


Popular (BPOP) Stock Still Seems Undervalued On Its 181% Three Year Run
Popular has delivered a powerful run for shareholders in recent years, which now puts a sharper spotlight on whether the current share price is properly backed by its earnings power. With the stock recently closing at US$158.88, the key issue is how that tag lines up with what the bank actually earns per share.
- Over the past 3 years, Popular has returned 180.7%, which raises the question of how much of that share price strength is supported by the underlying earnings profile.
- The bank relies on generating income from lending spreads, fees and disciplined credit risk, so any shift in profitability or loan quality can feed directly into what investors are paying for each dollar of earnings.
- The analysts covering Popular have run their own numbers. See what analysts think Popular's shares could be worth.
The stock's next move may depend on whether Popular's current earnings are strong and resilient enough to justify where the shares trade today.
If you want a quick comparison point for Popular's earnings story, it can help to line it up beside other banks and financials that pass a basic quality screen, such as 30 high quality undervalued stocks.
Is Popular Still Cheap on Earnings?
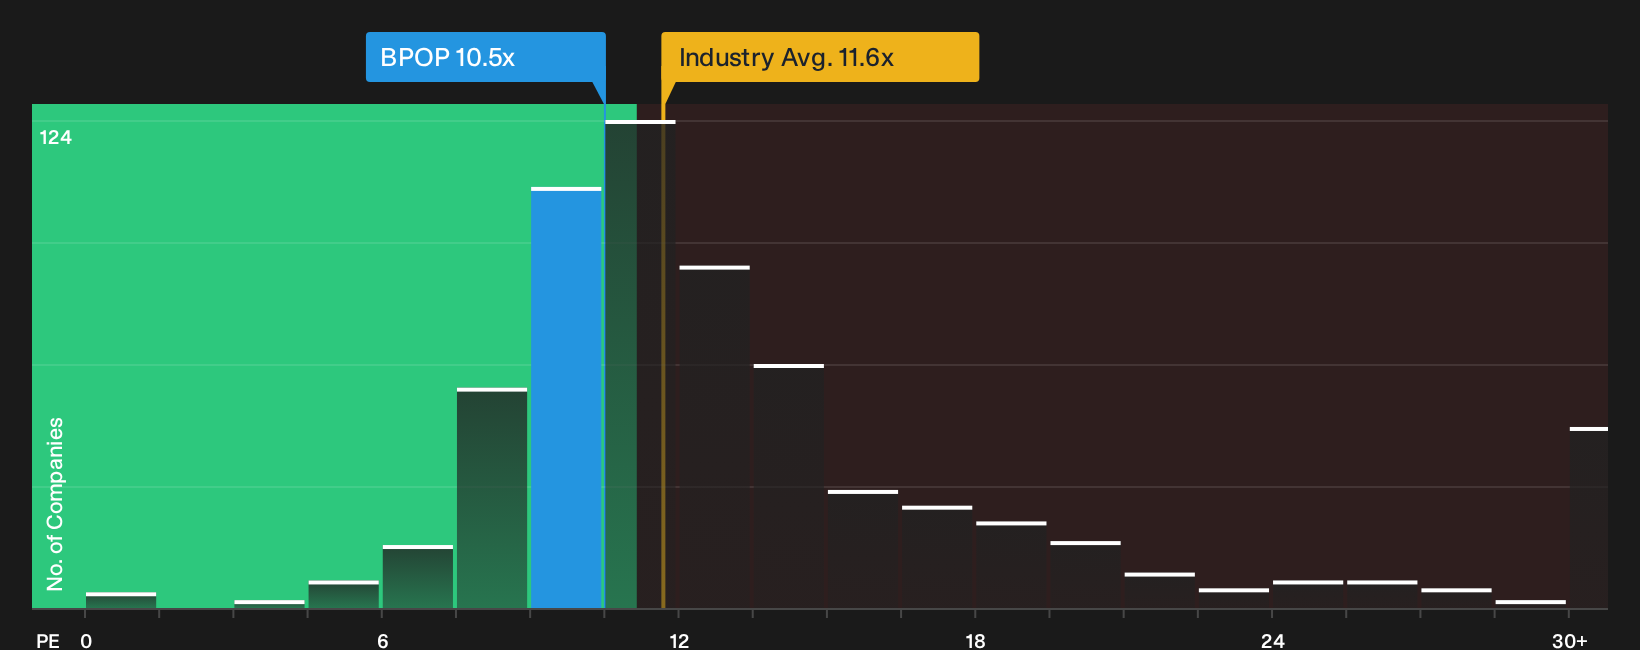
The P/E ratio tends to fit banks like Popular because earnings per share already reflect credit costs and interest margins that drive the business. On this measure, Popular trades on roughly 10.5x earnings, which is a small discount to both the broader banks industry on about 11.6x and the immediate peer group near 11.1x.
The fair multiple implied by Popular's own earnings quality, profitability profile and risk factors sits above where the stock currently trades. This points to the shares looking undervalued on this framework. For a holder, that gap suggests the market is pricing Popular more cautiously than its earnings power alone would indicate. However, you still need to weigh factors like loan growth, credit trends and capital returns before deciding how comfortable you are with that discount. Explore the numbers behind Popular's P/E valuation.
The Popular Narrative: What Would Justify Today's Price?
For Popular, Simply Wall St Narratives act as the missing link between that P/E puzzle and the expectations sitting behind it, because they spell out which paths for growth, margins and earnings would need to play out for the stock to be worth much more or much less than today. Instead of a single valuation output, they lay out the future story that number leans on so you can track whether Popular's actual progress still lines up with it over time on the Community page.
One of the top community narratives on Popular: 19% undervalued
"Ongoing investments in digital infrastructure, including Popular’s treasury and cash management platform, Mi Banco marketplace and branch upgrades, are starting to show through in higher debit and credit card fee income..."
Discover why this Narrative puts Popular at 19% undervalued.
Popular's share price is only one side of the decision
Before you anchor on Popular's valuation alone, it is worth knowing that Simply Wall St's checks have flagged specific risk signals that could change how you view the whole story. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com