


Murphy USA (MUSA) Stock Looks Fairly Valued On Cash Flow
Murphy USA has seen a strong share price run over recent years, which naturally raises a question for anyone looking at the stock today. Is the current market value properly grounded in the cash flows that the fuel and convenience retailer can generate over time?
- Murphy USA has delivered a 204.4% total return over the past 5 years, so a lot now depends on whether those gains line up with the strength and durability of its underlying cash flows.
- The business leans heavily on fuel volumes and in store sales to turn revenue into cash, which can shape how resilient its cash generation is through different pricing cycles and cost pressures.
- What if you looked at Murphy USA through its earnings instead? See why Murphy USA's 15.1x P/E tells a different valuation story.
The issue now is whether Murphy USA's recent share price level is fully supported by the intrinsic value implied by its cash flows.
If you want a wider starting point for research around cash flow led stories like Murphy USA, it can help to scan a focused list of 30 high quality undervalued stocks.
Is Murphy USA Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here uses Murphy USA's free cash flow today and projects what it could reasonably generate for shareholders over time. On the latest figures, the business produced roughly $535.4 million of free cash flow over the last twelve months, so the model is anchored in a meaningful current cash base rather than a purely theoretical future story.
Analysts then expect Murphy USA's annual free cash flows to stay in the hundreds of millions of dollars over the coming years, with the 2 Stage Free Cash Flow to Equity approach assuming this pot of cash grows at a measured pace before easing into more modest expansion. When those projected streams are discounted back and compared with the current share price of $506.24, the DCF framework suggests Murphy USA's estimated intrinsic value is broadly in line with where the stock trades today. Find out what Murphy USA could be worth using our Discounted Cash Flow (DCF) estimate.
The Murphy USA Narrative: What Would Justify Today's Price?
Murphy USA's valuation puzzle only really comes into focus once you spell out the specific futures that could justify very different prices, which is where Simply Wall St Narratives come in as a bridge between today's DCF output and the assumptions you think are realistic on growth, margins and earnings. Each narrative links its number to a clear view of how Murphy USA's economics and risks might evolve, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on Murphy USA: 8% undervalued
"The main thing that has to go right is that Murphy USA continues to execute on high return new store openings, digital loyalty driven pump to store conversion, and nicotine category growth…"
Discover why this Narrative puts Murphy USA at 8% undervalued.
One more detail on Murphy USA that could change the story
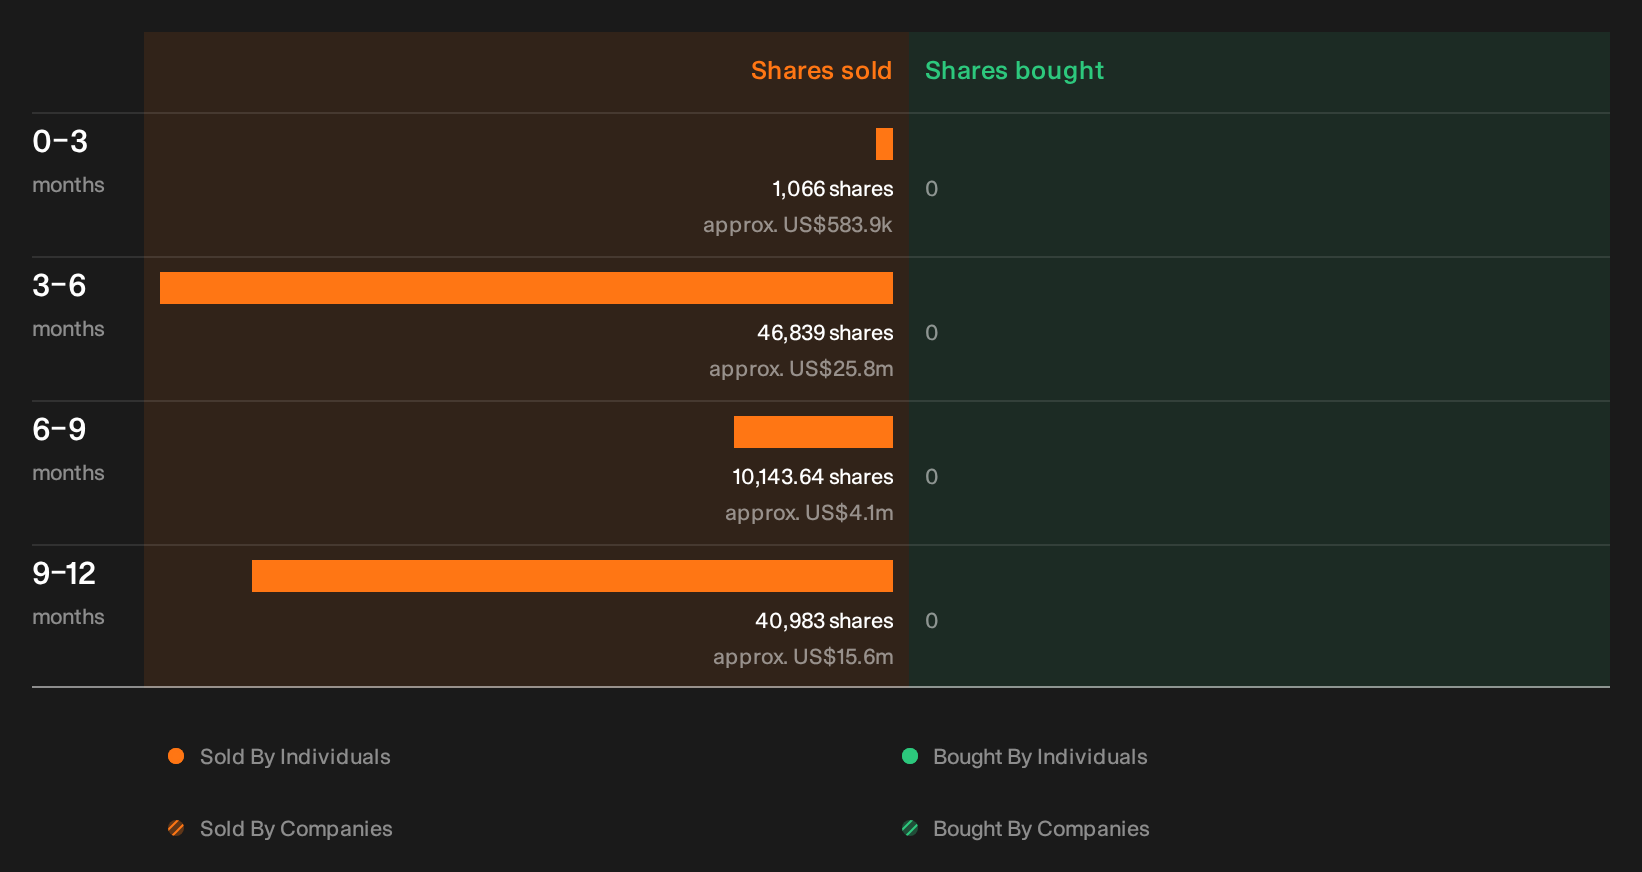
Before closing the book on Murphy USA, it is worth knowing that recent trades by people inside the business have triggered a fresh set of questions about who sold, how much, and why. See the recent insider selling flagged for Murphy USA.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com