


Sandisk (SNDK) Stock May Be Undervalued On Fresh AI Slowdown Fears
Sandisk has delivered one of the strongest share-price runs in the market over the past year, which naturally raises a blunt question for anyone looking at the stock today. Is the current valuation still grounded in what the business earns, or has the price pulled away from its earnings power.
- Over the past 12 months, Sandisk has delivered a very large 1 year return, which puts a lot of pressure on the earnings story to carry that move.
- Fresh headlines around AI related spending, new competition from China and shifting sentiment in chip demand can all feed directly into how investors frame Sandisk's future profit and cash generation potential.
- There is a second opinion on Sandisk worth weighing. See what analysts think Sandisk's shares could be worth.
The issue now is whether Sandisk's current share price is justified by the earnings that the business is generating and is expected to generate.
If you are weighing Sandisk after this AI driven run, it can help to compare it with a wider set of AI infrastructure plays using 86 AI infrastructure stocks.
Is Sandisk Still Cheap on Earnings?
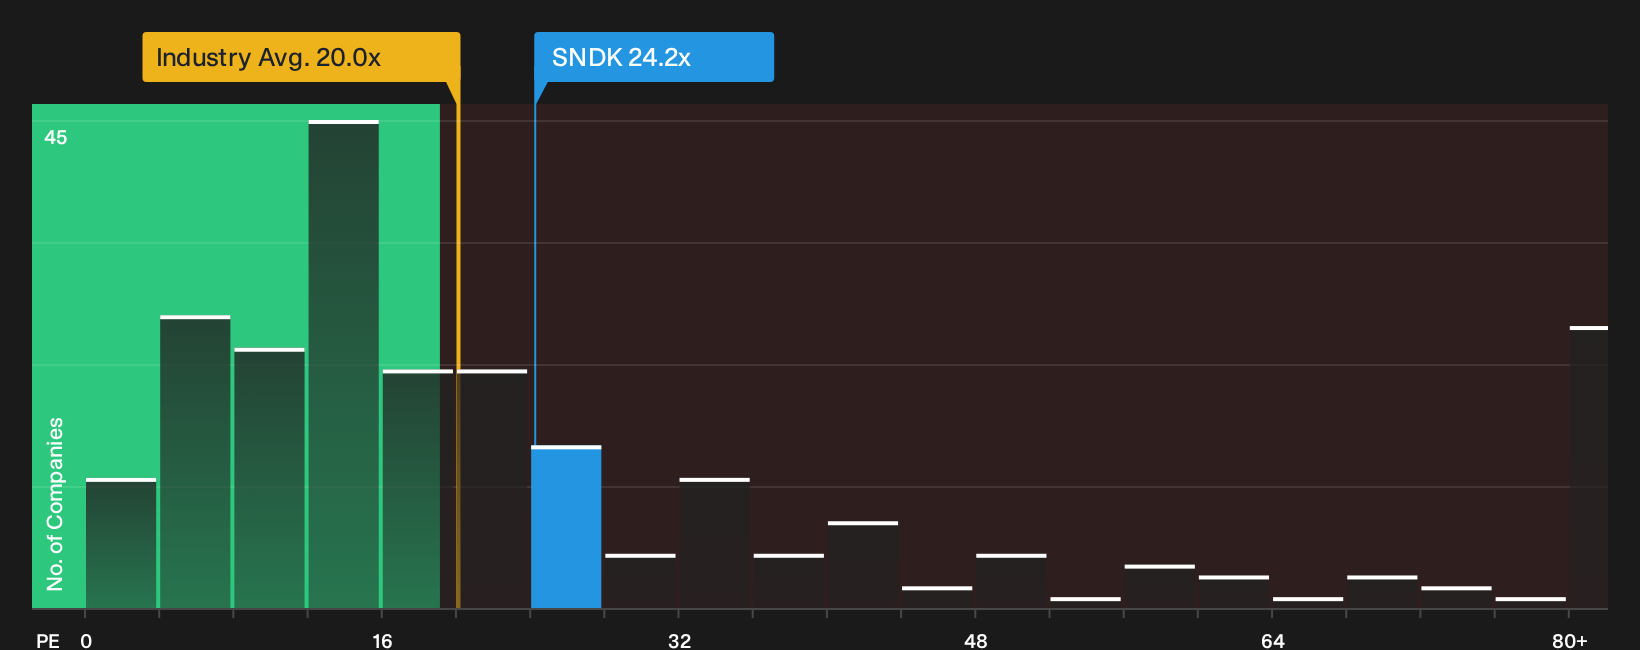
The P/E ratio is a useful yardstick for Sandisk because earnings are a key focus for investors trying to size up its AI driven opportunity. Sandisk trades on a P/E of 24.2x, which is lower than the wider tech industry average of about 20.0x. That puts the stock on a premium to the sector in absolute terms, but not at the eye watering levels sometimes seen in hot AI hardware plays.
Despite the recent pullback after the Anthropic essay on slowing AI development, the current P/E still sits below the peer group average of 36.2x and below the multiple implied by a more tailored fair value framework that blends growth, margins, size and risk. The model suggests the earnings multiple leaves Sandisk looking undervalued on this measure. The question for you is whether the profit stream backing that ratio feels robust enough to close that gap over time. Explore the numbers behind Sandisk's P/E valuation.
The Sandisk Narrative: What Would Justify Today's Price?
Narratives on Sandisk pick up where this P/E puzzle leaves off by explaining which paths for future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today. Each one links its number to a clear view on how Sandisk's business mix, profitability and risk profile might evolve, giving you a reference point you can revisit as fresh information comes through on Simply Wall St's Community page.
Community narratives on Sandisk are pulling in very different directions around how durable the AI memory story really is.
Bull case: 43% undervalued
"The mix shift toward high value enterprise SSDs and QLC-based ultra-high-capacity drives, combined with full fab utilization and disciplined CapEx, supports sustained gross margin expansion and increasing earnings leverage on incremental revenue..."
Discover why this Narrative puts Sandisk at 43% undervalued.
Bear case: 89% overvalued
"Any easing in AI driven exabyte demand or faster industry wide wafer and node additions could pressure NAND pricing, which would weigh directly on revenue and gross margin progression..."
Explore why this Narrative puts Sandisk at 89% overvalued.
Sandisk’s price still leaves one crucial angle unresolved
Big moves in valuation are only part of the picture, because the people steering Sandisk and the way their pay packages line up with your priorities can heavily shape what happens next. See who runs Sandisk and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com