


3 UK Large Cap Stocks Worth Watching For Global Earnings Strength
UK fiscal policy is back in focus, and this time the story is about rules, scrutiny and how comfortably companies can plan around them. With cross-party backing for an independent watchdog and talk of longer term forecasts, investors watching large UK-listed stocks with meaningful global earnings may see this as a rare window to reassess exposure before pricing shifts. This article highlights three quality UK large caps that appear positively exposed to this policy backdrop and sets out why each one may merit closer attention.
The three stocks that follow are only a sample of what fits this idea, since the wider screen surfaced 13 more large UK-listed businesses with similar quality markers and international footprints that are not included below. To see the full list and start sorting for your own highest conviction setups, head straight to the UK quality large-cap equities with policy and global earnings support screener.
Smiths Group (LSE:SMIN)
Smiths Group fits this UK quality large-cap theme as a London headquartered industrial technology specialist with a long history, a sizeable global footprint and a balance of cash returns and reinvestment that can matter when policy stability improves confidence in UK listed exporters.
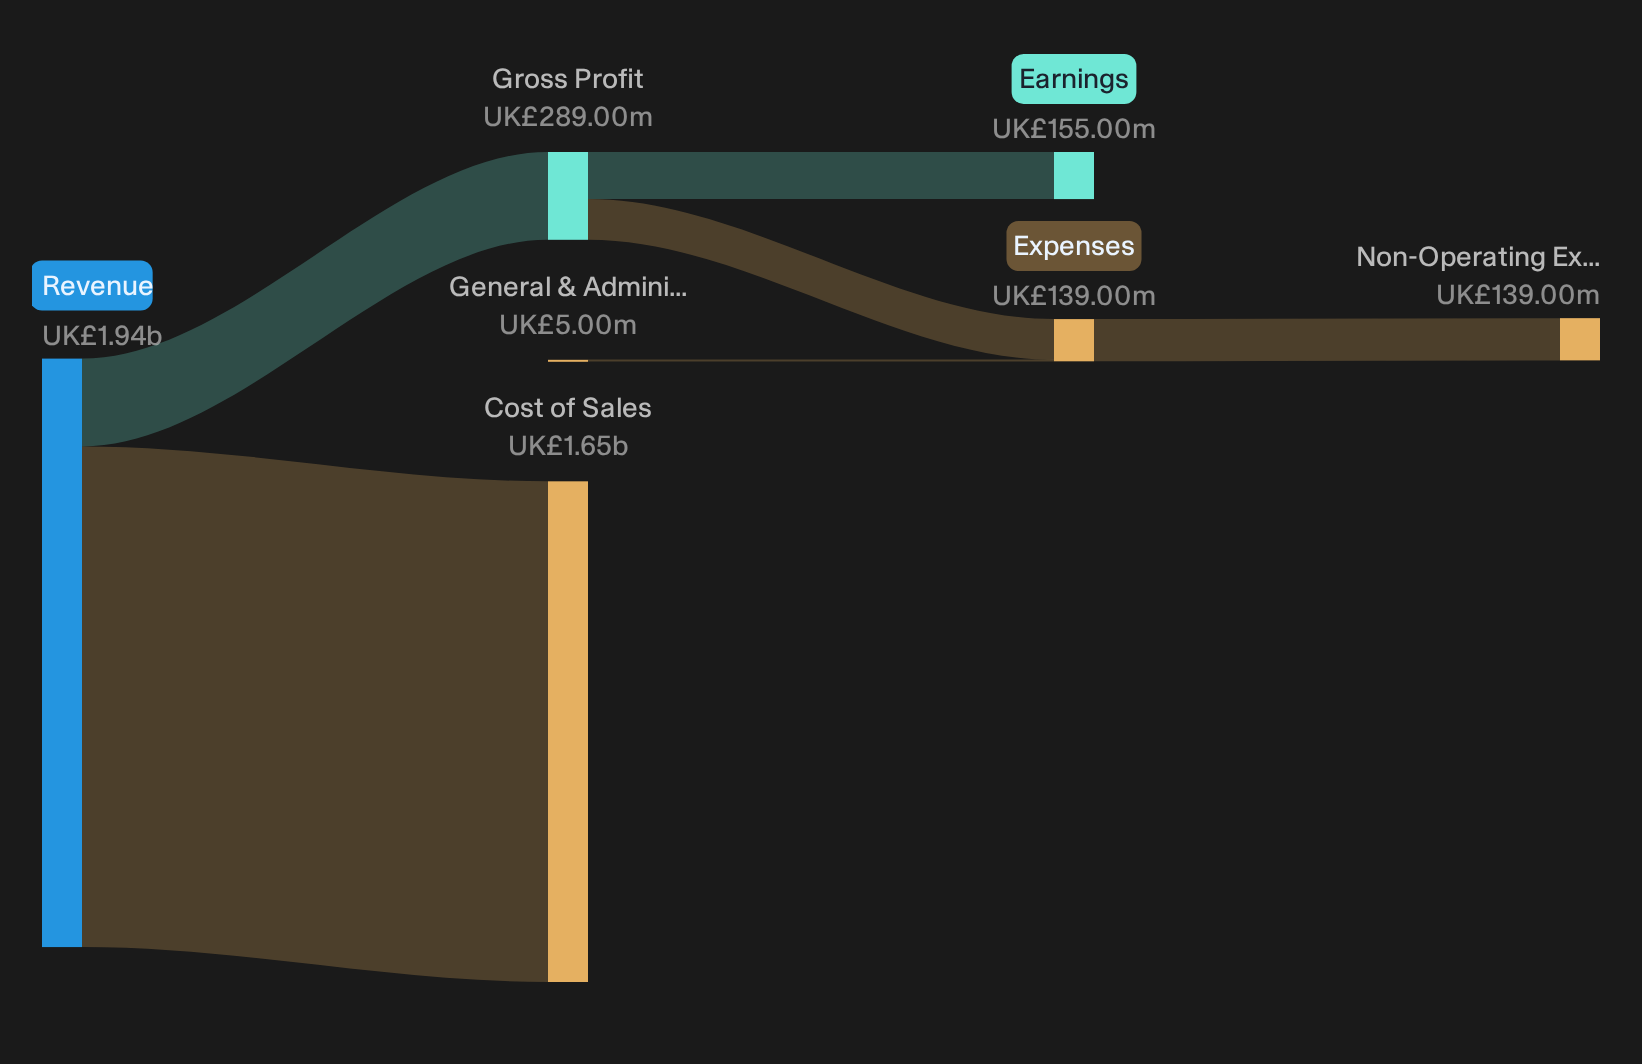
Smiths Group plc is an industrial technology business supplying seals, sensors, tubing, hosing and secure connectivity hardware to industrial, energy, safety, security and aerospace customers worldwide, and currently carries a market value of about £8.2b.
"Smiths Group is increasing its focus on high-performance technologies for efficient flow and heat management, intending to streamline operations and enhance margins through the sale or demerger of Smiths Interconnect and Smiths Detection."
The real test for Smiths Group will come from how one unresolved pressure on its earnings mix ultimately feeds through to margin credibility.
That pressure point is exactly where the story gets interesting, and the full narrative for Smiths Group shows how Smiths Group could turn today’s mix into tomorrow’s advantage.
GSK (LSE:GSK)
GSK brings a different flavour to this UK quality large-cap theme, with a London base, a global footprint and a portfolio tied directly to long term healthcare demand rather than domestic spending cycles. This is why the pipeline and patent story matters so much here.
GSK is a London headquartered pharmaceuticals group focused on vaccines, specialty treatments and everyday medicines, generating about £33.2b from its Commercial Operations segment and carrying a market value of roughly £76.4b, which places it firmly in the global large-cap bracket.
"GSK is well-positioned to benefit from the global rise in demand for vaccines and specialty medicines, driven by an aging population and higher healthcare access in emerging markets, evidenced by robust ongoing growth in Shingrix, meningitis vaccines, and double-digit expansion in specialty medicines. Loss of exclusivity for key drugs, notably dolutegravir in HIV and respiratory products, is flagged as a future revenue risk. Patent expiries post-2028 could hit earnings and net margins, especially if new launches like Blenrep face timing risks or fail to compensate for these losses."
What happens to valuation and cash returns if one pressure point in that future product mix does not break the way current expectations imply.
If that earnings pressure really bites, full narrative for GSK shows how GSK’s pipeline, cash generation and patent cycle could still be quietly resetting expectations higher.

Bunzl (LSE:BNZL)
Bunzl is a London based distributor of everyday consumables like safety gear, cleaning supplies and food packaging, squarely in the UK quality large cap camp with international earnings. Packaging and containers bring in about £12b of sales, and the stock is valued at roughly £8.6b.
Bunzl matters here because it links a UK listing and balance sheet discipline to a broad stream of global cash flows, which is exactly the mix this screener is designed to surface.
"The turnaround of the North America Distribution business, which suffered from over-centralization and execution missteps but is now regaining local autonomy, improving service and inventory levels, and re-energizing sales teams, sets the stage for a recovery in revenue growth and operating margin beginning in H2 2025 and accelerating through 2026, though current results do not yet fully reflect these improvements."
What that could mean for Bunzl’s future appeal hinges on how one quiet shift in its earnings mix ultimately lands in the margin line.
If that shift really takes hold, full narrative for Bunzl shows how Bunzl’s recovering North American arm, consolidation track record and margin profile could quietly re-rate the whole group.

Seeking Alternatives Before Momentum Flies
Fresh stock ideas can move quickly when momentum builds and early data points start stacking up. Consider researching any potential opportunities promptly.
- Track cash rich businesses built to withstand shocks and look for resilient balance sheets inside the curated list of solid balance sheet and fundamentals (10 results) before they become widely followed.
- Explore potential income opportunities by scanning high yield candidates tagged as 1 dividend fortresses while payouts and share prices may still be less widely tracked.
- Review companies positioned for possible infrastructure developments and sift through carefully filtered 40 power grid technology and infrastructure stocks while valuations still reflect current expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com