


Learn Why The Bull Case For EMCOR Group Stock Could Change Following Earnings Estimate Upgrades
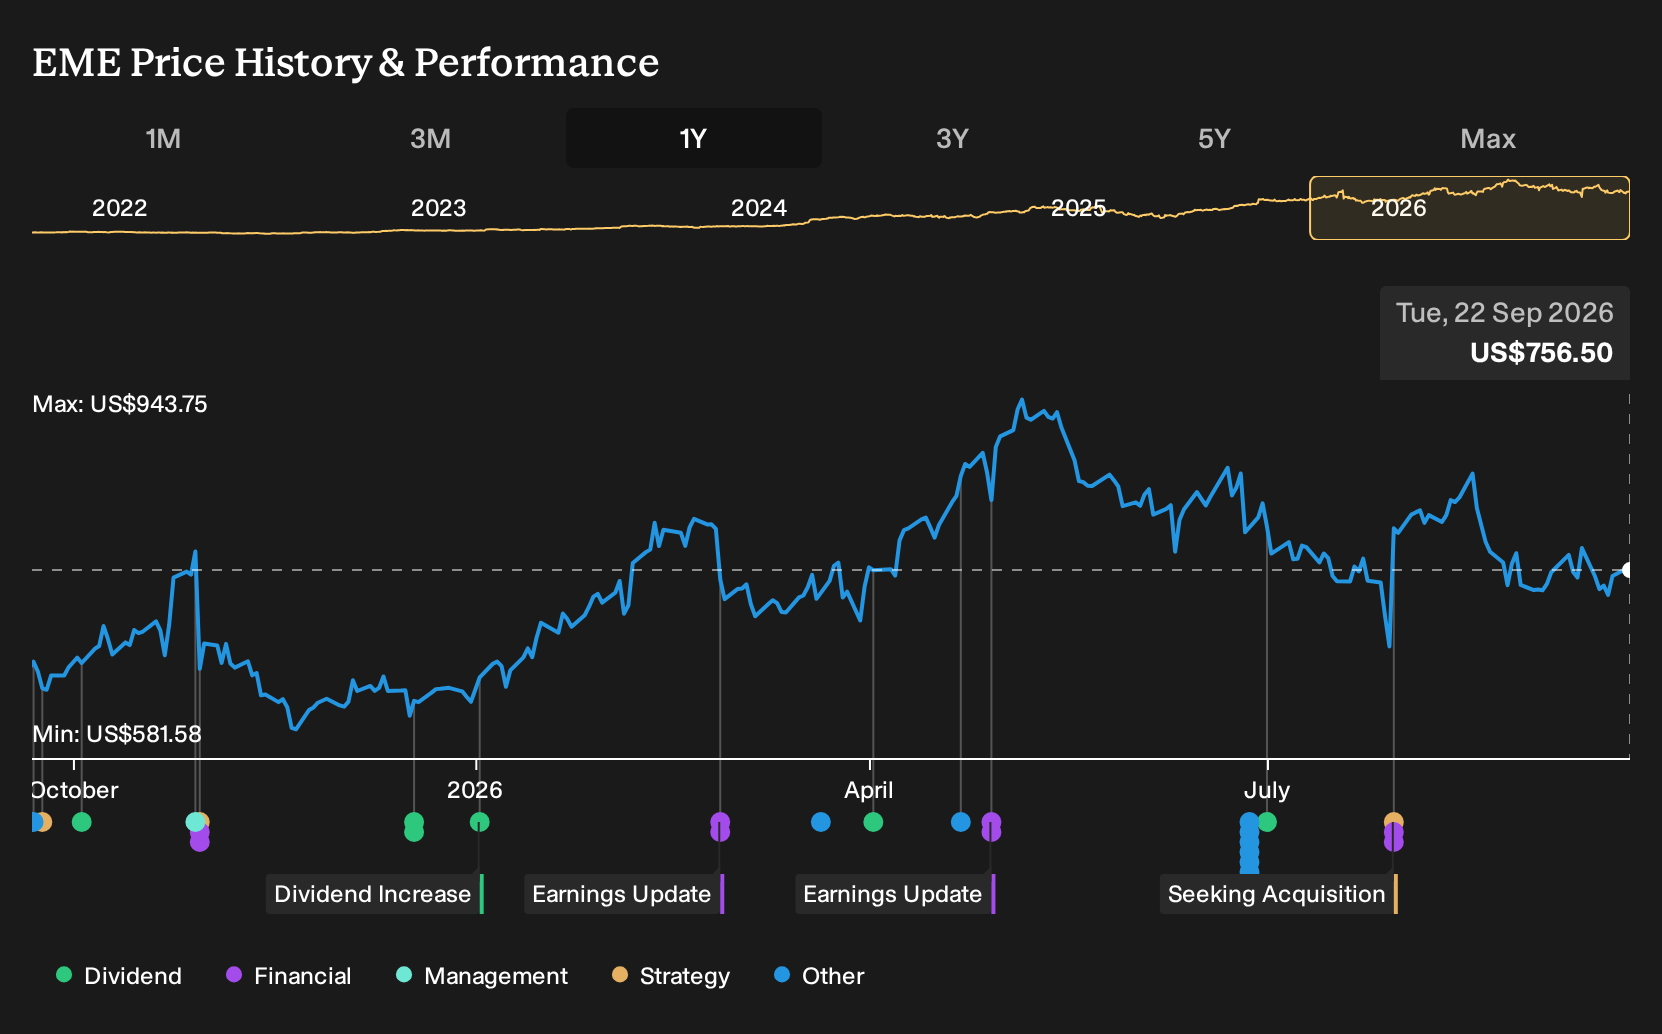
- EMCOR Group recently appeared at Morgan Stanley's 14th Annual Laguna Conference in California, where senior leadership outlined current operations and financial planning priorities for the contracting and services business.
- Recent earnings estimate revisions now indicate projected gains in both EPS and revenue, which reflects how analysts view EMCOR Group's backlog, cost structure and project mix as supportive for profitability.
- We will now examine how EMCOR Group's updated earnings estimates could influence the broader investment narrative around the business.
Scan how EMCOR Group compares with other contractors and services stocks that analysts see as potential earnings movers using our curated list of 29 high quality undervalued stocks.
EMCOR Group Investment Narrative Recap
For EMCOR Group, the big-picture belief is that it can keep turning its record Remaining Performance Obligations and strong data center exposure into steady project execution without giving up too much margin. In the near term, the story hinges on converting that large, complex backlog efficiently while keeping project schedules under control across mechanical, electrical, and services work.
The biggest swing factor right now is margin pressure from more prime contractor roles and a heavier guaranteed maximum price and cost plus contract mix, on top of tight labor markets. The Laguna conference commentary does not appear to change that equation in a material way, but it helps clarify how leadership is thinking about productivity and cost control.
The most relevant recent item for this context is EMCOR Group’s presentation at Morgan Stanley’s 14th Annual Laguna Conference in September 2026. Management used that forum to walk through current project pipelines, Remaining Performance Obligations, and capital spending on prefabrication and Virtual Design and Construction tools, which sit at the center of near-term execution.
For you as a shareholder or prospective investor, the interest lies in how these tools, contract choices, and acquisitions feed into future earnings quality and project risk. Analyst estimate revisions around EPS and revenue provide one lens on that, but the core test remains operational. EMCOR Group needs to show it can keep complex AI data center and infrastructure work on budget while managing labor costs.
EMCOR Group's narrative projects US$25.3b revenue and US$2.0b earnings by 2029. This assumes 10.9% yearly revenue growth and an earnings increase of about US$0.6b from US$1.4b today.
Uncover why EMCOR Group's fair value indicates a 37% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts see EMCOR Group very differently. They focus on a possible surge in high margin recurring service work, with bullish forecasts pointing to US$27.3b in revenue and US$2.3b in earnings by 2029, versus the baseline US$25.3b and US$2.0b. Those projections all pre date the Laguna conference, so opinions may evolve as new details filter through.
Explore 5 other EMCOR Group fair value estimates, including one that suggests as much as 78% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EMCOR Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for EMCOR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EMCOR Group's overall financial health at a glance.
Looking For More EMCOR Group Style Investment Ideas?
If EMCOR Group has sharpened your interest in capital projects and services, it can be useful to line this thesis up against other opportunities that share similar qualities or offer a very different risk profile.
- For investors who want potential upside with tighter risk controls, check out a 30 resilient stocks with low risk scores that may help you focus on businesses with more resilient profiles.
- If you prefer companies with healthier funding and less balance sheet stress, start with a list of solid balance sheet and fundamentals (23 results) that screens for stronger financial foundations.
- Those hunting for under the radar opportunities can review a 16 high quality undiscovered gems that highlights quality stocks which do not yet attract as much market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com