


ManpowerGroup (MAN) Could Be 69% Below Fair Value After Its Latest Valuation Check
Recent trading in ManpowerGroup (MAN) has caught investor attention after the stock moved around its intrinsic discount estimate and recent performance figures, prompting fresh interest in how the workforce solutions provider is being valued.
Short term momentum for ManpowerGroup has cooled, with a 30 day share price return of down 6.22% and a 7 day share price return of down 1.40%. However, the 90 day share price return of 76.83% and 1 year total shareholder return of 62.03% still point to a strong rebound from earlier weakness and frame the latest move around its intrinsic discount as part of a broader rerating story. Spot opportunities beyond ManpowerGroup by scanning our curated 29 high quality undervalued stocks, which focuses on fundamentals and potential rerating stories.For ManpowerGroup, the recent swing around its intrinsic discount raises a simple tension. Are investors reassessing the underlying workforce business, or just cycling through a sentiment shift that the current valuation does not fully capture yet?
Most Popular Narrative: 1% Overvalued
ManpowerGroup is trading close to the most followed fair value estimate of $57.33, with the last close at $57.63, so the small premium hinges on whether the market agrees with the growth and margin story embedded in that narrative.
ManpowerGroup's ongoing investment in AI-driven digital platforms like PowerSuite and Sophie AI is accelerating operational efficiency, enabling more precise sales targeting and automation of recruiting workflows, which should drive scalable revenue growth and net margin expansion as these tools are deployed across more regions and business lines.
See why 9 investors see ManpowerGroup as 1% overvalued.
Result: Fair Value of $57.33 (OVERVALUED)
Still, the ManpowerGroup story can be knocked off course if AI and automation reduce demand in core staffing categories, or if Northern Europe continues to drag on profitability.
Find out about the key risks to this ManpowerGroup narrative.
Another View: ManpowerGroup Through The Cash Flow Lens
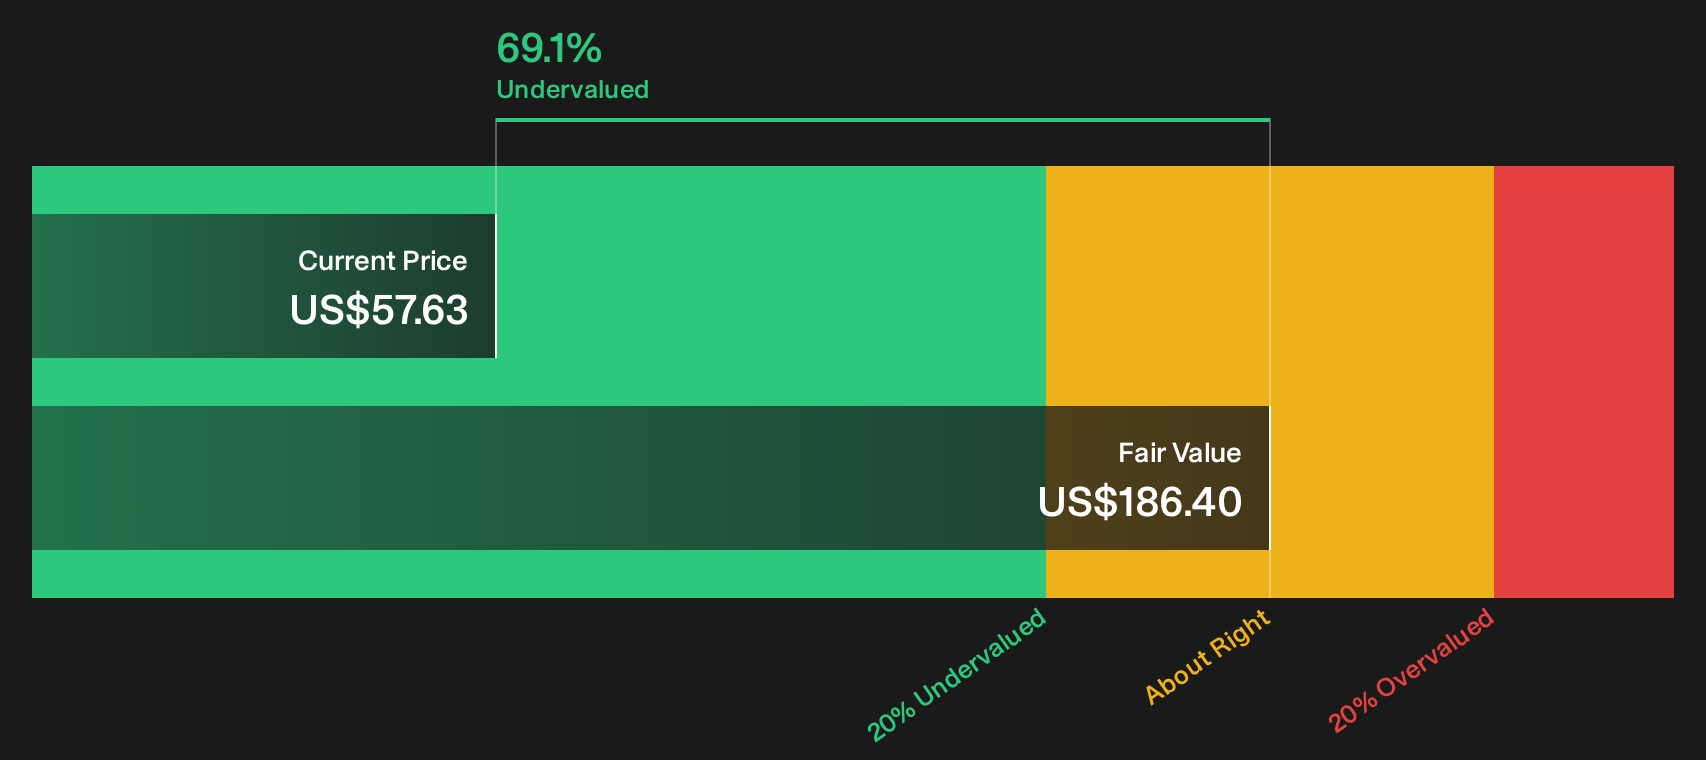
The analyst fair value of $57.33 paints ManpowerGroup as roughly fully priced, yet the SWS DCF model points in a very different direction. On that framework, the stock at $57.63 trades around 69% below its estimated future cash flow value of $186.40, which implies a wide valuation gap that investors need to explain for themselves. Is this a genuine disconnect, or is the cash flow model too generous about how much earnings power ManpowerGroup can sustain?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around ManpowerGroup can make the story feel murky. Use this moment to move quickly, review the full picture, and weigh both the upside and the downside by checking the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond ManpowerGroup?
Do not stop with ManpowerGroup. Use this same momentum to scan fresh opportunities tailored to your style before the next wave of reratings gets crowded.
- Hunt for companies that combine quality with potential mispricing by running your filters through the 16 high quality undiscovered gems.
- Prioritise strength and resilience by checking which tickers clear your thresholds in the list of solid balance sheet and fundamentals (23 results).
- Dial down portfolio volatility and focus on stability by reviewing candidates surfaced through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com