


3 Japanese Value Stocks Trading Up To 40% Below Fair Value
With the Federal Reserve lifting interest rates again and borrowing costs climbing, global investors are paying closer attention to companies that can fund themselves through strong internal cash generation rather than cheap debt. That is where undervalued Japanese cash flow stocks come in. This article highlights three opportunities from our cash flow focused screener that appear mispriced relative to their projected cash streams, and explains why each might deserve a spot on your watchlist.
The three ideas below are only a small sample, as the full screen surfaced 36 more companies with cash flow stories that look just as compelling but are not covered here. To assess the wider opportunity set, head straight to the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and prioritize the highest conviction setups for your own watchlist.
Canon (TSE:7751)
Canon is a diversified Japanese manufacturer of printers, cameras, medical imaging systems, and industrial equipment, with its office printing and managed document solutions arm providing the most direct tie to strong, recurring cash flows that fit this screener’s theme. The group is sizeable, with a market value around ¥3,824.6b.
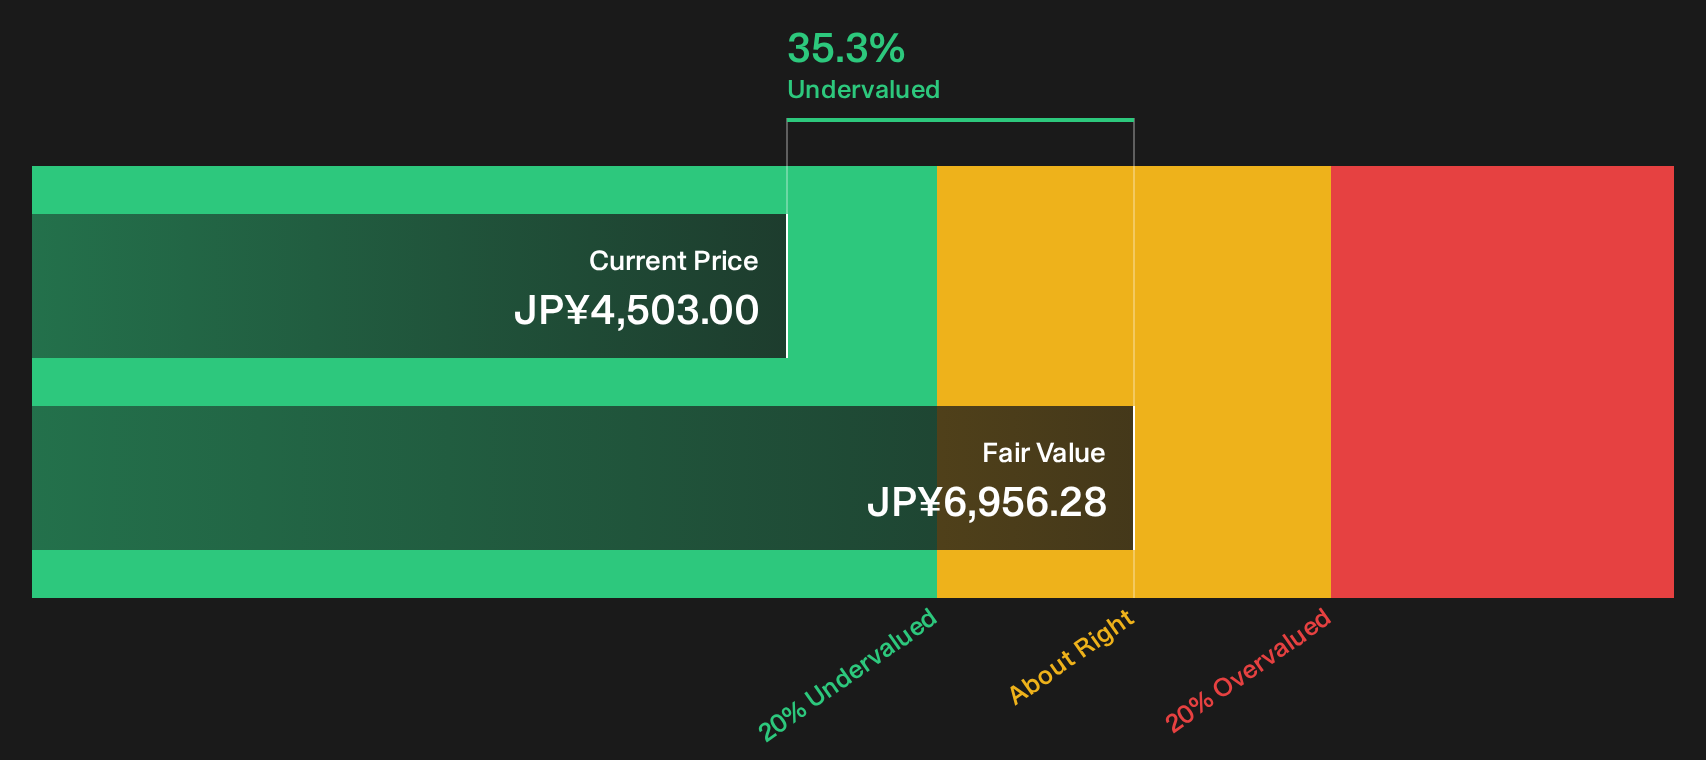
Canon screens as potentially undervalued, trading about 35.3% below SWS’s cash flow based fair value estimate. Its printing unit generates recurring revenue from hardware, consumables, and service contracts. That combination of discounted cash flows and steady printing economics is appealing, depending on how one unseen pressure on that recurring stream plays out.
That pressure point is exactly why the 4 key rewards and 1 important warning sign could be worth a look, as it shows how Canon’s cash engine and vulnerabilities really stack up.
Astellas Pharma (TSE:4503)
Astellas Pharma is a global drug maker built around prescription treatments in oncology, ophthalmology, urology and women’s health, where its marketed cancer therapies feed directly into the screener’s recurring cash flow theme. Pharmaceutical sales total ¥2,274.4b, and the group’s market value is about ¥4,273.6b.
For investors focused on undervalued cash flow potential, Astellas Pharma offers a clear test case of how a high margin oncology portfolio can support long term valuation, while the rest of the pipeline and pricing decisions shape how durable those cash streams really are.
"Patent expirations for key drugs such as XTANDI and mirabegron threaten to create substantial revenue and earnings losses as generic entrants erode Astellas' market share in critical therapeutic areas over the next several years."
What matters most for this screener is how management responds if a single cash flow assumption around that core oncology engine starts to shift.
If that oncology cash engine is starting to shift, the full narrative for Astellas Pharma outlines how expiry risks, pipeline execution and pricing power could be decoupling worries from Astellas Pharma's long term potential.

Terumo (TSE:4543)
Terumo leans on a broad mix of medical devices, yet its Medical Care Solutions and Cardiac & Vascular units, built around high volume consumables and interventional gear, are what tie it to this cash flow focused screener, with revenue of ¥706.7b and ¥222.3b respectively and a market value near ¥3,301.3b.
For investors scanning for undervalued cash flow stories, Terumo offers a useful test case of how repeat use devices and long life catheters can translate predictable demand into a valuation gap that might still be open.
"Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects and positioning the company for future revenue growth in this key emerging market."
What ultimately matters is how one less visible shift in pricing power and mix flows through to future margins and free cash generation.
That shift is exactly where the full narrative for Terumo shows whether Terumo's pricing power, product mix and cash generation are quietly accelerating beyond what headline revenues suggest.

Seeking Fresh Alternatives Before They Fly
Breakout stories rarely stay under the radar for long. Momentum builds, prices move, and ideal entry points can become harder to find. Scan these fresh ideas now and consider them early.
- Spot resilient performers before the crowd by scanning a curated set of steady compounders with the 21 resilient stocks with low risk scores to help keep downside risk tightly controlled.
- Track the power grid upgrades reshaping energy infrastructure using a focused list built from the 40 power grid technology and infrastructure stocks to explore companies that may still be overlooked.
- Follow trends in automation by focusing on curated industrials and tech hardware within the 95 robotics and automation stocks before more capital potentially moves into the space.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com