


Will Long Term Partnering Deal Change NCC Stock Narrative
- NCC has recently announced a ten year partnering agreement for multiple construction and civil engineering projects worth an estimated SEK 3–5b, alongside several large public and private contracts in Sweden, Finland and Denmark that span offices, care facilities and government premises.
- Together, these agreements point to a thicker project pipeline for NCC, with long duration work structured in partnering and alliance models. This can influence capacity planning, risk sharing and the mix of Swedish and Nordic public sector exposure in the order book.
- We will now assess how NCC's new long term partnering contract could reshape the existing investment narrative around balance sheet strength.
Scan a curated set of Nordic construction and infrastructure peers with long term contracts and public sector exposure by checking the list of solid balance sheet and fundamentals (197 results) to compare them with NCC's latest deals.
NCC Investment Narrative Recap
To own NCC, you need to believe in a contractor that leans heavily on large, complex Nordic projects and can turn its sizeable order book into steadier earnings, despite thin recent margins and a heavy debt load. The key near term swing factor remains execution on existing contracts while keeping pricing discipline against smaller rivals in Sweden and Finland.
The new ten year partnering deal and recent public sector wins support visibility on future activity, but they do not remove the main risk. Profitability can still be pressured if property transactions stay muted, the krona strengthens against Nordic currencies, or tender competition forces lower prices on less complex work.
The long term partnering agreement worth an estimated SEK 3 to 5 billion looks most relevant for the current thesis. It feeds straight into NCC Infrastructure and NCC Building Sweden, where analysts already expect earnings to grow strongly and see upside based on current P/S and DCF metrics. The interest is less about the headline size and more about duration and repeat work.
For catalysts, this arrangement helps frame how NCC might use its balance sheet flexibility and low net debt to pursue selective M&A from a position of contracted volume. At the same time, it raises the bar on delivery. Any cost overruns, currency headwinds or delays across these long dated projects could matter for cash flow that supports a dividend already flagged as not fully covered by earnings and free cash.
NCC's current analyst narrative points to SEK 64.5b in revenue and SEK 2.7b in earnings by 2029, built on an assumed 6.1% yearly increase in revenue and an earnings move of roughly SEK 2.6b from SEK 78.0m today to the projected level.
Uncover how NCC's fair value indicates a 12% potential upside to its current price before investors factor in the new contract pipeline.
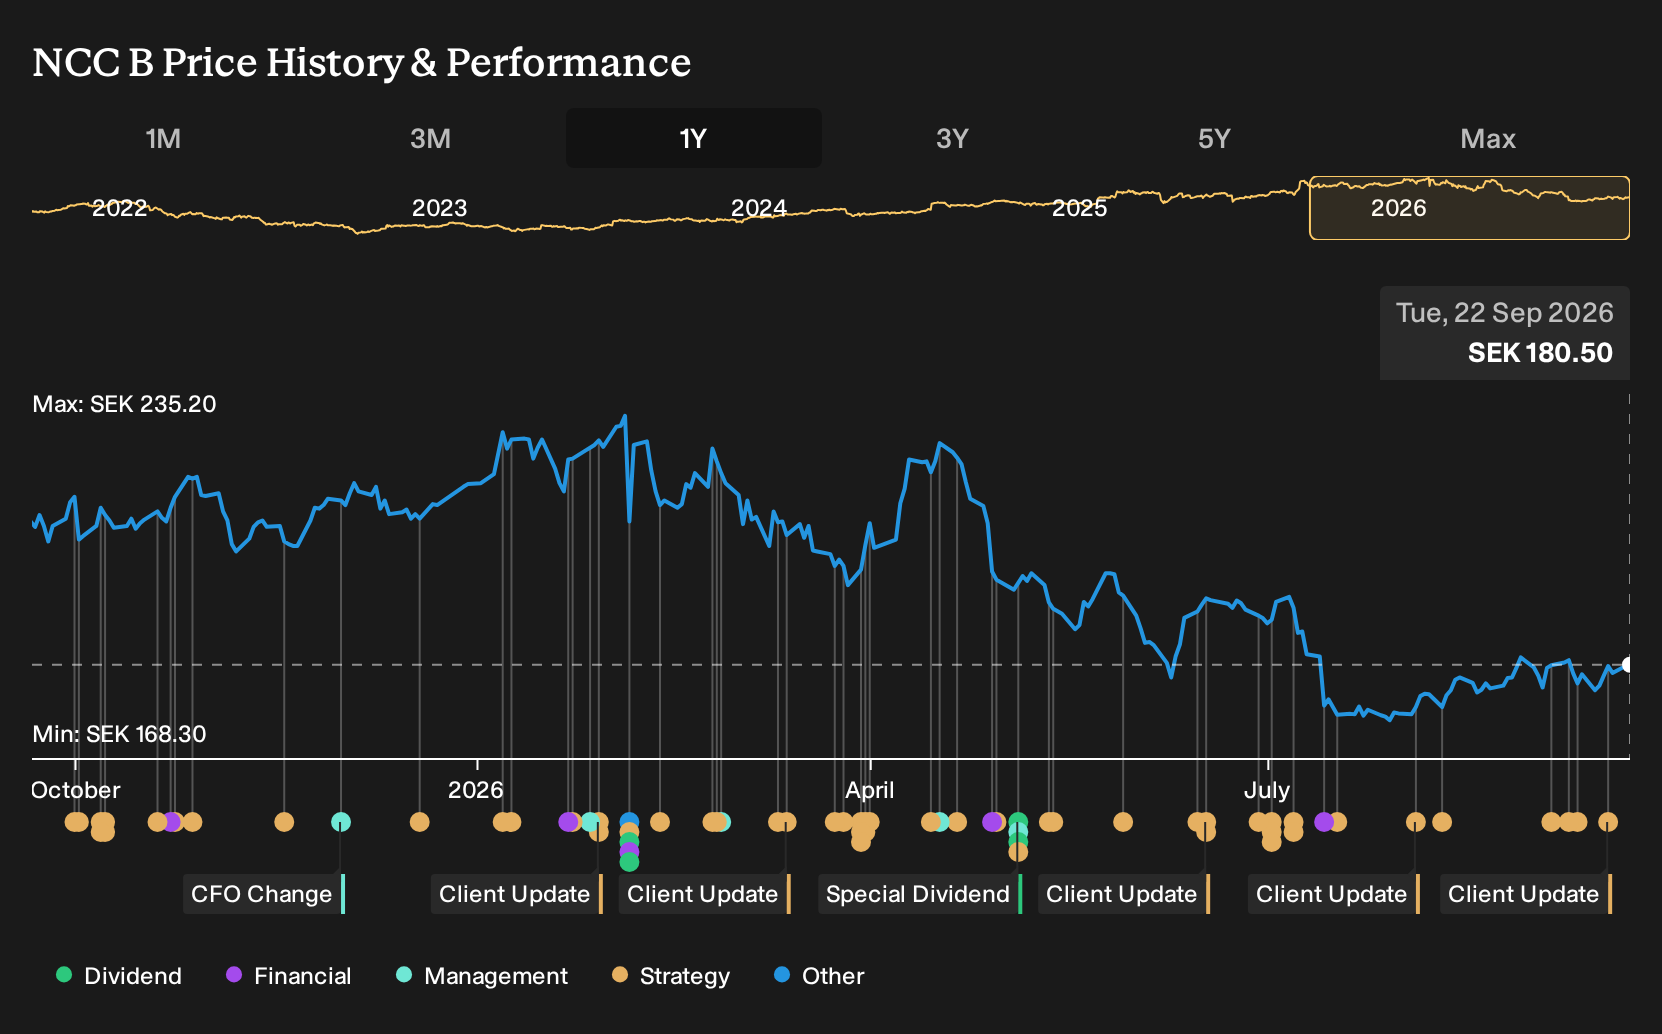
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between about SEK 201.55 and SEK 202.50, which indicates that retail views on NCC are concentrated rather than scattered. Those models were set before the latest partnering and public sector contracts, so you may want to weigh them against currency risk, pricing pressure and the longer dated order commitments now emerging.
Explore 2 other NCC fair value estimates, including one that suggests as much as 12% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NCC research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for NCC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCC's overall financial health at a glance.
Looking for more investment ideas beyond NCC?
If this NCC review has sharpened your view on contractors with long term agreements, it can help to widen the lens and see how other businesses with different balance sheet profiles and cash flow patterns line up beside it.
The Simply Wall St Screener lets you filter for specific traits, then compare fundamentals side by side in a structured way.
- If you want potential mispricing with quality in mind, scan a curated group of resilient companies through the 174 high quality undervalued stocks and see how they stack up against NCC in terms of financial strength and valuation.
- For readers who want income reliability to sit alongside construction exposure, use the 160 dividend fortresses to find businesses offering higher yields supported by stronger coverage metrics.
- If capital protection and balance sheet resilience matter most, focus on stability first by screening for companies with lower risk scores using the 230 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com