


Why Did DFDS (CPSE:DFDS) Move Today?
DFDS operating update and leadership reshuffle
DFDS (CPSE:DFDS) has drawn attention after reporting August operating figures that show largely unchanged freight volumes alongside fewer passengers, combined with board changes and a new Chief Digital & Information Officer appointment.
At a share price of DKK172.7, DFDS has seen strong momentum build recently, with a 1-day share price return of 6.34% and a 90-day share price return of 41.79%. The 1-year total shareholder return of 72.79% contrasts with a 3-year total shareholder return that declined 23.16% and a 5-year total shareholder return that fell 48.57%. This points to a sharp rebound in sentiment after a weaker longer run as investors react to the steady freight figures and the leadership reshuffle.
Scan how other transport and logistics stocks are reacting to similar operating updates and leadership shifts with the hand picked list of solid balance sheet and fundamentals (198 results).
After DFDS jumped on steady freight data and fresh leadership, the real tension now is simple: does the current price still leave enough upside to compensate for the risks you are taking on?
Most Popular Narrative: 6% Overvalued
On the most followed narrative, DFDS carries a fair value estimate of DKK163.5 against a last close of DKK172.7. That story frames the recent rally as slightly ahead of the implied worth while still hinging on execution in ferries and logistics.
The progress from the eight ongoing Logistics Boost projects, a program that has already turned collectively positive and seen five units exit with >3% EBIT margins, indicates meaningful operational improvements and margin uplift potential for the logistics division, helping to drive overall EBITDA and net margin growth.
See why 12 investors see DFDS as 6% overvalued.
Result: Fair Value of DKK163.5 (OVERVALUED)
Still, pressure in loss making Mediterranean routes and uncertainty around competitive pricing on corridors like Istanbul Trieste could quickly challenge the current DFDS fair value story.
Find out about the key risks to this DFDS narrative.
Another View on DFDS Valuation
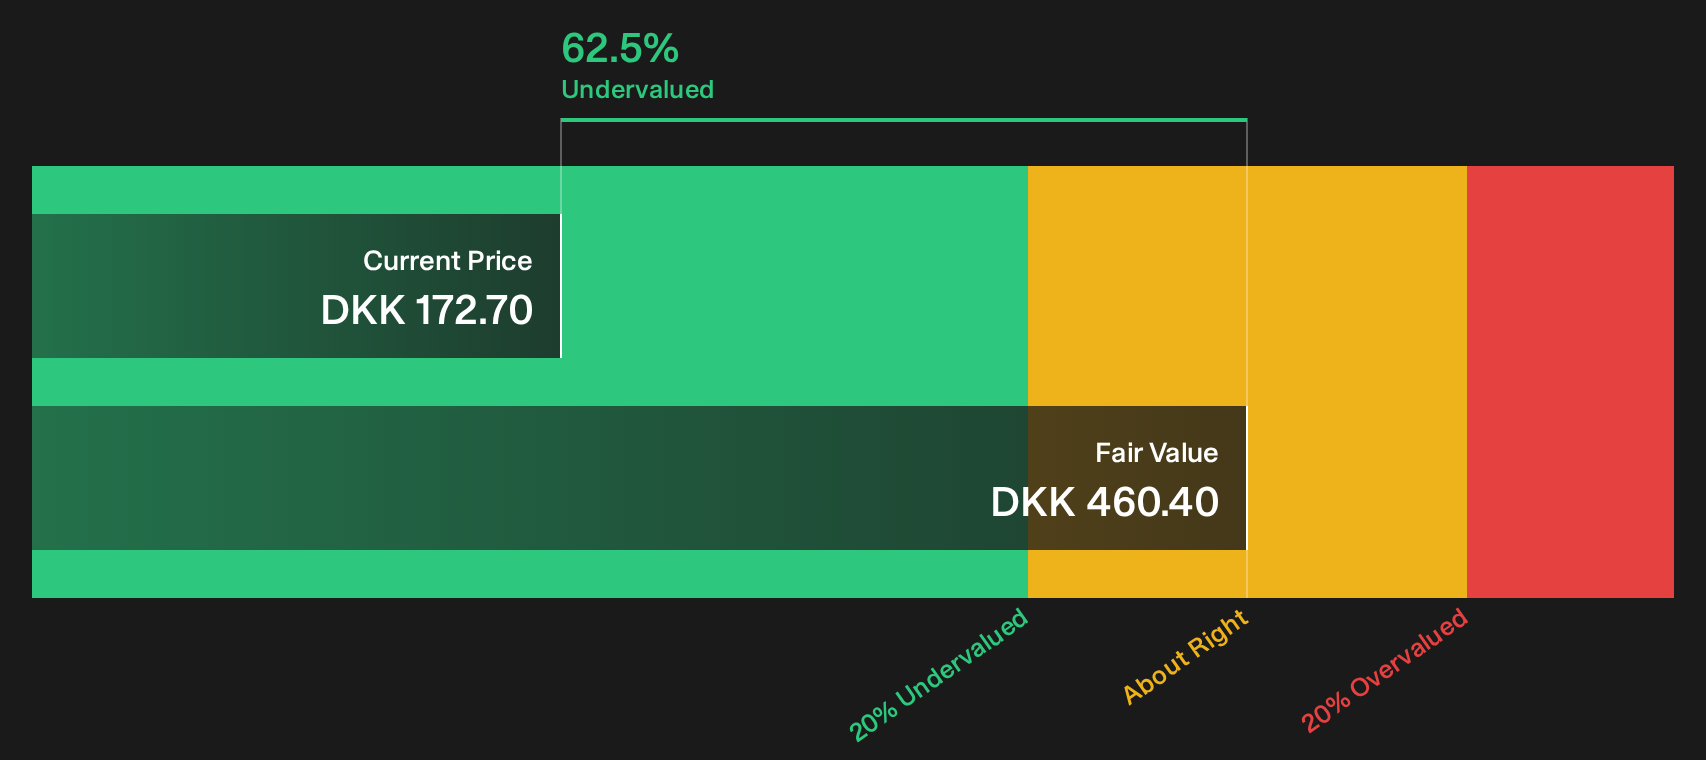
The analyst narrative pegs DFDS at around DKK163.5 and describes the stock as roughly 6% overvalued at DKK172.7. A different lens tells a very different story. Our DCF model, based on estimated future cash flows, implies a value closer to DKK460.4, which suggests significant undervaluation. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on DFDS valuation and risk can easily pull you in opposite directions, so move quickly, review the underlying data, then weigh the 3 key rewards and 2 important warning signs.
Looking for more DFDS sized ideas?
If DFDS has you rethinking what belongs in your portfolio, do not stop here. Use focused stock lists to spot opportunities you might otherwise miss.
- Target resilient compounding potential by scanning a carefully filtered pool of quality opportunities through the 174 high quality undervalued stocks.
- Prioritise staying power and sleep better at night by sifting through the 229 resilient stocks with low risk scores built around resilience and lower risk scores.
- Get ahead of the crowd by reviewing the 615 high quality undiscovered gems that combine strong business fundamentals with less widely followed tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com