


WuXi XDC Cayman (SEHK:2268) Climbed, What Is Behind The Fresh Attention?
WuXi XDC Cayman (SEHK:2268) is back in focus after announcing an exclusive global out licensing deal with Ona Therapeutics for its WuXiTecan-2 payload linker technology platform.
The licensing update comes on top of a strong run in WuXi XDC Cayman’s stock. The latest share price is HK$80.7 after a 1-day share price return of 4.81% and a 90-day share price return of 65.17%. This performance far outpaces its 1-year total shareholder return of 5.84%, suggesting that momentum has picked up sharply in recent months as investors reassess both growth potential and risk around its ADC platform deals.
Scan beyond WuXi XDC Cayman and see how other ADC and biotech specialists are pricing in similar deal momentum with our curated list of 613 high quality undiscovered gems.
After a 65% move in 90 days and WuXi XDC Cayman still trading below both analyst targets and intrinsic estimates, the real tension is simple: Is the fresh deal flow already in the price or not yet fully reflected?
Most Popular Narrative: 12% Undervalued
The most followed valuation narrative pegs WuXi XDC Cayman's fair value at HK$92.10, above the latest HK$80.70 close, which puts recent deal headlines into sharper context.
The growing use of antibody drug conjugates and newer bioconjugates such as AOCs and APCs is contributing to a larger addressable project funnel at WuXi XDC Cayman. This can support sustained revenue growth as more assets move from discovery to development and commercial manufacturing.
See why 1 investors see WuXi XDC Cayman as 12% undervalued.
Result: Fair Value of HK$92.10 (UNDERVALUED)
Still, the bullish WuXi XDC Cayman story leans heavily on ADC demand holding up and on new capacity in China and Singapore avoiding long spells of underuse.
Find out about the key risks to this WuXi XDC Cayman narrative.
Another View on WuXi XDC Cayman's Valuation
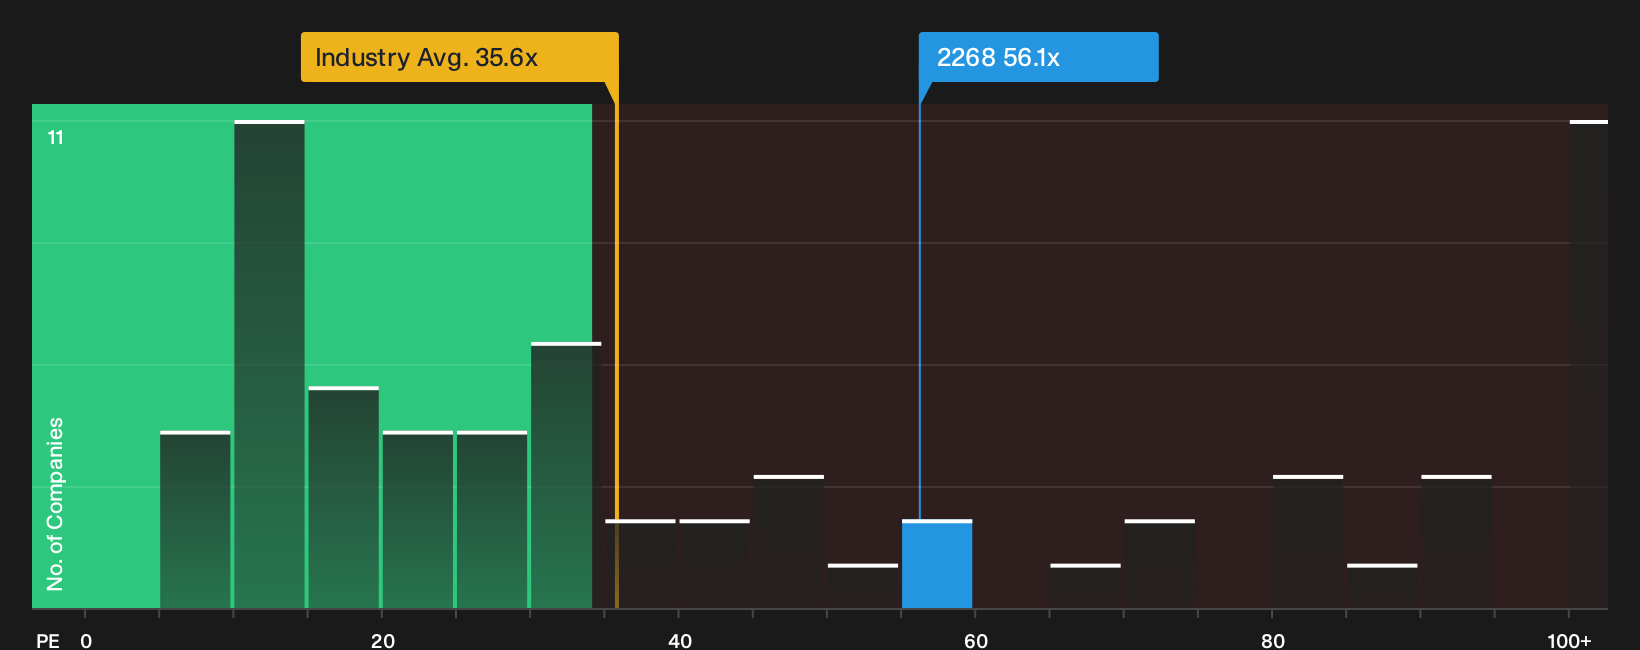
There is a different story if you look at WuXi XDC Cayman through its P/E. The stock trades on 56.1x earnings, while the Asian Life Sciences group averages 35.6x and direct peers sit near 23.2x. The fair ratio is 31x. That is a wide gap. How comfortable are you paying that kind of premium for this growth profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on WuXi XDC Cayman so far. If you want to move quickly and decide where you land, start by weighing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond WuXi XDC Cayman?
Do not stop at WuXi XDC Cayman. Use the screener to spot fresh opportunities, compare different edges, and pressure test your conviction before committing more capital.
- Target potential mispricing by scanning a curated pool of quality businesses trading below what the market currently implies through the 183 high quality undervalued stocks.
- Prioritize resilience by focusing on companies with stronger financial footing and cleaner balance sheets using the list of solid balance sheet and fundamentals (199 results).
- Hunt for overlooked opportunities with healthier fundamentals that fewer investors are watching right now through the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com