


Is Liberty Energy (LBRT) Undervalued Following Its 30% Share Price Reset?
Liberty Energy (LBRT) has delivered a multi year total return near 80%, yet the recent share price pullback now puts sharper focus on whether current earnings fully underpin that valuation.
Over the past year Liberty Energy’s share price has swung from strong momentum to a sharp reset, with the stock down about 31% over the last 90 days even as the 1 year total shareholder return of roughly 79% keeps longer term holders well ahead.
Scan beyond Liberty Energy’s recent pullback and benchmark it against hand picked 35 high quality undervalued stocks that may offer a similar valuation story backed by earnings strength.
Liberty Energy has just dropped more than 30% in three months, while multi year holders still sit on strong gains. Does it make more sense to lean into this reset now, or wait for the valuation to work harder first?
Most Popular Narrative: 33% Undervalued
Liberty Energy closes at $19.33 against a widely followed fair value estimate near $29.04, so the key question is whether its long term power ambitions can justify that gap in investor expectations.
Strategic alliances and scale investments (for example, the Oklo partnership for advanced nuclear solutions, and microgrid and distributed power projects) position Liberty to pursue higher value, long duration contracts from large scale customers such as data centers. This expands Liberty's addressable market and may support future top line and margin growth.
See why 8 investors see Liberty Energy as 33% undervalued.
Result: Fair Value of $29.04 (UNDERVALUED)
Still, softer completions activity and heavier spending on Liberty Power Innovations could pressure cash generation and keep investors questioning the current Liberty Energy narrative.
Find out about the key risks to this Liberty Energy narrative.
Another View: Liberty Energy On Earnings Multiples
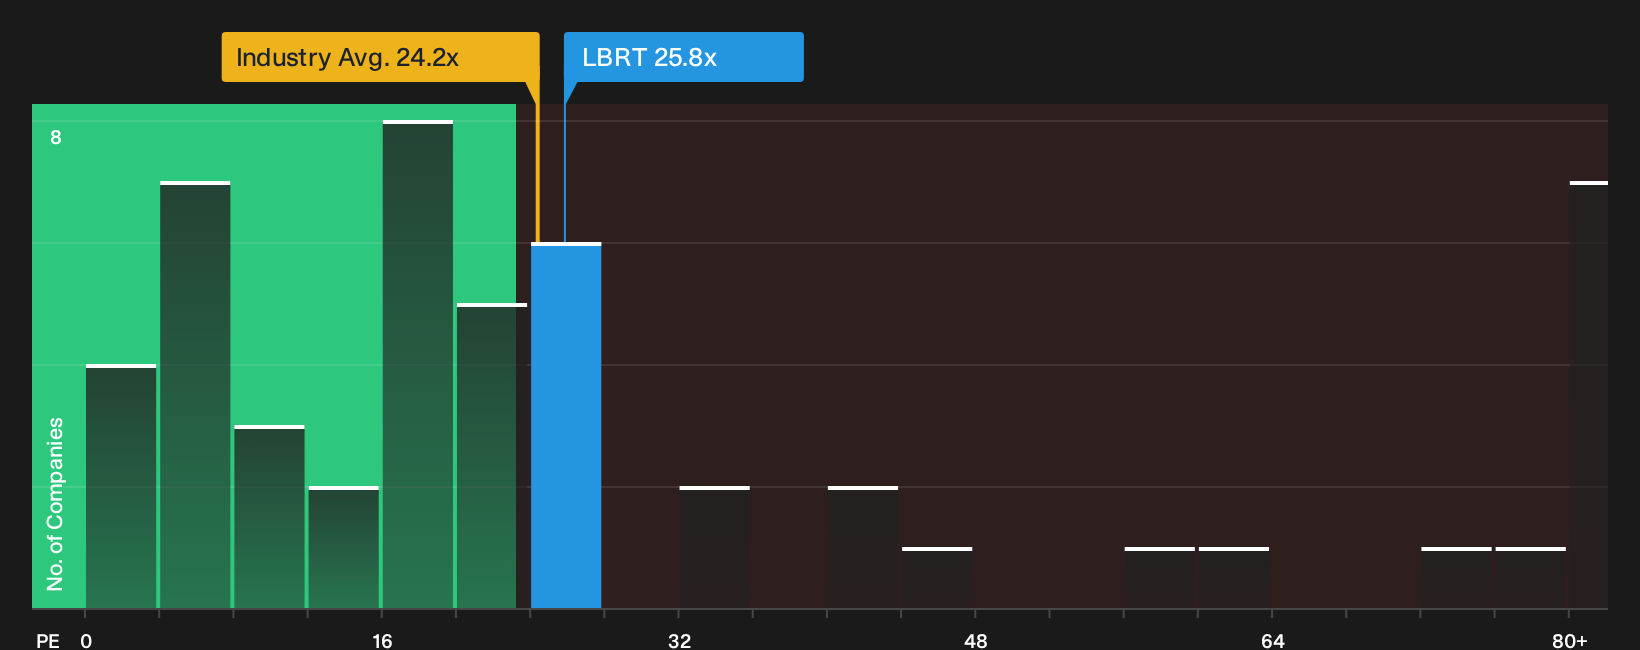
The first narrative presents Liberty Energy as undervalued based on fair value estimates. However, its P/E of 25.8x is higher than both the US Energy Services industry average of 24.2x and an estimated fair ratio of 11.4x. This gap suggests the market already prices in a significant amount of future execution risk. The key question is whether earnings can grow into that multiple or whether the ratio will move closer to the fair ratio instead.
For a closer look at how current pricing compares with earnings, sector peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Liberty Energy can feel messy, so move quickly, study the data for yourself, and weigh both the upside and the problems through 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Liberty Energy?
If Liberty Energy has sharpened your focus on value and risk, do not stop here. Broaden your watchlist now so you are not chasing the next move late.
- Target resilient wealth compounding by focusing on dependable balance sheets through a list of solid balance sheet and fundamentals (23 results) that filters for financial strength and funding flexibility.
- Hunt for mispriced quality and sharpen your opportunity set with a 16 high quality undiscovered gems that highlights lesser known companies with solid fundamentals.
- Prioritize sleep at night investing and lean on a 30 resilient stocks with low risk scores that spotlights businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com