


Distribution Deal Might Change The Case For Investing In Littelfuse Stock (LFUS)
- Flip Electronics previously announced an authorized distribution partnership with Littelfuse covering end-of-life, obsolete, aged, and excess devices for industrial, military, aerospace, transportation, and medical customers.
- The agreement gives Littelfuse a way to monetize legacy inventory and reach niche, high-reliability programs that often rely on older components.
- This broader channel access for Littelfuse’s legacy devices could influence the longer term investment narrative.
Littelfuse Investment Narrative Recap
To own Littelfuse, you need to believe in long-cycle demand for electrification across autos, industrial equipment, data centers, and grid infrastructure, and in the company’s ability to turn that into durable earnings after a period of losses. In the near term, the key swing factor is execution in power semiconductors and electronics margins, where softness and compensation impacts are already weighing on profitability.
On the risk side, exposure to cyclical automotive and industrial end markets, along with competitive pressure from lower cost Asian manufacturers, keeps revenue and margin volatility on the table. The newest announcements do not appear to change those core drivers or near-term catalysts in a material way.
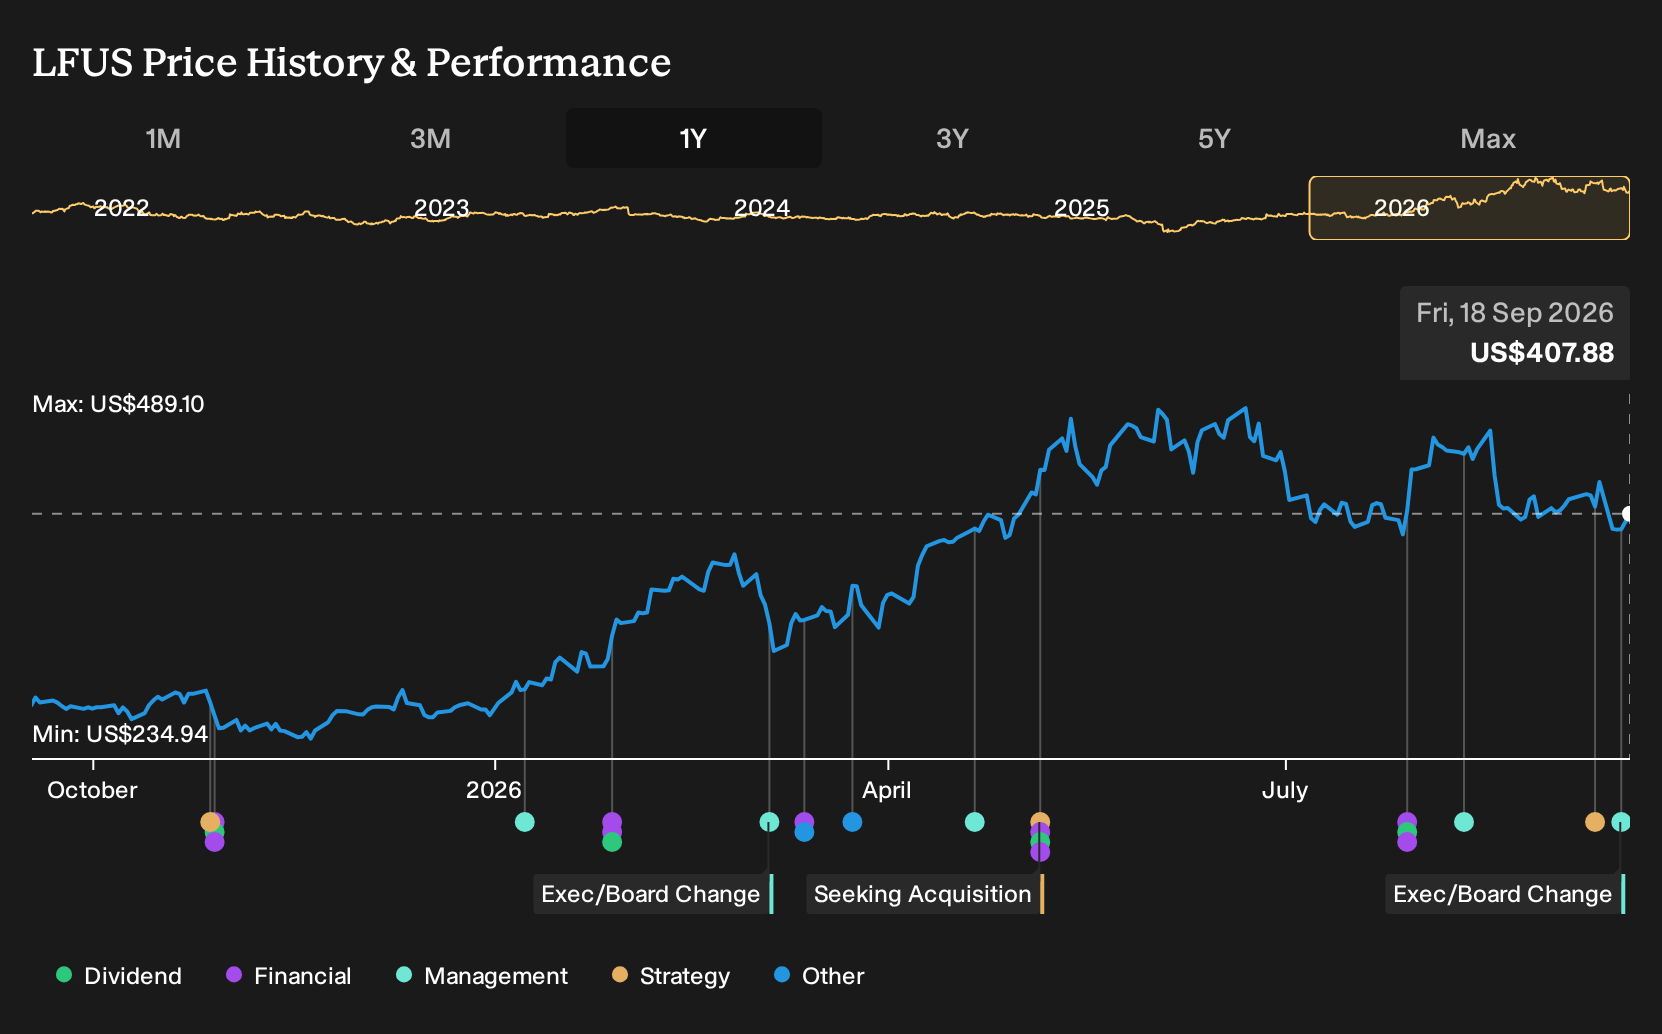
The leadership transition announced for 2027, with Deepak Nayar retiring and Dr. Karim Hamed taking on an expanded Senior Vice President and General Manager role, matters most for how Littelfuse runs its semiconductor and electronics operations. Hamed brings more than two decades of experience in chips, including senior roles at Analog Devices and other specialized RF and microwave players.
For investors, the key consideration is whether this planned handover supports the existing catalyst path, which is centered on electrification demand, operational excellence, and a solutions-focused model that targets data centers, grid projects, and transportation. Any disruption in execution, integration of acquisitions, or product roadmap alignment during the transition would compound existing risks around power semiconductor performance and margin recovery.
Littelfuse's narrative projects US$3.8b revenue and US$619.9m earnings by 2029. Analysts are assuming 13.2% yearly revenue growth and an earnings increase of about US$628m from current earnings, which are a US$8.1m loss.
Uncover why Littelfuse's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Littelfuse acquisition risk. Bullish analysts were already penciling in about US$3.6b revenue and US$603.5m earnings by 2029, assuming smooth deal making and integration. If you think the Flip partnership and leadership changes shift that story, you may want to compare several competing narratives before deciding.
Explore another Littelfuse fair value estimate, including one that suggests a potential upside of up to 38% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Littelfuse research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Littelfuse. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Littelfuse's overall financial health at a glance.
Looking For More Investment Ideas Beyond Littelfuse?
If the Littelfuse story has you thinking about where else long-cycle demand and resilient business models might show up, it can help to widen your search with a structured stock filter rather than jumping from ticker to ticker on headlines alone.
- For investors who want quality and value to line up, a good starting point is a curated set of companies trading on compelling fundamentals, screened from a universe of 35 high quality undervalued stocks.
- If capital preservation and steadier return profiles matter most to you, consider focusing on businesses that pair stronger balance sheets with lower overall risk, drawn from our 30 resilient stocks with low risk scores.
- When you are hunting for tomorrow's potential leaders before they hit the mainstream, it can be useful to scan a focused pool of lesser-known yet fundamentally solid opportunities from the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com