


Sienna Senior Living (TSX:SIA) Has A Fresh Update, What Is Drawing Attention?
Sienna Senior Living (TSX:SIA) is moving to acquire Stonemont On the Park, a 305-suite Ottawa retirement residence that opened in 2024 and is currently about 99% occupied.
For context, Sienna Senior Living’s share price is CA$20.31, with a 1-day share price return of 0.99% and a 7-day share price return of 2.52%. The 30 and 90 day share price returns have moved lower, yet the 1 year total shareholder return of 16.64% and very large 3 year and 5 year total shareholder returns indicate that longer term momentum has been strong, even as investors weigh new deals and ongoing capital commitments such as the Stonemont acquisition.
Scan how Sienna Senior Living stacks up against other income focused operators by reviewing our hand picked list of 1 dividend fortresses.
Sienna Senior Living is adding a fully leased Ottawa asset after a strong multi year run. Is the bigger opportunity now in fresh upside, or was most of the easy value already captured on the way here?
Preferred P/E of 43.2x for Sienna Senior Living: Is it justified?
On simple valuation checks, Sienna Senior Living looks expensive when set against its healthcare peers. The stock trades on a P/E of 43.2x, while the broader North American healthcare group sits closer to the mid 20s, even though Sienna is also flagged as trading well below an internal fair value estimate based on future cash flows.
P/E focuses on what investors are willing to pay today for each dollar of earnings. For a senior living operator with CA$1.08b in revenue and CA$52.08m in net income, a 43.2x multiple implies the market is attaching a relatively rich price to current profitability compared with many other healthcare stocks.
The tension is clear. On one side, Sienna Senior Living screens as expensive relative to both the North American healthcare industry average P/E of 24.4x and a closer peer set at 24.6x. On the other, the SWS DCF model suggests the shares trade at about a 49.9% discount to an estimated future cash flow value of CA$40.53 per share, and analysts as a group see scope for a 31.5% uplift from the current CA$20.31 level according to their price target.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 43.2x (OVERVALUED)
Still, the story can change quickly if Sienna Senior Living faces weaker occupancy in new projects or higher funding costs that reduce returns from fresh deals.
Find out about the key risks to this Sienna Senior Living narrative.
Another View on Sienna Senior Living's Value
The SWS DCF model presents a very different picture for Sienna Senior Living. At CA$20.31, the shares are flagged as trading about 49.9% below an estimated future cash flow value of CA$40.53 per share, which suggests undervaluation rather than an expensive P/E story. Which signal do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
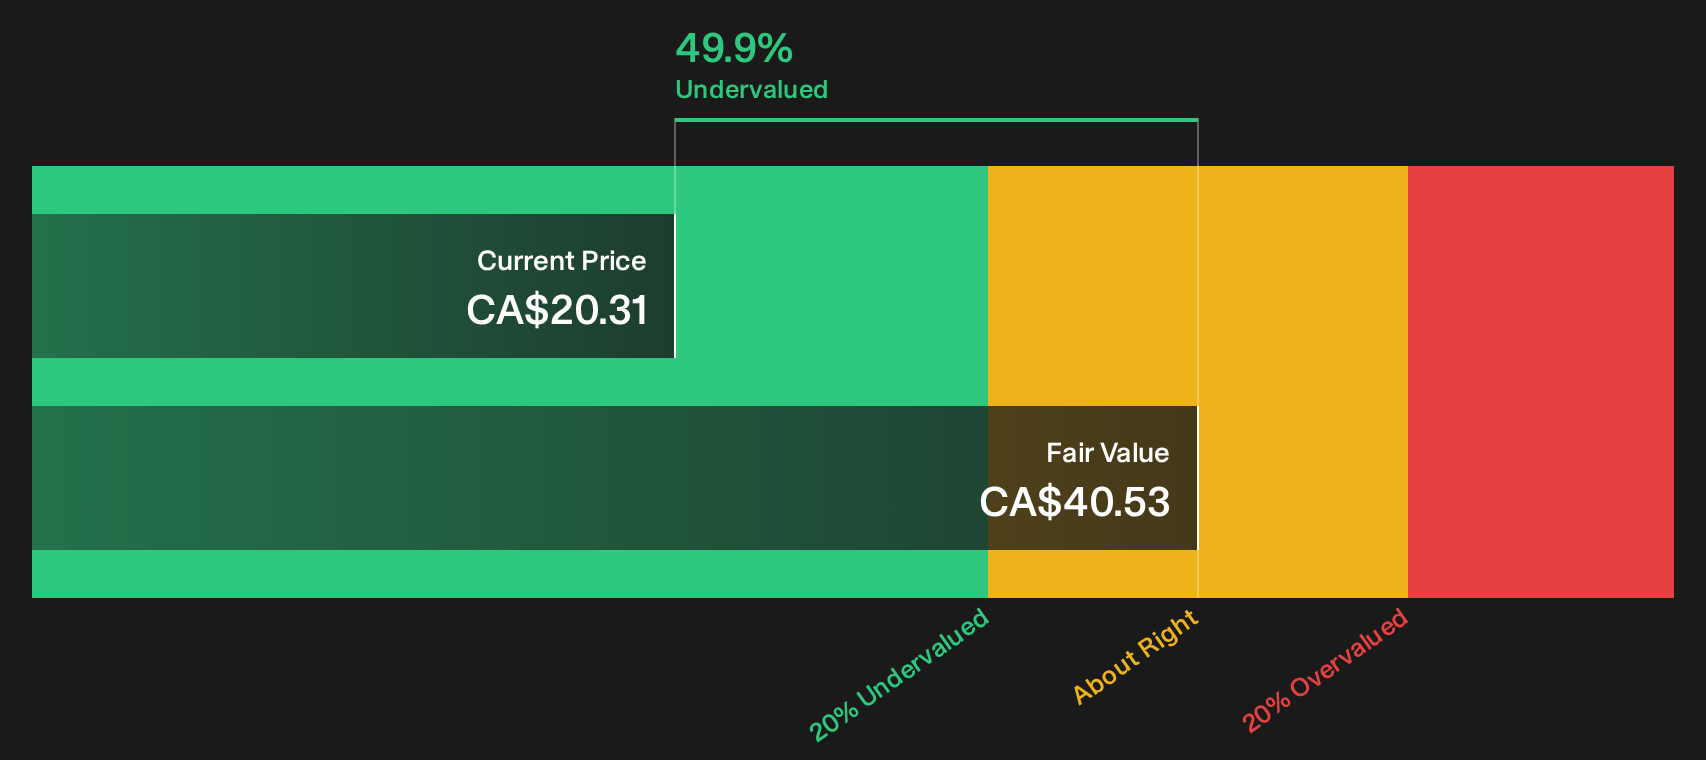
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sienna Senior Living for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sienna Senior Living can be confusing, so consider reviewing the latest data and test the story yourself by weighing its 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Sienna Senior Living?
If Sienna Senior Living is only one piece of your watchlist, broadening your opportunity set with fresh ideas can help you spot gaps others miss.
- Explore potentially resilient businesses by reviewing a curated mix of steadier companies through our 8 resilient stocks with low risk scores.
- Search for value candidates that pair quality fundamentals with appealing pricing using the 4 high quality undervalued stocks.
- Strengthen your watchlist with companies that have healthier finances and cleaner leverage profiles using the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com