


Growth Plan Might Change The Case For Investing In NovoCure Stock (NVCR)
- NovoCure reported that long serving director Timothy Scannell retired from the Board on 2 September 2026, with the company stating his departure after five years did not stem from any dispute with management.
- Management also laid out a refreshed operating roadmap that concentrates on rekindling glioblastoma device demand, broadening pancreatic and lung cancer launches, and working toward adjusted EBITDA break-even by year-end.
- We will look at how NovoCure's investment narrative is reshaped by this renewed push toward adjusted EBITDA break-even and wider cancer indications.
Scan for other cancer care stocks that are pushing toward profitability targets with disciplined expansion plans by reviewing our curated list of list of solid balance sheet and fundamentals (23 results)
NovoCure Investment Narrative Recap
For NovoCure, the big picture you need to buy into is that Tumor Treating Fields can gain broader traction across glioblastoma, lung cancer and pancreatic cancer, while the company tightens costs enough to move closer to adjusted EBITDA break even. In the near term, the main swing factor remains execution on that operating roadmap rather than board composition.
The biggest operational risk still sits with uptake and reimbursement for new indications, and with the business continuing to report net losses. Timothy Scannell’s retirement appears to have limited impact on those near term catalysts, unless future board changes start to dilute the current level of independence or oncology experience.
The most relevant update in this context is NovoCure’s aim to reach adjusted EBITDA break even by year end while pushing into pancreatic and lung cancer. That goal places significant emphasis on prescription trends, pricing, and spending discipline across R&D and SG&A, given the company still reports a loss of US$148.6 million.
For you as a shareholder, the question is whether management can convert its single technology focus into broader, reimbursed usage quickly enough to close that earnings gap. Execution on launches in Europe and Japan, along with any regulatory decisions in pancreatic cancer, sits alongside the EBITDA target as a key operational catalyst and test of the plan.
NovoCure's narrative projects US$915.6 million in revenue and US$119.8 million in earnings by 2029. This projection assumes 11.8% yearly revenue growth and an earnings increase of about US$256 million from a loss of US$136.2 million today.
Uncover why NovoCure's fair value indicates a 56% potential upside to its current price, which could narrow quickly.
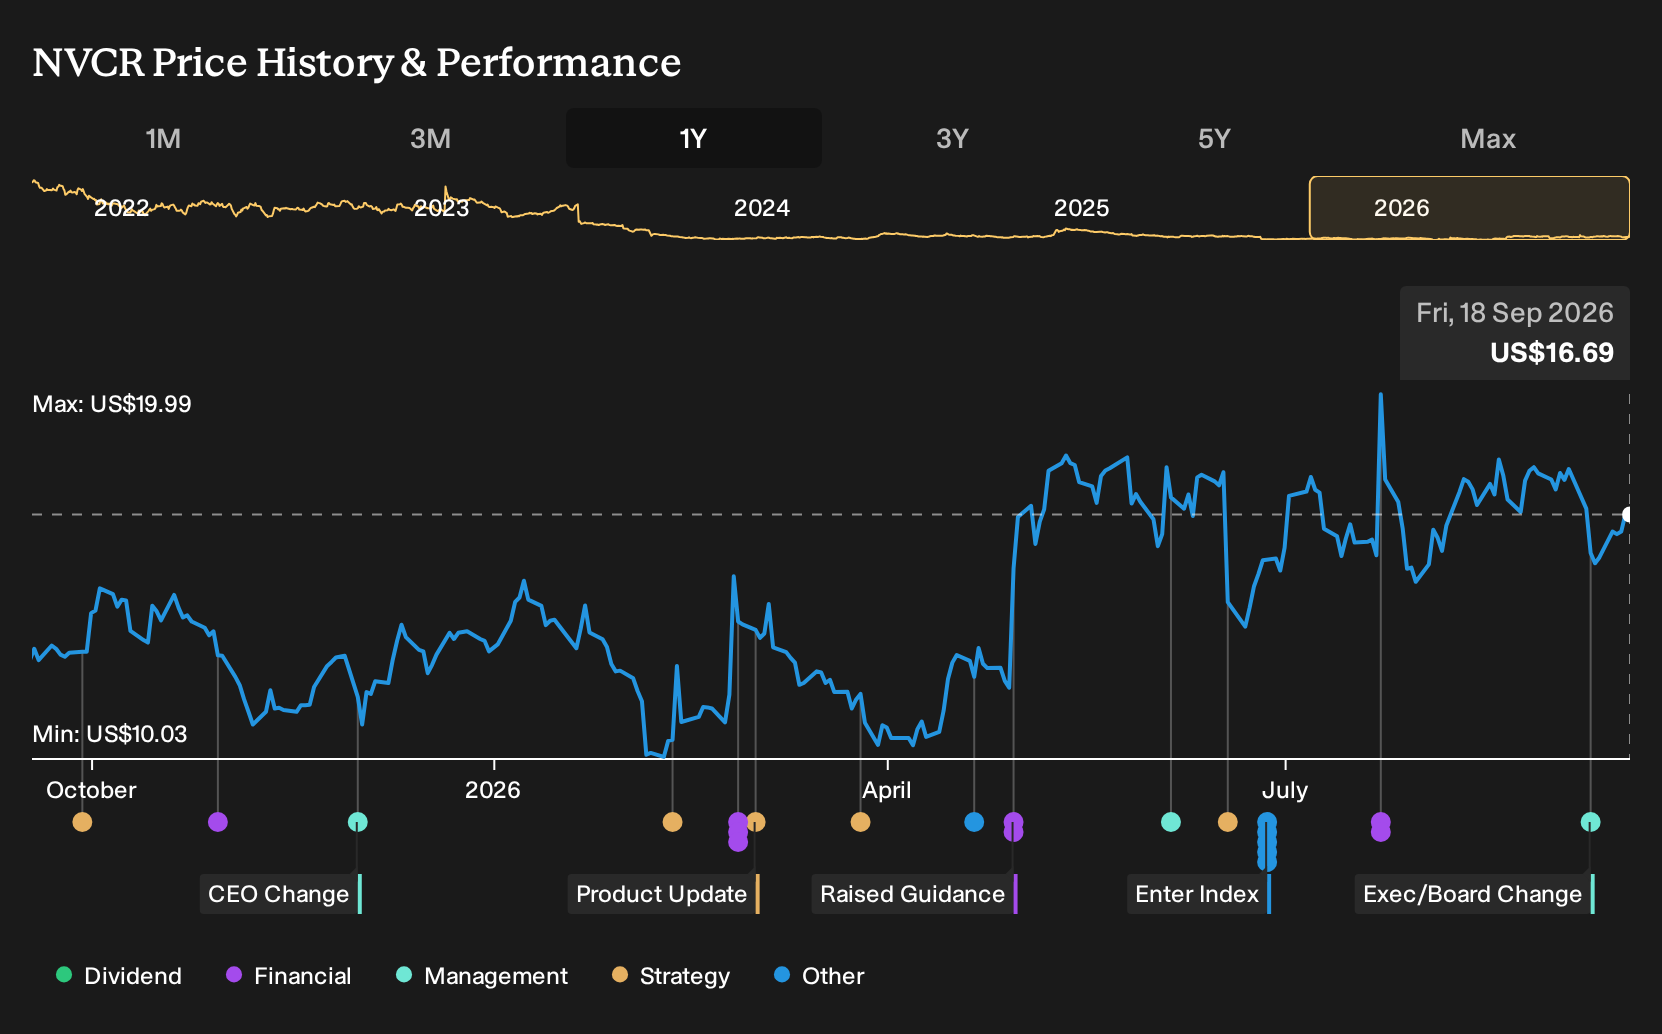
Exploring Other Perspectives
The lowest analysts focus on NovoCure’s single technology risk rather than the EBITDA target. They were already pencilling in slower progress, with revenue rising at 10.3% a year and earnings moving from a loss of US$173.0 million to US$110.2 million by 2029. Board changes and the refreshed roadmap may lead those views to evolve.
Explore 3 other NovoCure fair value estimates, including one that suggests it could be worth just $26.07!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NovoCure research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NovoCure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NovoCure's overall financial health at a glance.
Looking For More Investment Ideas Beyond NovoCure?
Once you have a view on NovoCure, it can help to cross check that thesis against other opportunities that match your risk tolerance and income goals. A targeted screener can quickly surface candidates that fit the kind of balance sheet strength, valuation profile, or resilience you want in your portfolio.
- If capital preservation matters most and you want businesses with room to absorb shocks, start by reviewing a 30 resilient stocks with low risk scores that have historically held up better on key stability checks.
- When the focus is on quality at a reasonable price, scan a 35 high quality undervalued stocks that combine solid fundamentals with attractive valuation markers.
- If you prefer companies that can better withstand funding stress and invest through cycles, consider a curated list of solid balance sheet and fundamentals (23 results) that already meet strict balance sheet and fundamentals criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com