


Charter Communications (CHTR) Stock Looks Undervalued Despite Its Spectrum Expansion News
Charter Communications has seen its share price fall sharply in recent years, which puts the focus squarely on whether the current valuation still lines up with the earnings power of the business. With the stock under pressure, the key issue for you is how much of the company’s profit story is already reflected in today’s US$128.17 price.
- The share price has declined 82.7% over the past 5 years, which raises real questions about how the market currently rates Charter Communications’ earnings profile.
- Spectrum’s move to welcome more than 11 million former Cox customers into its footprint may support future revenue and profit scale, which matters directly for how sustainable the company’s earnings base looks.
- The analysts covering Charter Communications have run their own numbers. See what analysts think Charter Communications's shares could be worth.
The issue now is whether Charter Communications’ current share price is appropriately aligned with the earnings it is generating today.
If you want to explore the same earnings question you are considering for Charter Communications with other stocks, it is worth scanning 33 high quality undervalued stocks
Is Charter Communications a Bargain on Earnings?
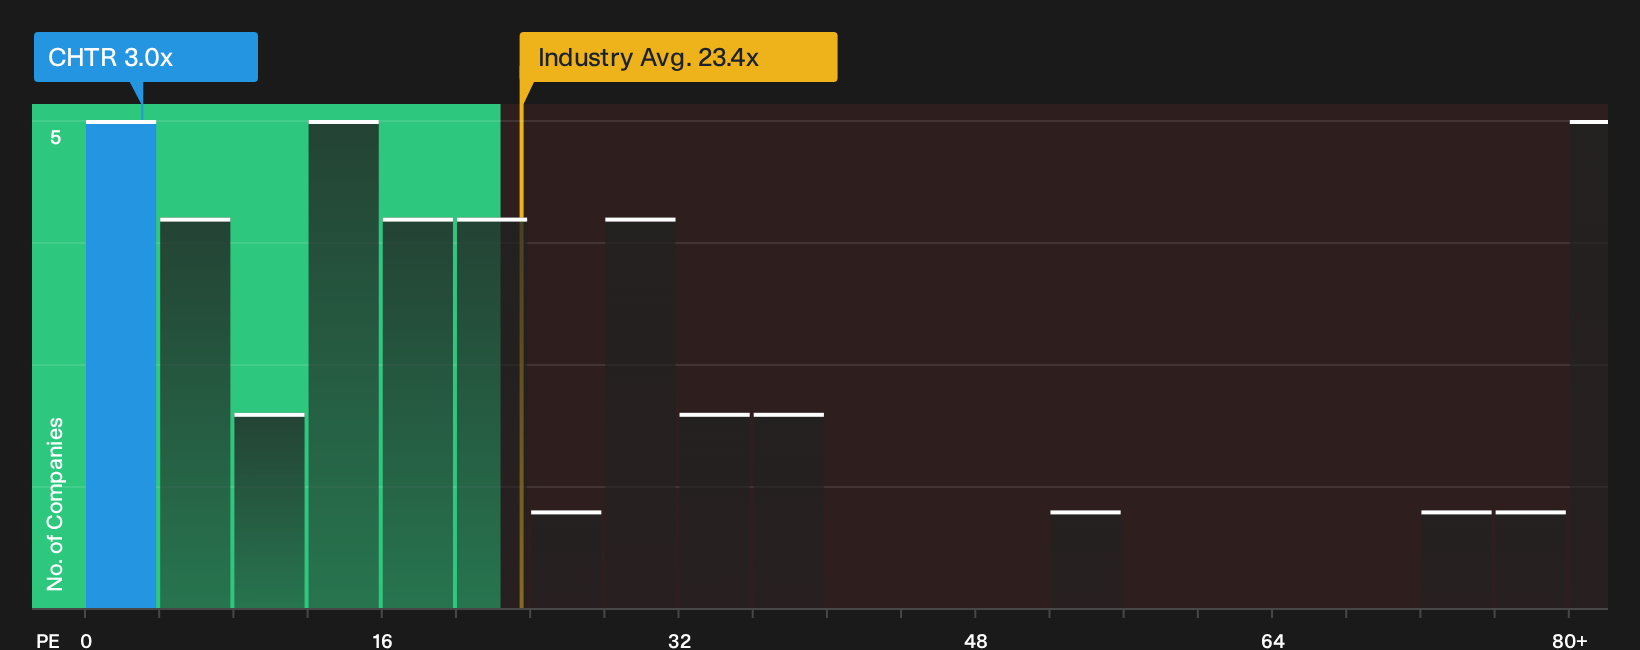
The P/E ratio fits Charter Communications because investors focus heavily on how efficiently it converts its large customer base into earnings. On that score, the stock changes hands at about 3.0x earnings, which is a fraction of the Media sector average near 23.4x and well below the peer group around 15.3x.
Because the latest P/E sits meaningfully under the level suggested by a tailored fair multiple for the business, the shares screen undervalued on this yardstick. The gap is wide enough that even with Spectrum integrating more than 11 million former Cox customers into its footprint, the current earnings multiple still prices Charter Communications at a steep discount to what many comparable media companies command. Explore the numbers behind Charter Communications's P/E valuation.
The Charter Communications Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Charter Communications pick up where the P/E puzzle leaves off. They spell out what kind of future growth, margins and earnings trajectory would need to occur for the stock to be worth materially more or less than today’s price. Each scenario lays out its own set of assumptions about Charter Communications' fair value so you can later compare those expectations with the actual results as they come through on the Community page.
Bulls and bears on Charter Communications are working off the same cash flow story but land on very different readings of the risk.
Bull case: 57% undervalued
"CHTR is nearing the end of a large multi-year network upgrade. Capex, which has been coming in at roughly 11.5B for three years, will decline…"
Discover why this Narrative puts Charter Communications at 57% undervalued.
Bear case: 27% overvalued
"Charter Communications faces persistent broadband subscriber losses amid heightened competition from 5G and fixed wireless access providers, threatening the company's ability to return to meaningful broadband customer growth…"
Explore why this Narrative puts Charter Communications at 27% overvalued.
One more Charter Communications check that belongs next to the P/E story
Price tells you what the market thinks of Charter Communications today, while the projected path for revenue and profit a few years out tells you what the analyst community is building into their models. Explore where analysts expect Charter Communications to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com