


Will RNAi Market Growth Change Alnylam Stock's Narrative?
- Recent market research points to significant projected expansion in global RNA interference therapeutics, with Alnylam Pharmaceuticals identified as a leading participant in RNA-based treatments for hard-to-treat conditions, including hereditary transthyretin-mediated amyloidosis.
- The emphasis on rare disease prevalence and precision medicine investment highlights how Alnylam Pharmaceuticals's focus on hATTR and RNAi platforms ties directly into an expanding treatment universe and potential demand for specialized therapies.
- We will now see how this stronger RNA interference market outlook could influence Alnylam Pharmaceuticals's investment narrative for long term oriented investors.
Alnylam Pharmaceuticals Investment Narrative Recap
To own Alnylam Pharmaceuticals, you need to believe RNAi therapies can support a broad rare disease portfolio and that the ATTR franchise can fund that expansion. The RNA interference market tailwind highlighted in the recent research mostly reinforces the existing thesis rather than changing it. The near term swing factor still looks like execution on AMVUTTRA and broader ATTR adoption trends.
The biggest operational risk remains concentration in that TTR franchise, combined with pricing pressure and gross margin drag from royalties and payer dynamics. High R&D and SG&A spending keeps the bar high for every new program to justify itself. The new RNAi market optimism does not remove those cost and payer pressures.
With no fresh company specific announcements tied directly to this RNAi market report, the most relevant reference point is still Alnylam Pharmaceuticals' push on AMVUTTRA and late stage ATTR programs such as nucresiran. The growth focus is squarely on turning a strong ATTR position into a durable, multi indication platform.
For you as an investor, the question is execution speed and consistency. Broader RNAi enthusiasm only matters if AMVUTTRA uptake, international expansion and future ATTR launches support the heavy spend on development and commercialization while offsetting risks from pricing, margins and payer policy shifts.
Alnylam Pharmaceuticals' current analyst narrative points to US$8.8b in revenue and US$1.8b in earnings by 2029, based on an assumed 22.2% yearly increase in sales. That earnings figure would represent an increase of about US$1.0b from earnings today of US$774.7m.
Discover why Alnylam Pharmaceuticals' fair value indicates a 55% potential upside to its current price. This suggests a discount that could narrow faster than investors expect.
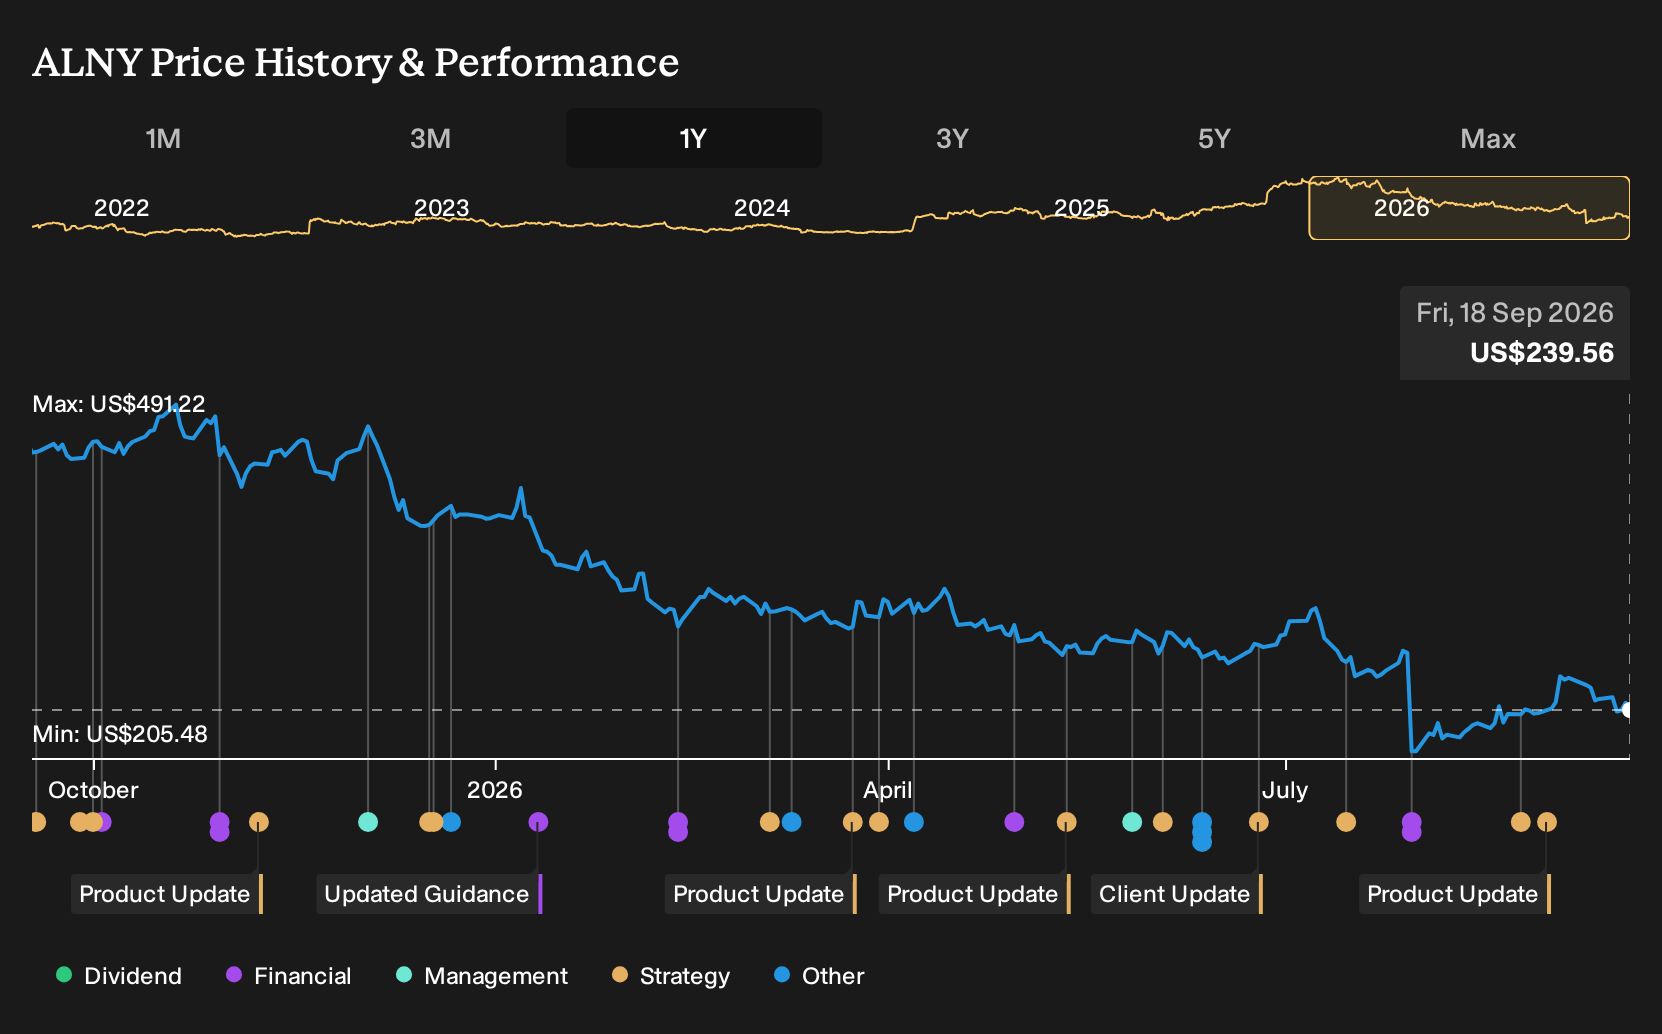
Exploring Other Perspectives
One alternate view leans hard into pricing risk. On that score, the most cautious analysts were only penciling in about US$7.3b of 2029 revenue and roughly US$1.3b of earnings for Alnylam Pharmaceuticals before this RNAi market news. That is far more pessimistic than the consensus and shows how much opinions can diverge, so it is worth exploring several angles before deciding how this new information might reshape expectations.
Explore 4 other Alnylam Pharmaceuticals fair value estimates, including one that suggests it could be worth just $230.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alnylam Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Alnylam Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alnylam Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Alnylam Pharmaceuticals?
If you want to stress test your Alnylam Pharmaceuticals thesis or simply widen your opportunity set, the Simply Wall St Screener can help you line up peers and alternatives that match your own risk and return preferences.
- If capital protection is front of mind, filter for companies with sturdier profiles by running a 30 resilient stocks with low risk scores and compare how their risk scores stack up against what you see in Alnylam Pharmaceuticals.
- When you care most about quality at a reasonable entry point, use the screener to focus on businesses trading below their assessed worth through the 33 high quality undervalued stocks and see which ones fit your checklist.
- If you are hunting for potential future leaders that are not yet widely followed, cast a wider net with the 16 high quality undiscovered gems and see which under the radar ideas merit a deeper look next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com