


Karman Holdings (KRMN) Could Be 66% Undervalued As Backlog Story Holds
Karman Holdings (KRMN) has drawn fresh attention after recent trading left the share price at US$35.75. Short term moves look modest; however, the past month and past 3 months show sharper declines.
Over the past year, momentum in Karman Holdings has faded, with the share price return down 53.48% year to date and the 1-year total shareholder return down 45.93%. The sharp 30-day share price decline of 38.57% points to a recent reset in growth expectations or perceived risk.
Pressure test Karman Holdings against peers by scanning a hand picked group of list of solid balance sheet and fundamentals (23 results) to see how other contractors with sturdier financial foundations have held up under recent volatility.
The recent slide in Karman Holdings puts the current US$35.75 level front and centre. Is that a reasonable entry now, or does it make more sense to wait for a cheaper valuation?
Most Popular Narrative: 66% Undervalued
Karman Holdings is trading at $35.75, while the most followed valuation storyline on Simply Wall St anchors fair value much higher at $105.60. That gap frames a very different picture to the recent share price slide.
The backlog exceeding $1 billion, up 61% year-over-year, is the single most important data point in this story. It represents 1.4x forward annual revenue and provides exceptional near-term visibility.
See why 45 investors see Karman Holdings as 66% undervalued.
Result: Fair Value of $105.60 (UNDERVALUED)
Still, Karman Holdings faces real pressure points, with its sizeable debt load and customer concentration both capable of quickly reversing this undervaluation story.
Find out about the key risks to this Karman Holdings narrative.
Another View on Karman Holdings Valuation
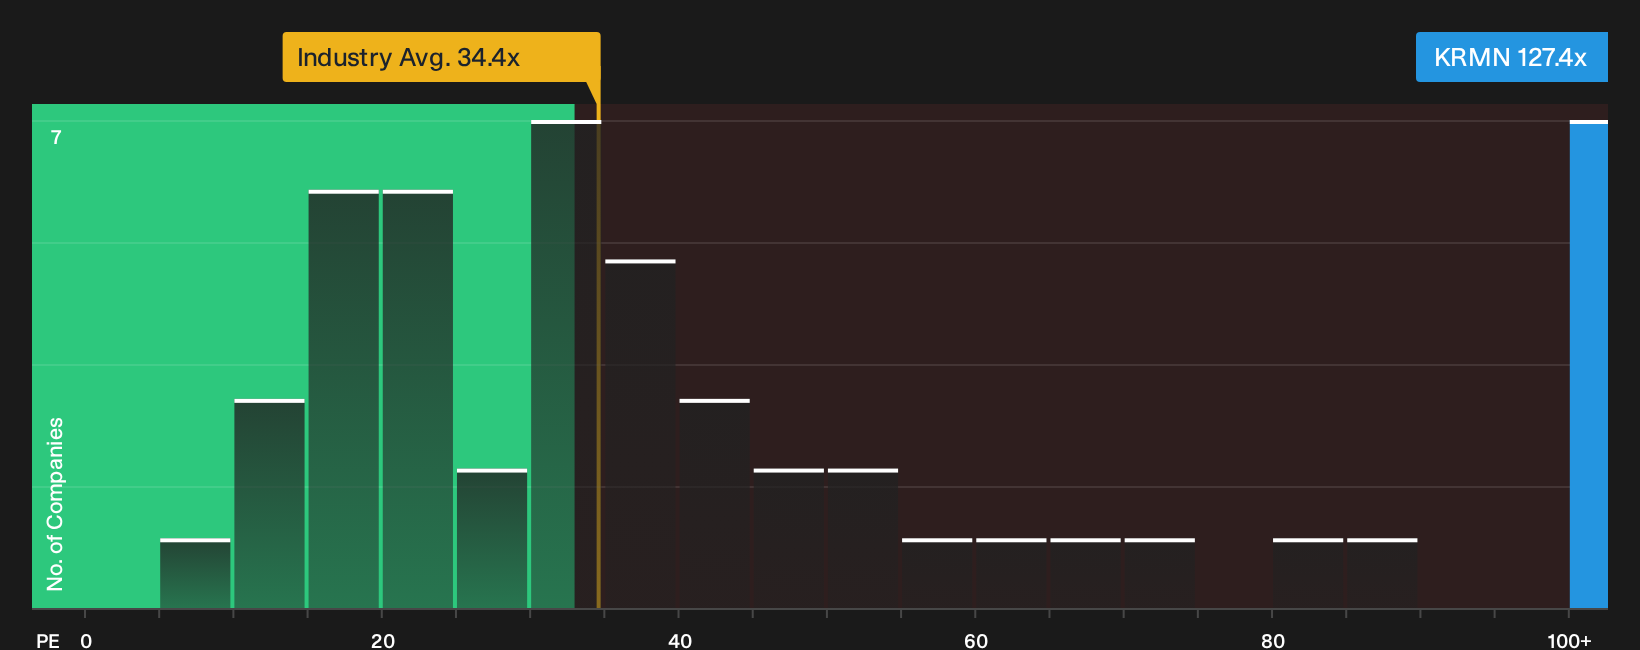
The fair value narrative around Karman Holdings leans heavily on a US$105.60 figure, yet its current P/E of 127.4x tells a very different story. The wider US Aerospace & Defense sector trades at 34.4x and peers average 53.5x, while the fair ratio sits at 75.9x. That gap suggests investors are paying a steep premium, so is the crowd leaning too far ahead of the fundamentals?
Before leaning on that premium as a comfort blanket, it is worth stress testing what the earnings multiples imply about downside risk versus upside potential for Karman, especially if sentiment cools off or growth assumptions are revised. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This mix of sharp price pressure and an optimistic fair value story makes Karman Holdings a polarised situation. Move quickly to test the data, weigh both sides, and anchor your own stance using 2 key rewards and 1 important warning sign.
Looking for more Karman Holdings style investment ideas?
Do not stop your research with Karman Holdings alone. Use the Simply Wall St screener to surface fresh ideas that fit the way you like to invest.
- Target steady compounding by reviewing a curated 6 dividend fortresses that focuses on income first without ignoring balance sheet strength.
- Zero in on potential bargains by scanning a 33 high quality undervalued stocks that blends quality fundamentals with prices that sit below intrinsic value estimates.
- Protect your downside by filtering for a 30 resilient stocks with low risk scores so you can focus on businesses where measured risk scores stay front of mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com