


3 Oil And Gas Stocks For Higher Crude Prices
Oil routes around Saudi Arabia are back in the spotlight as Houthi attacks, pipeline closures and rising shipping risk around Bab al-Mandeb push crude prices higher and rattle inflation expectations. That kind of shock can punish some sectors while lifting others, so sitting on the sidelines can feel costly. This article breaks down 3 stocks exposed to this news and explains how their Middle East footprint could matter for your portfolio now.
The three stocks below are just a starting sample, and the full screen surfaced 57 more global oil and gas producers and integrated majors with equally compelling narratives that are not covered here. To identify and analyze the highest conviction ideas for your own portfolio, head straight into the Global Oil & Gas Producers and Integrated Energy Majors screener.
OKEA (OB:OKEA)
Overview: OKEA is a pure-play oil and gas producer on the Norwegian Continental Shelf, giving investors clear upstream exposure to global crude pricing.
Operations: The business generated about US$898 million from development and production of oil and gas, entirely from assets in Norway.
Market Cap: NOK4.1 billion
OKEA matters in this screener because it ties the headline story of higher global crude prices directly into producing Norwegian fields that already sit on key infrastructure.
"Ongoing infill and development drilling around existing hubs, such as Garn West South at Draugen and new production wells at Brage and Statfjord, is structured to keep using installed infrastructure more intensively. This can support field life and capital efficiency, with potential to benefit revenue and earnings."
The real swing factor for OKEA now is how one pressure on future profitability evolves as these mature fields move through their next investment cycle.
That pressure point is exactly why reading the full narrative for OKEA can clarify how OKEA’s next drilling phase could reshape risk, capital intensity and upside potential.

Amplitude Energy (ASX:AEL)
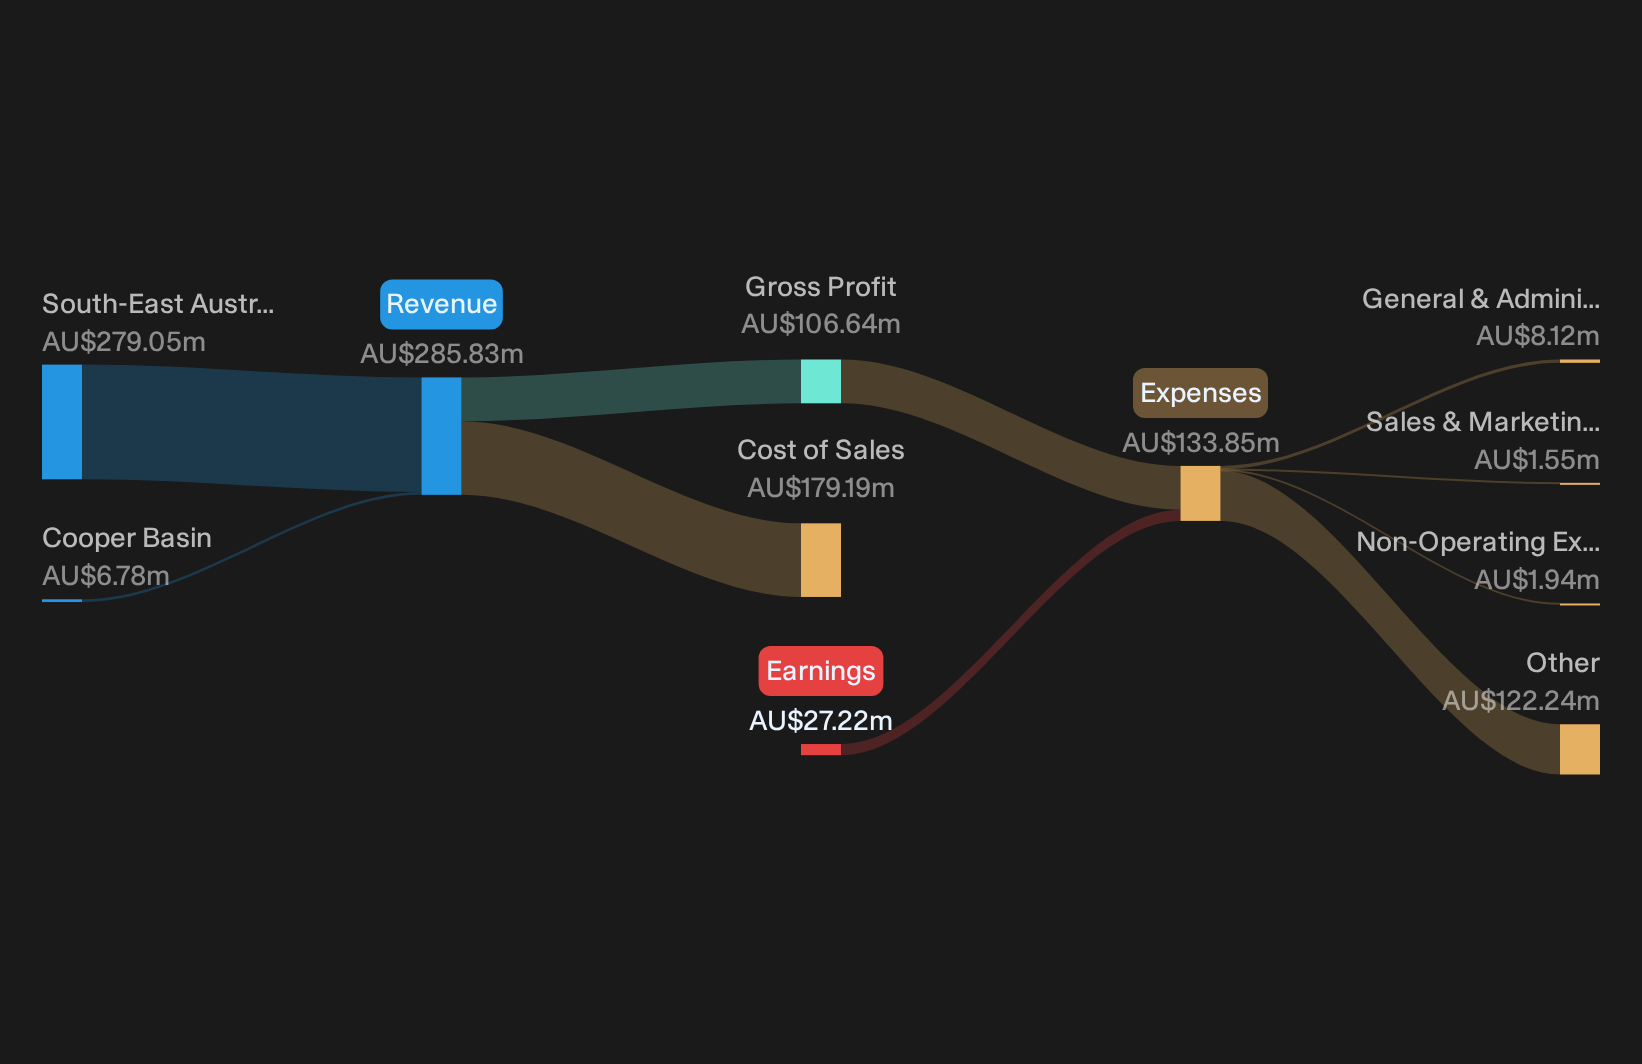
Overview: Amplitude Energy is an Australian producer focused on supplying domestic markets with natural gas and low-cost oil from its regional hubs.
Operations: The business generates about A$279 million from South-East Australia and A$7 million from the Cooper Basin, with all A$286 million earned domestically.
Market Cap: A$552 million
Amplitude Energy fits this oil and gas producer screen because it offers direct upstream exposure to Australian hydrocarbons at scale. Its East Coast gas focus is closely linked to any shift in global pricing power driven by Middle East supply worries.
"Improving reliability and higher run rates at Orbost, supported by sulfur processing upgrades and debottlenecking work, give the company more room to direct volumes into spot markets such as Victoria and Sydney, which directly supports revenue and EBITDAX margins."
What happens if one key assumption about future pricing in those domestic spot markets bends against the current optimistic forecasts?
If that pricing risk matters to you, read the full narrative for Amplitude Energy to see how Amplitude Energy’s next investment phase could accelerate or stall the story.
Prio (BOVESPA:PRIO3)
Overview: Prio is a Brazilian upstream oil and gas producer focused on offshore fields that give investors direct exposure to global crude pricing.
Operations: Prio reports about R$21.4b in revenue from oil and gas exploration and production, with all of it classified as foreign sales.
Market Cap: R$50.5b
Prio connects cleanly to this global producers theme because it is a pure play on lifting offshore barrels, so any spike in seaborne crude benchmarks quickly matters to how investors view its future cash generation.
"Ramp-up of production at the Wahoo field, supported by the recently obtained installation license and continuing progress on drilling/installation, is expected to add significant new output in 2026 and 2027, which in turn would increase both revenues and operating leverage if production grows faster than fixed costs."
The real test for Prio now is how one less visible cost and funding pressure behaves if crude stays volatile around these higher levels.
If that cost squeeze is on your mind, read the full narrative for Prio to see how Prio’s capital choices, funding mix and upside scenarios could be decoupling.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout stories, early momentum and falling valuations can get snapped up fast while they are still under the radar, so consider your options carefully.
- Spot resilient cash machines before income hunters arrive by scanning the 155 dividend fortresses and filtering for payouts that might help anchor a diversified portfolio.
- Track the next wave of automation leaders with the 95 robotics and automation stocks and see which operators are building businesses behind the headlines.
- Review infrastructure plays supporting AI demand using the 88 AI infrastructure stocks and see which enablers are contributing to data center activity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com