


PriceSmart (PSMT) Stock Still Looks Pricey Given Its Earnings Premium
PriceSmart has delivered a powerful share price run in recent years, which puts fresh attention on whether the current valuation is still grounded in what the warehouse retailer earns today. With the stock now well above levels of a few years ago, the core issue for you is how that price lines up with the earnings power of the business.
- PriceSmart has gained 137.4% over the past 3 years, which puts a lot of weight on the question of whether its earnings profile can carry that move.
- The company leans on a membership warehouse model and recurring fee income, which can shape how reliably earnings convert into cash and how much headroom there is for reinvestment or dividends.
- The analysts covering PriceSmart have run their own numbers. See what analysts think PriceSmart's shares could be worth.
The issue now is whether the current PriceSmart share price is justified by its earnings when stacked up against the Fair Ratio benchmark.
If you want more ideas with a similar earnings focus to PriceSmart, a good next step is to scan the market using the 33 high quality undervalued stocks
Has PriceSmart Run Too Far on Earnings?
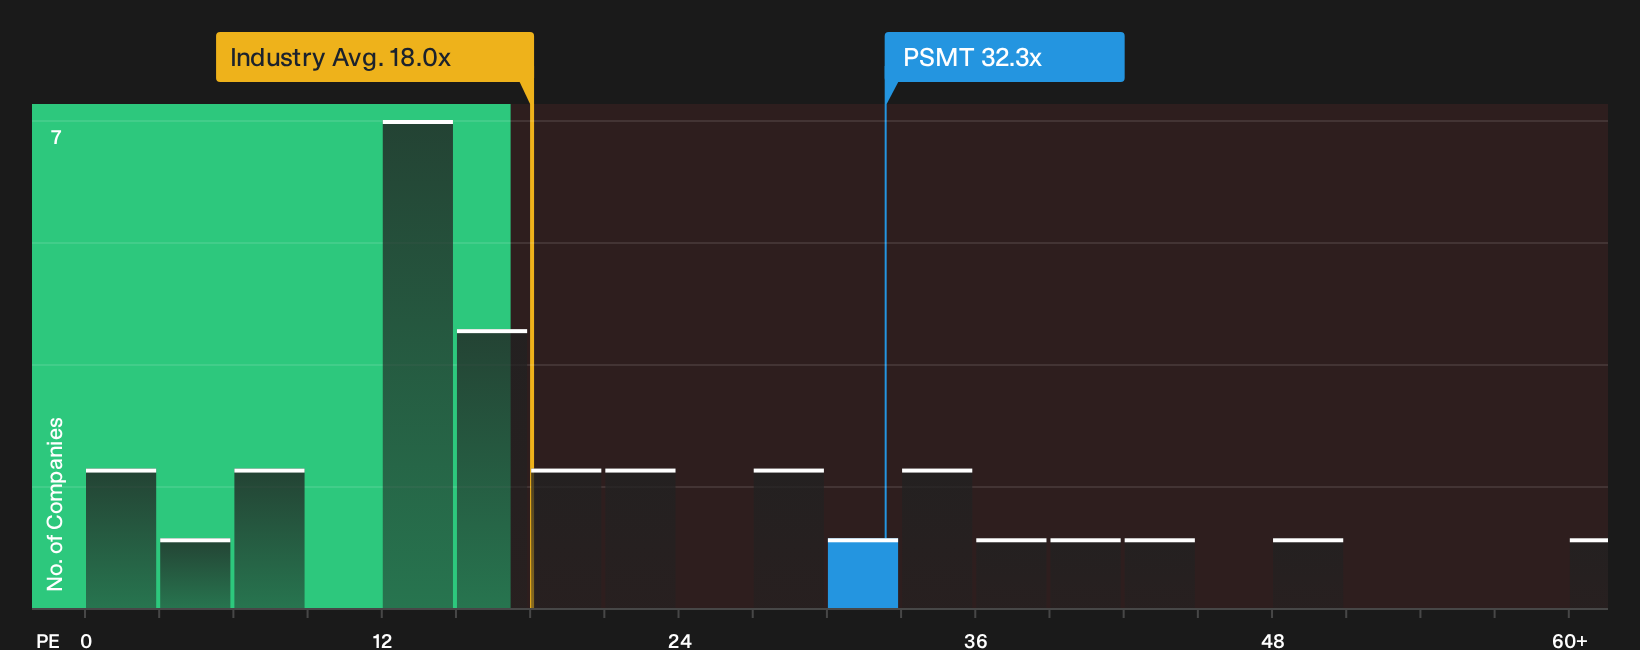
The P/E ratio fits PriceSmart because earnings are a central anchor for how investors frame membership retail businesses. On this yardstick, the stock trades on about 32.3x earnings, which is well above the Consumer Retailing industry average of roughly 18.0x and higher than the peer group on about 16.2x. That is a meaningful premium for a warehouse retailer whose story is built around recurring income and fairly straightforward store economics rather than hard to value intangibles.
The Fair Ratio, which reflects what you might expect for PriceSmart given its business quality, risks and sector, sits below the current market multiple. That gap suggests the shares screen as overvalued on this framework and that a lot of good news is already reflected in the price. For you as a shareholder or potential buyer, the key question is whether the company can keep justifying that richer P/E against other Consumer Retailing stocks or whether sentiment has moved ahead of what recent earnings support. Explore the numbers behind PriceSmart's P/E valuation.
The PriceSmart Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PriceSmart pick up where the P/E puzzle leaves you. They spell out which paths for PriceSmart's revenue, profitability and earnings would need to play out for the share price to end up materially higher or lower than it is today. Each one connects its implied number to a clear view on how growth, margins and risk might evolve that you can come back to as fresh information arrives on the Community page.
PriceSmart brings out two very different emphases in the community, with one group seeing more upside in the membership model than the other.
Bull case: 15% undervalued
"Disciplined expansion of warehouse clubs in underpenetrated markets such as Guatemala, Costa Rica and Jamaica, along with the planned entry into Chile, is set to enlarge the addressable member base and sustain high single digit revenue growth and club level earnings over time..."
Discover why this Narrative puts PriceSmart at 15% undervalued.
Bear case: roughly fairly valued
"Ongoing FX and liquidity challenges, complex supply chains, rising expenses, market saturation, and mounting competition threaten margins, profitability, and future revenue growth..."
Explore why this Narrative puts PriceSmart at roughly fairly valued.
PriceSmart's price is only one side of the story
Valuation frames what you pay today, but analyst projections for PriceSmart over the next few years give you another reference point to compare with that headline multiple and earnings profile. Explore where analysts expect PriceSmart to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com