


Will Leasing Momentum Change Simon Property Group Stock Narrative
- Simon Property Group has issued US$800 million of senior notes and reported robust first half leasing, with over 2,300 leases signed across 9.5 million square feet, while continuing to recycle capital by relinquishing weaker assets such as the Square One Mall in Saugus.
- The launch of the Simon Media Network and reduced tenant allowances highlight a push to extract more value from high traffic centers while tightening leasing economics in the portfolio.
- We will now look at how Simon Property Group's investment narrative could be influenced by its strong leasing activity and digital push.
Scan how Simon Property Group's refinancing and digital push compares with other landlords by reviewing our curated list of list of solid balance sheet and fundamentals (23 results).
Simon Property Group Investment Narrative Recap
To own Simon Property Group, you need to believe its premier centers can keep attracting retailers and shoppers even as weaker malls struggle. The near term story is about keeping occupancy high and rent spreads healthy while retailer balance sheets stay mixed. The strong first half leasing and traffic data support that operating thesis, and the Saugus surrender does not materially change it.
The bigger swing factor right now is how Simon manages debt and reinvestment spending while earnings are expected by analysts to soften over the next few years. Rising rates and heavy redevelopment needs remain the key risk. Recent leasing results and the digital push help on the revenue side but do not fully offset that financial pressure.
The fresh US$800 million senior notes, with a weighted average term of 7.7 years and 5.450% coupon, matter most in this context. Simon plans to use the proceeds to refinance US$750 million of 3.250% notes due 2026 and possibly other unsecured borrowings. That extends maturities and locks in current funding costs, which you should weigh against higher coupons.
For an investor watching catalysts, this refinancing sits alongside the Simon Media Network launch and ongoing development spend as a core execution test. Strong leasing and digital monetisation can help support interest coverage and tenant demand. The flip side is that heavier interest expense and already high leverage leave less room if retail bankruptcies or traffic softness resurface.
Simon Property Group's current analyst narrative points to forecast revenue of US$7.4b and earnings of US$2.5b by 2029, based on an assumed 2.0% yearly revenue growth rate. That path implies earnings today of US$4.6b would decline by US$2.1b to reach the 2029 consensus level.
Uncover why Simon Property Group's fair value indicates a 14% potential upside to its current price that investors may see realized sooner than expected.
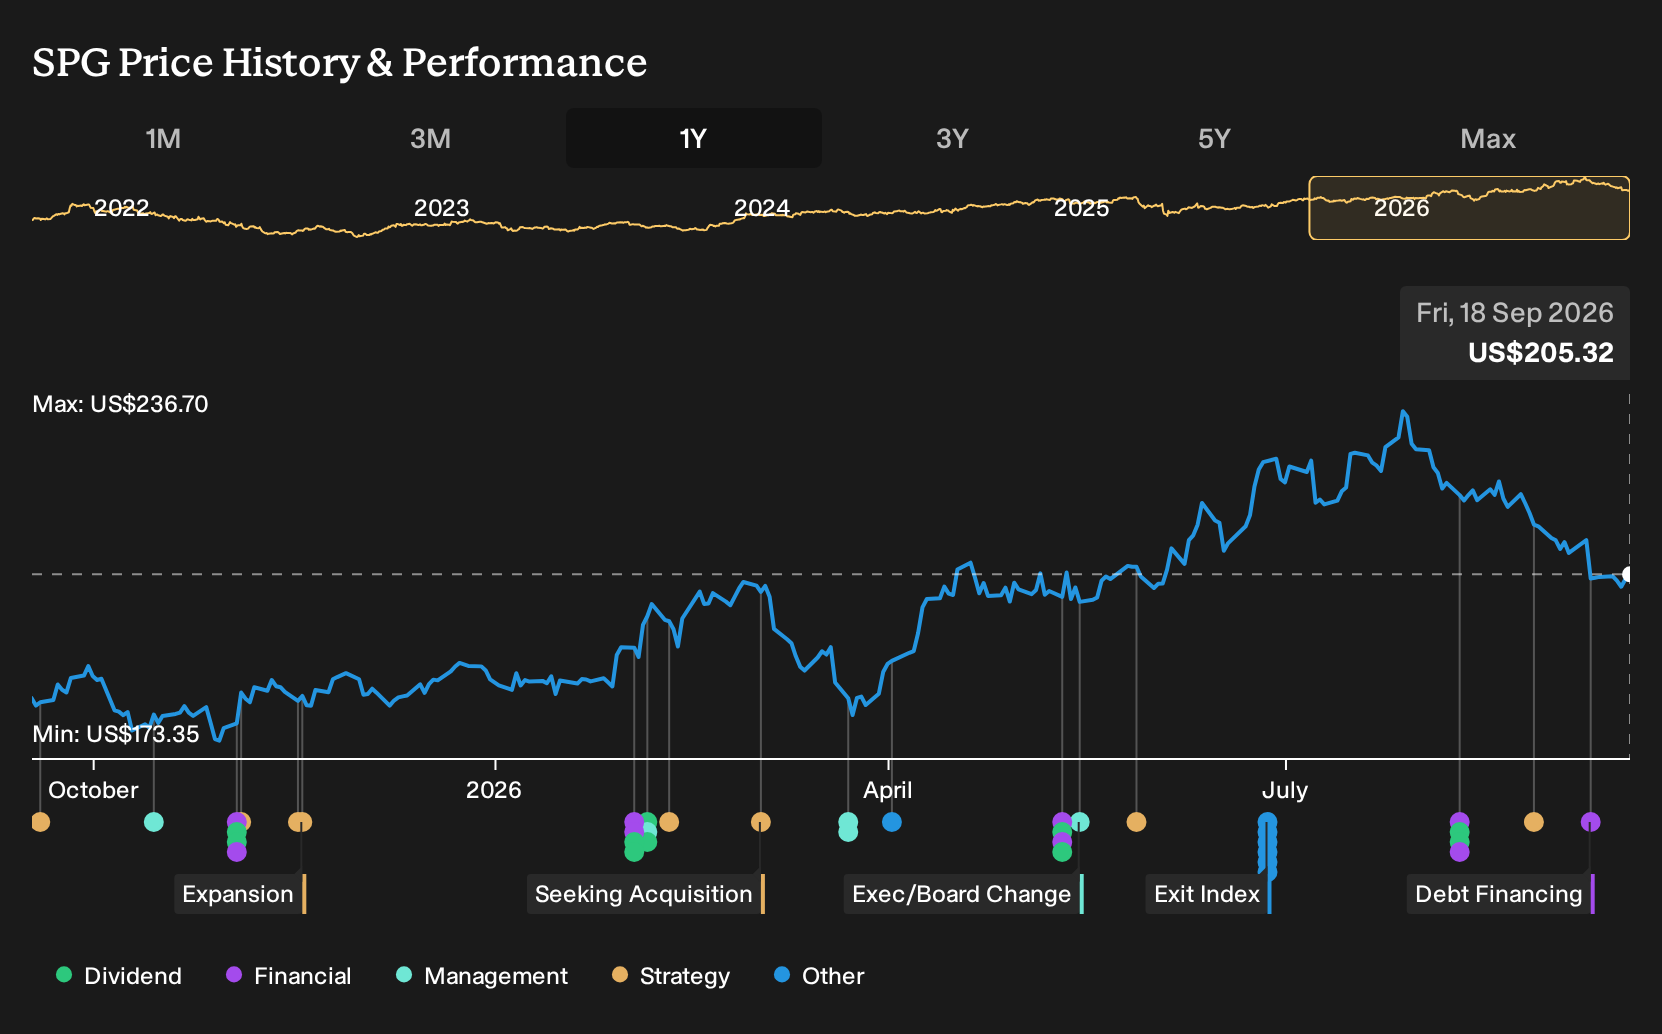
Exploring Other Perspectives
Fair value estimates for Simon Property Group in the Simply Wall St Community span roughly US$233 to US$302 across 2 individual views, so you are looking at a wide personal range. In addition, risks such as refinancing at higher coupons and heavy redevelopment spend mean that the upcoming BofA conference could shift how investors frame these competing stories.
Explore another Simon Property Group fair value estimate, including one that suggests potential upside of up to 47% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Simon Property Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Simon Property Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simon Property Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Simon Property Group?
If the Simon Property Group story has sharpened your thinking about income, quality and balance sheet strength, it can be useful to line it up against other businesses with clear financial profiles. The Simply Wall St Screener helps you quickly filter for companies that match the kind of risk and return balance you want to target next.
- For investors focused on quality at a fair price, scan a focused set of companies that combine strong fundamentals with potentially attractive pricing through our 33 high quality undervalued stocks.
- If resilience and capital preservation sit high on your priority list, narrow your search to businesses with sturdier financial profiles by reviewing a 30 resilient stocks with low risk scores.
- For those who want to keep income on the table while still monitoring quality, line up options that offer higher yields with our curated 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com