


Will Ford Pro Expansion Change Ford's (F) Narrative
- Ford Motor has been rolling out an updated 2027 F-150 lineup with fresh styling, new in-cabin tech, and lower prices on several premium trims, while expanding Ford Pro software, telematics, and aftermarket services that already reach 1.6 million paid subscribers and roughly 530,000 active BlueCruise users.
- The push toward recurring digital revenue in Ford Pro, extended range electric trucks, and proprietary electrical architecture shifts Ford Motor’s focus from one off vehicle sales toward higher margin, subscription based fleet solutions and more durable earnings streams.
- Next comes a look at how Ford Motor’s push into software rich Ford Pro services could reshape the broader investment narrative around the stock.
Ford Motor Investment Narrative Recap
To own Ford Motor today you need to believe the shift toward Ford Pro software, data and service revenues can gradually turn a cyclical automaker into a more recurring cash generator. In the short term, the key swing factor is execution on this commercial platform, while keeping truck volumes healthy as the refreshed 2027 F 150 rolls out at sharper price points.
The biggest current risk sits in capital intensity and balance sheet strain. Debt is not well covered by operating cash flow and the dividend is not well covered by earnings, which limits room for mistakes. Recent concerns over Chinese partnerships and tariffs add another layer of cost and regulatory uncertainty but do not yet change the core thesis.
Among recent developments, Ford Motor joining Toyota and General Motors in a coalition urging the White House to keep barriers on Chinese vehicles has direct links to both risk and opportunity. Protection from low cost Chinese imports could support pricing for trucks, SUVs and future EVs, which matters for a business still heavily tied to ICE profitability.
The same move highlights how exposed Ford is to trade policy and tariff swings. Material and battery partnerships with Chinese groups are already drawing national security questions from regulators, while analysts flag up to a US$2b tariff headwind as a key risk. For you as a shareholder, the near term catalyst lies in whether management can grow Ford Pro software subscriptions and extended range EV offerings fast enough to offset any pressure from higher costs or policy shifts.
Ford Motor's narrative projects US$192.2b revenue and US$16.2b earnings by 2029. This implies relatively flat yearly revenue growth and an earnings change of US$23.6b from a current loss of US$7.4b.
Uncover why Ford Motor's fair value indicates a 19% potential upside to its current price that may not last much longer.
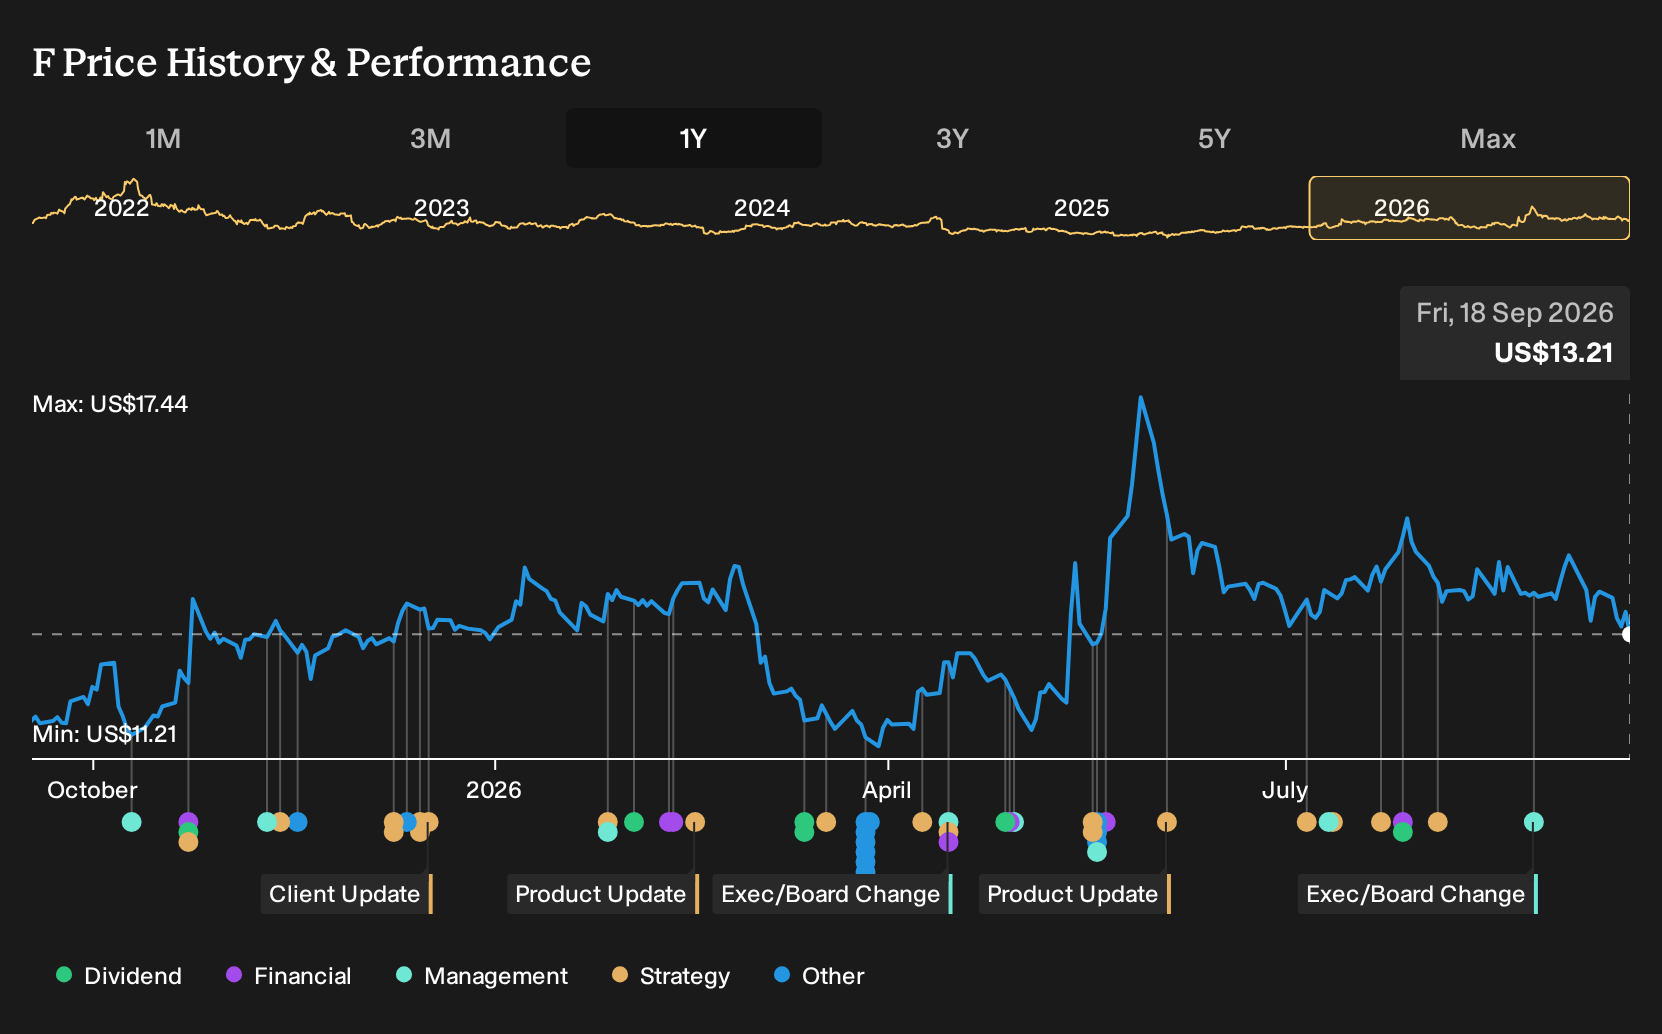
Exploring Other Perspectives
One bullish perspective on Ford Motor focuses on conference catalysts rather than tariffs. The most optimistic analysts were already penciling in about US$193.2b of revenue and US$14.5b of earnings by 2029, and a P/E of 7.8x, before this Laguna conference slot was on the calendar. Their outlook could become more optimistic, or be scaled back, once more information is available and you compare a few different angles for yourself.
Explore 5 other Ford Motor fair value estimates, including one that suggests as much as 50% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ford Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ford Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ford Motor's overall financial health at a glance.
Looking for more Ford Motor investment ideas?
Once you have a view on Ford Motor, it often helps to compare that thesis with a few other opportunities that fit different risk and income profiles. The Simply Wall St Screener can help you quickly scan the market for stocks that match the kind of portfolio role you want Ford to play.
- If you are aiming for value with quality fundamentals, test your thesis against a broader opportunity set by running a search through the 33 high quality undervalued stocks.
- For investors who care most about capital resilience and steadier business profiles, consider building a watchlist starting with the 30 resilient stocks with low risk scores.
- If a strong financial position matters to you before anything else, compare Ford Motor with companies in the list of solid balance sheet and fundamentals (23 results) to see how its balance sheet stacks up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com