


Should Clean Fuel Project Require Action From Plug Power Stock Investors?
- Plug Power featured as a key technology provider in a multibillion dollar sustainable aviation fuel project in Uzbekistan and recently presented at the Midwest NDR conference, giving investors fresh detail on its operations and financing plans.
- The Uzbekistan project, which could use up to 2.4 GW of Plug Power GenEco PEM electrolyzers, highlights the company’s focus on large, capital intensive clean hydrogen deployments, alongside efforts to refresh GenDrive units and pursue asset sales.
- Next, the focus will be on how Plug Power’s role in this large SAF electrolyzer project could reshape its already complex investment narrative.
Scan beyond Plug Power and evaluate how other potential clean energy and high-growth stories compare on valuation and quality inside our curated list of 33 high quality undervalued stocks.
Plug Power Investment Narrative Recap
To own Plug Power, you need to believe the hydrogen buildout can eventually support a healthier margin profile and more self funded growth. The business is still dealing with losses and cash burn, so the real hinge point is whether operational fixes, GenDrive refreshes and large electrolyzer contracts can tighten unit economics over the next stretch.
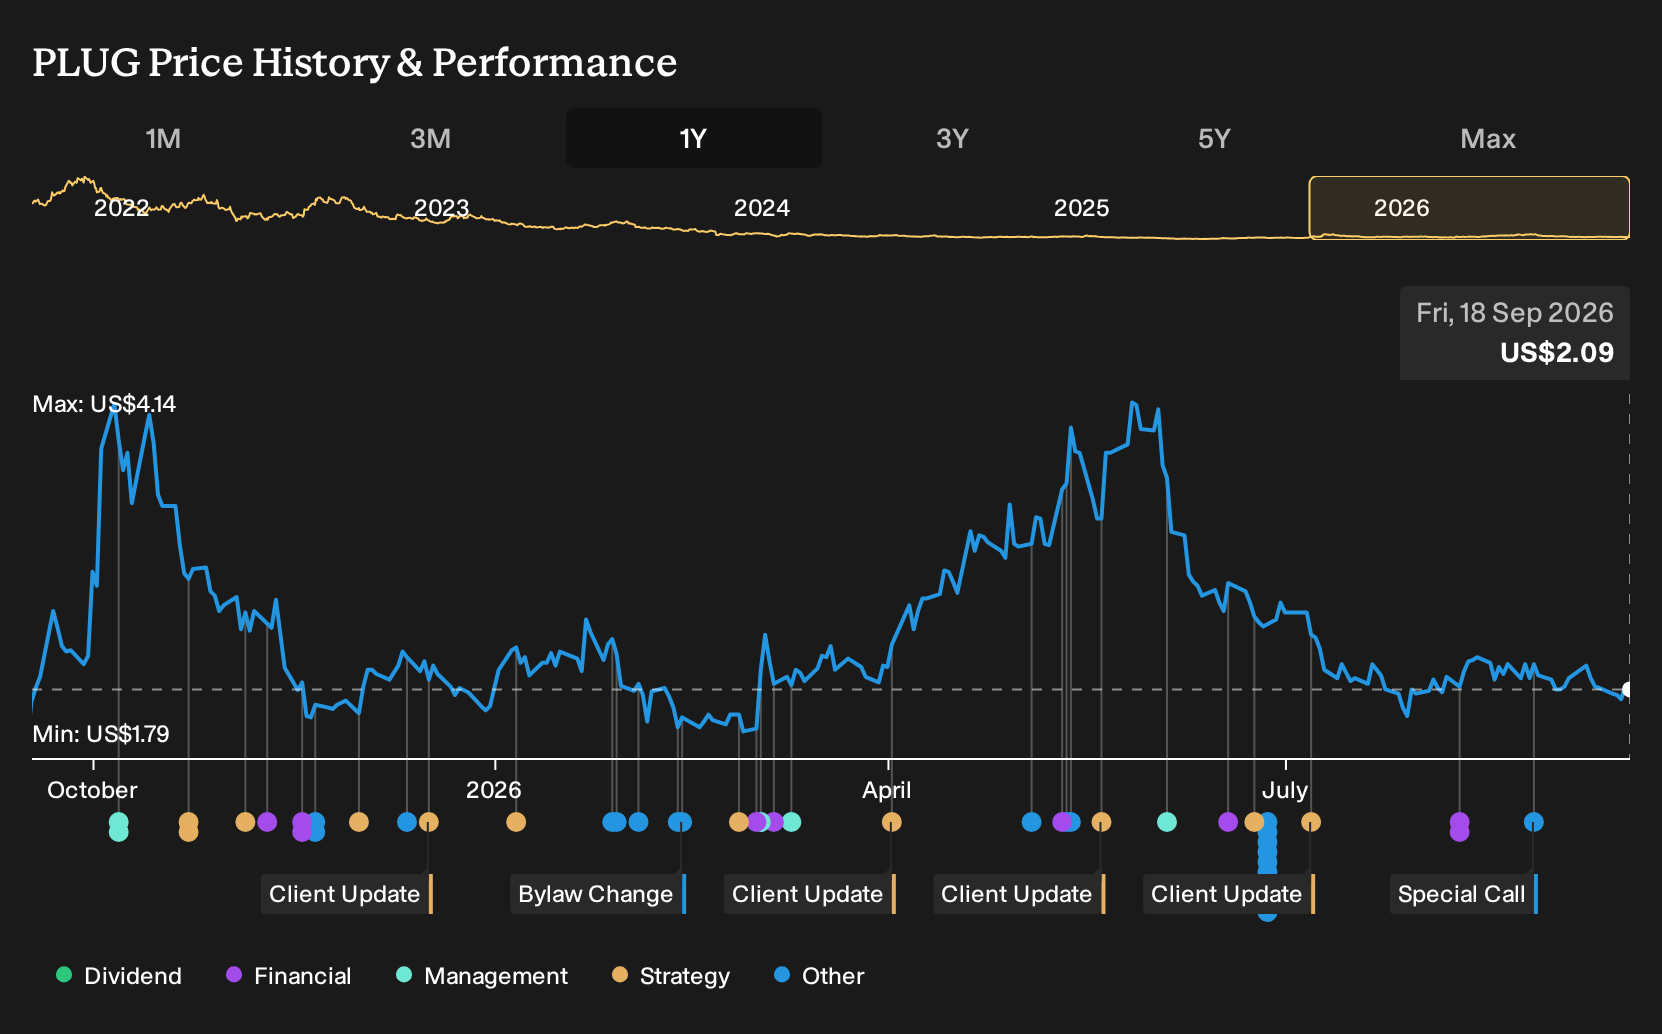
Recent Uzbekistan electrolyzer news and the Midwest NDR presentations mainly reinforce the existing story rather than redefine it. The key near term catalyst is clearer progress toward gross margin breakeven. The biggest risk remains liquidity pressure, with less than one year of cash runway and potential dependence on fresh capital.
The Uzbekistan SAF project announcement looks most relevant here. It shows Plug Power positioning its GenEco PEM electrolyzers in very large, multi gigawatt style deployments. If executed, such projects could support future top line scale and help absorb fixed costs across manufacturing and service operations.
That kind of pre FID project also underlines the main execution risk. Revenue timing hinges on permitting, funding and customer decisions that sit outside Plug Power’s direct control. For you as a shareholder, the real question is whether these big pipeline opportunities arrive fast enough to offset ongoing losses and any further dilution.
Plug Power’s current analyst narrative points to revenues of US$1.2b and earnings of US$137.5m by 2029, based on 18.5% yearly revenue growth and an earnings change of about US$1.8b from today’s loss of US$1.7b.
Uncover how Plug Power's fair value indicates a 70% potential upside to its current price that could narrow quickly if sentiment turns.
Exploring Other Perspectives
For Plug Power, the alternate narrative centers on rapid cost progress. The most bullish analysts were already modeling about US$1.5b of revenue and US$11.7m of earnings by 2029, well before the Uzbekistan SAF electrolyzer news. That optimistic view could shift again as you explore how new information challenges or supports those expectations.
Explore 3 other Plug Power fair value estimates, including one that suggests as much as 227% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Plug Power research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Plug Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plug Power's overall financial health at a glance.
Looking For More Investment Ideas Beyond Plug Power?
If Plug Power has you thinking about where risk and reward line up best in your portfolio, it can help to compare it with other opportunities using a structured stock screener.
- Hunt for potential mispricings by filtering for quality, value, and financial strength in our curated set of 33 high quality undervalued stocks.
- If capital preservation and balance sheet resilience matter most to you, start with this focused list of solid balance sheet and fundamentals (23 results).
- Prefer income over story stocks? Zero in on companies with sizeable yields and robust coverage using our dedicated 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com