


PJT Partners (PJT) Selloff Has Put Its Valuation Back In Focus
PJT Partners (PJT) has drawn fresh attention after recent share price moves, with the stock roughly flat over the past 3 months but down about 12% over the past month.
For context, PJT Partners now trades at US$151.47 after a 7-day share price return that declined 7.19% and a 30-day share price return that fell 12.44%. The year-to-date share price return is down 10.66%, and the 1-year total shareholder return has declined 18.79%, compared with a 3-year total shareholder return of 99.73% and a 5-year total shareholder return of 108.49%, which points to fading short-term momentum following what has so far been a strong longer-term run.
Stress test PJT Partners against peers by scanning a hand picked list of solid balance sheet and fundamentals (23 results) that have held up better through recent swings.
Bulls argue PJT Partners is being marked down despite solid advisory scale, while bears see a premium fee earner finally repricing. The valuation work now needs to show which side the current US$151.47 tag supports.
Preferred P/E of 19.4x for PJT Partners: Is it justified?
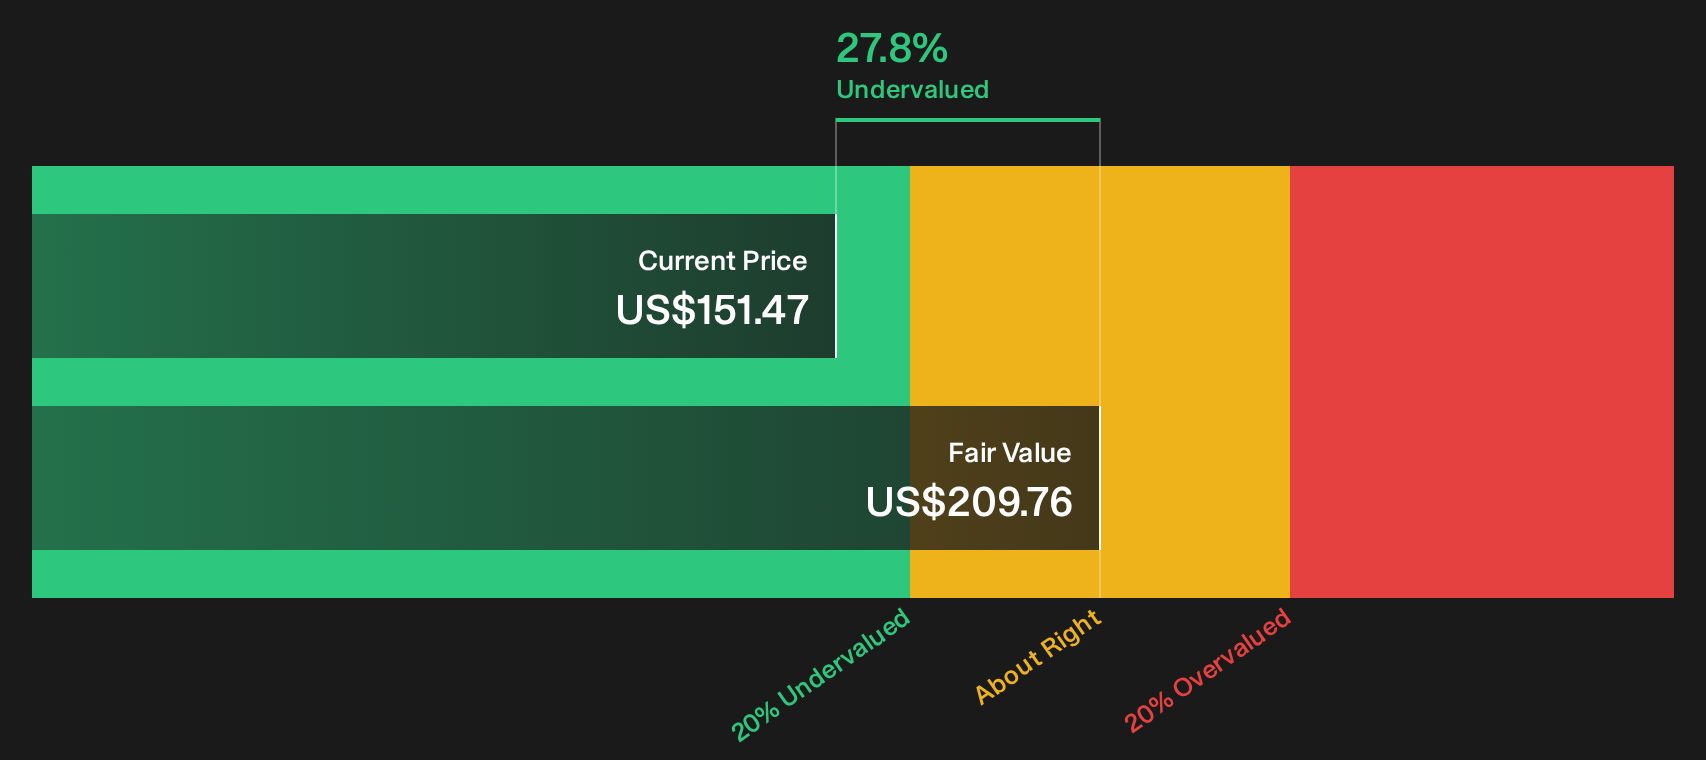
On the valuation side, PJT Partners currently screens as undervalued on several fronts, with the SWS DCF model estimating a future cash flow value of $209.76 against a last close of $151.47, and the shares also flagged as good value on earnings multiples.
The preferred yardstick here is the P/E ratio. PJT Partners trades on a P/E of 19.4x, which is described as attractive both versus the US Capital Markets industry average of 39.6x and versus a peer group average of 19.6x. For an advisory focused investment bank where earnings are a key driver, that earnings based gauge is a natural reference point for investors.
A P/E ratio reflects how much investors are paying today for each dollar of current profit. When that figure sits near peer levels but far below a broader industry average, it often suggests the market is assigning a more cautious earnings outlook or is waiting for clearer proof that recent profit trends can be sustained. At the same time, PJT Partners is also assessed as trading 27.8% below an internal fair value estimate, which implies the market price is not fully matching the modeled cash flow profile at this point.
Against the wider capital markets group, the valuation gap is stark. The stated 19.4x P/E for PJT Partners is roughly half the 39.6x industry average, which points to a materially lower earnings multiple than many US capital markets peers carry. With no fair ratio available for comparison, the discussion rests on that relative discount and the separate estimate that the current $151.47 level sits 27.8% below an intrinsic value of $209.76 using the SWS DCF model.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 19.4x (UNDERVALUED)
Still, the PJT Partners story can be knocked off course if capital markets activity cools or if advisory fees fail to match the current P/E expectations.
Find out about the key risks to this PJT Partners narrative.
Another View on PJT Partners' value
A different lens comes from analyst price targets rather than the SWS DCF model. The consensus target of $187.80 sits 24% above the current $151.47 level and aligns with the view that PJT Partners trades 27.8% below an internal fair value estimate. Is this simply a discount, or a signal that assumptions need more scrutiny?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PJT Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on PJT Partners so far. If that feels familiar, treat it as a prompt to dig into the numbers yourself and weigh both sides of the story with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond PJT Partners?
If PJT Partners has your attention but you want a wider bench of ideas, use the Simply Wall St screener to keep building out your watchlist.
- Target steady compounding potential by reviewing a curated 30 resilient stocks with low risk scores that may help you focus on resilience when markets turn choppy.
- Hunt for mispriced quality by scanning a focused set of 16 high quality undiscovered gems that many investors might not be watching yet.
- Sharpen your income game by zeroing in on 6 dividend fortresses that could support a stronger yield focused portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com