


Learn Why The Bull Case For Air Canada (TSX:AC) Could Change Following Skytrax Award Wins
- Air Canada was recently recognized at the 2026 Skytrax World Airline Awards as Best Airline in North America for a second consecutive year, alongside wins for its Toronto Signature Suite dining, cabin crew in Canada, and economy catering in North America.
- The cluster of service awards signals that Air Canada’s investment in premium cabins, lounges, and onboard experience is resonating with higher-yield travelers, which connects directly to its focus on premium revenue mix and loyalty economics.
- This raises the question of how Air Canada’s investment narrative around premium demand and service quality is affected by its repeat Best Airline recognition.
Scan beyond Air Canada to see which other carriers and travel plays might be building similar premium stories with our hand picked 9 high quality undiscovered gems in the sector and adjacent services.
Air Canada Investment Narrative Recap
To own Air Canada, you need to be comfortable with a story built on premium demand, international routes and loyalty economics, while margins remain tight. The recent Skytrax wins reinforce the premium angle but do not change the near term swing factors. Labor inflation, higher interest costs and yield pressure on key long haul routes still look like the big near term watchpoints.
On the other side of the ledger, premium cabins already account for close to 31% of passenger revenue and global travel appetite remains important for Air Canada’s international footprint. The awards support that positioning, yet they do not remove exposure to high capex, fuel and currency volatility, or structural softness in some transborder markets.
The upcoming appearance at Morgan Stanley’s 14th Annual Laguna Conference on 17 September 2026 is the clearest touchpoint linked to this news. With CFO John Di Bert speaking, investors get a fresh read on how Air Canada frames these Skytrax wins inside its premium and loyalty narrative, and how management talks about capital allocation against that backdrop.
Listening for detail on unit revenue trends, premium mix, interest coverage and fleet spending could be particularly useful. Any commentary around the 1.8% net margin, pressure from rising labor costs and competition on Pacific routes will help you judge whether the service accolades are translating into better earnings quality or simply reinforcing brand strength without easing the main financial risks.
What the Air Canada Consensus Is Really Pricing In
Air Canada's narrative points to forecast revenue of CA$28.8b and earnings of CA$566.8m by 2029, built on analysts assuming 6.8% yearly revenue growth and an earnings increase of about CA$136.8m from CA$430.0m today.
Uncover why Air Canada's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
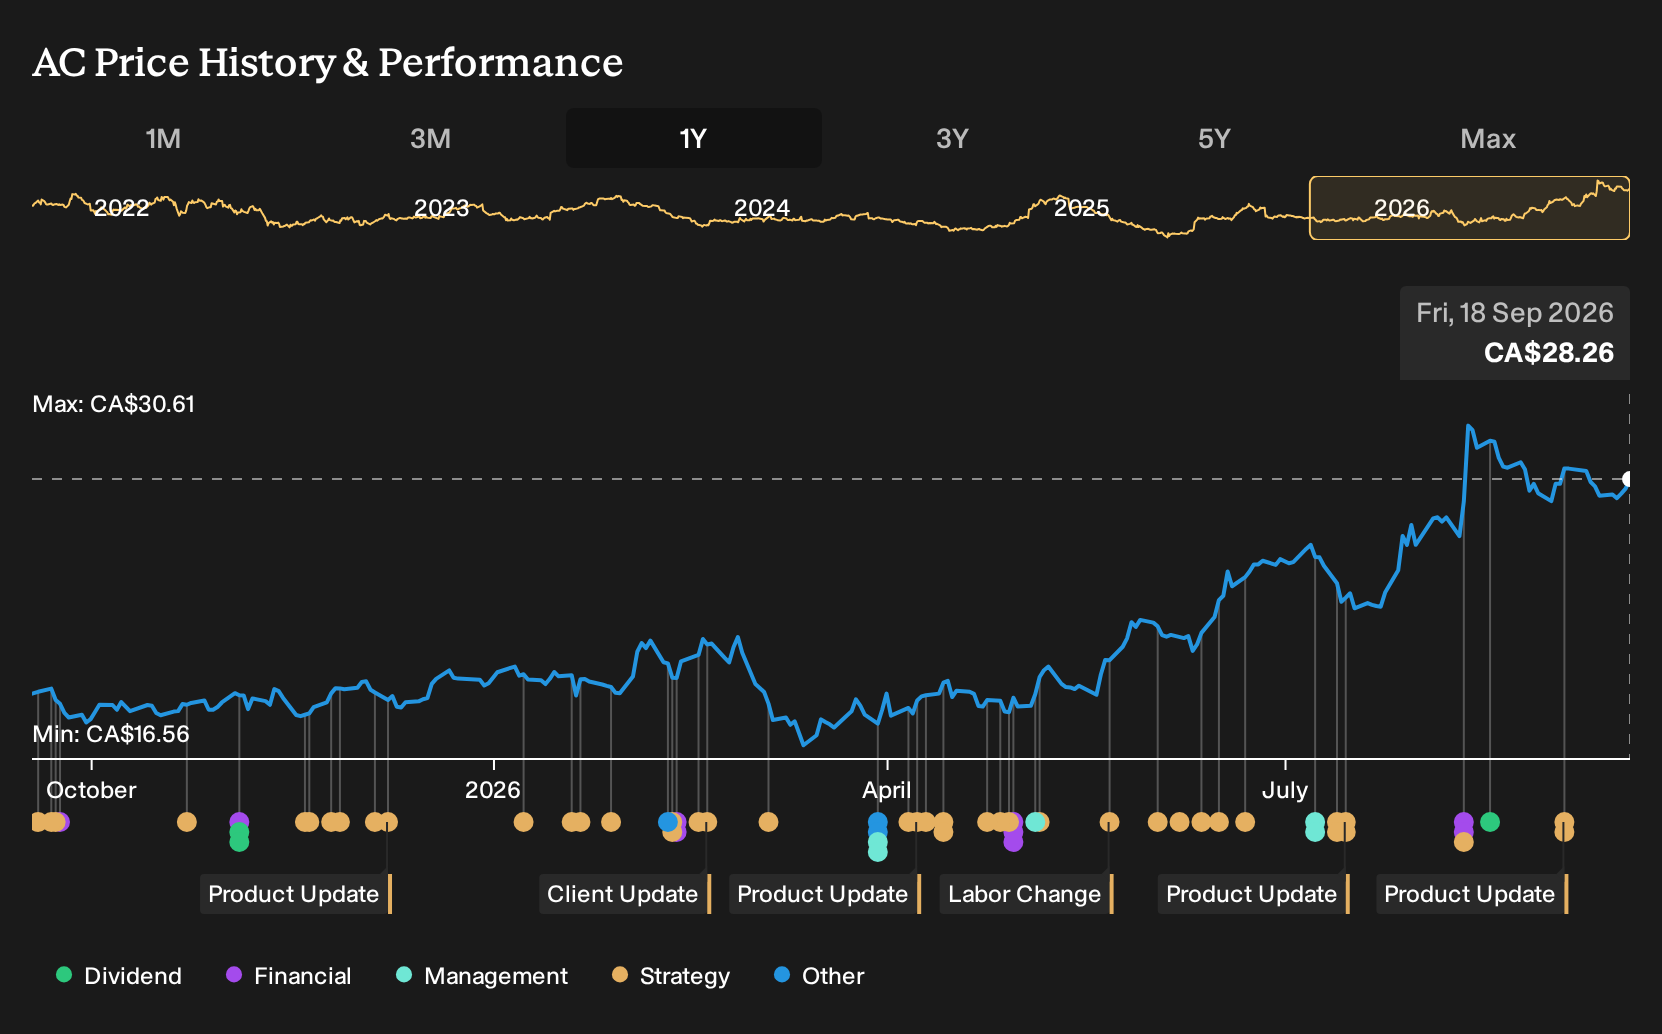
Exploring Other Perspectives
You can read the Skytrax wins and the Laguna conference through a very different lens. The most optimistic analysts were already modelling CA$30.6b of revenue and CA$1.1b of earnings by 2029, almost double the consensus profit view. That crowd treats Air Canada’s premium push as a powerful accelerator, while others see the same data as fragile. Use this gap as a cue to explore multiple narratives before you decide how the new awards and conference messaging might reshape expectations.
Explore 5 other Air Canada fair value estimates, including one that suggests as much as 191% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on thorough research and analysis.
- A great starting point for your Air Canada research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Air Canada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Air Canada's overall financial health at a glance.
Looking For More Ideas Beyond Air Canada?
If the Air Canada story has you thinking more broadly about travel, premium demand or balance sheet strength, it can help to widen the lens across other listed businesses using the Simply Wall St Screener.
- For investors who want quality on sale, start with companies that screen as attractively priced on fundamentals through the 4 high quality undervalued stocks.
- If capital preservation is front of mind, narrow your radar to businesses that score well on financial resilience using the 8 resilient stocks with low risk scores.
- For readers who care most about strong finances backing the equity story, look across the list of solid balance sheet and fundamentals (7 results) and compare debt loads, cash positions and core profitability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com