


India Export Stocks Poised For an FTA Boost Investors May Have Missed
Trade deals usually sound distant until tariffs actually disappear. With the India–New Zealand FTA expected to kick in within weeks, some Indian exporters could suddenly see a bigger, friction-light market open up overnight. That kind of rule change can reshape which stocks quietly pull ahead and which get left behind. This article unpacks three exporters from our screener that appear directly exposed to this new trade corridor.
The three exporters covered below are only a starting sample from this idea. The full screen surfaced 32 more Indian Industrials and Healthcare companies with equally compelling export narratives that are not discussed here. To identify and analyze those additional candidates in seconds, head straight into the India-focused Export-Oriented Industrials & Healthcare screener.
Privi Speciality Chemicals (BSE:530117)
Privi Speciality Chemicals plugs directly into the screener’s export story as a Mumbai based aroma and fragrance ingredient supplier that sells into global home and personal care supply chains.
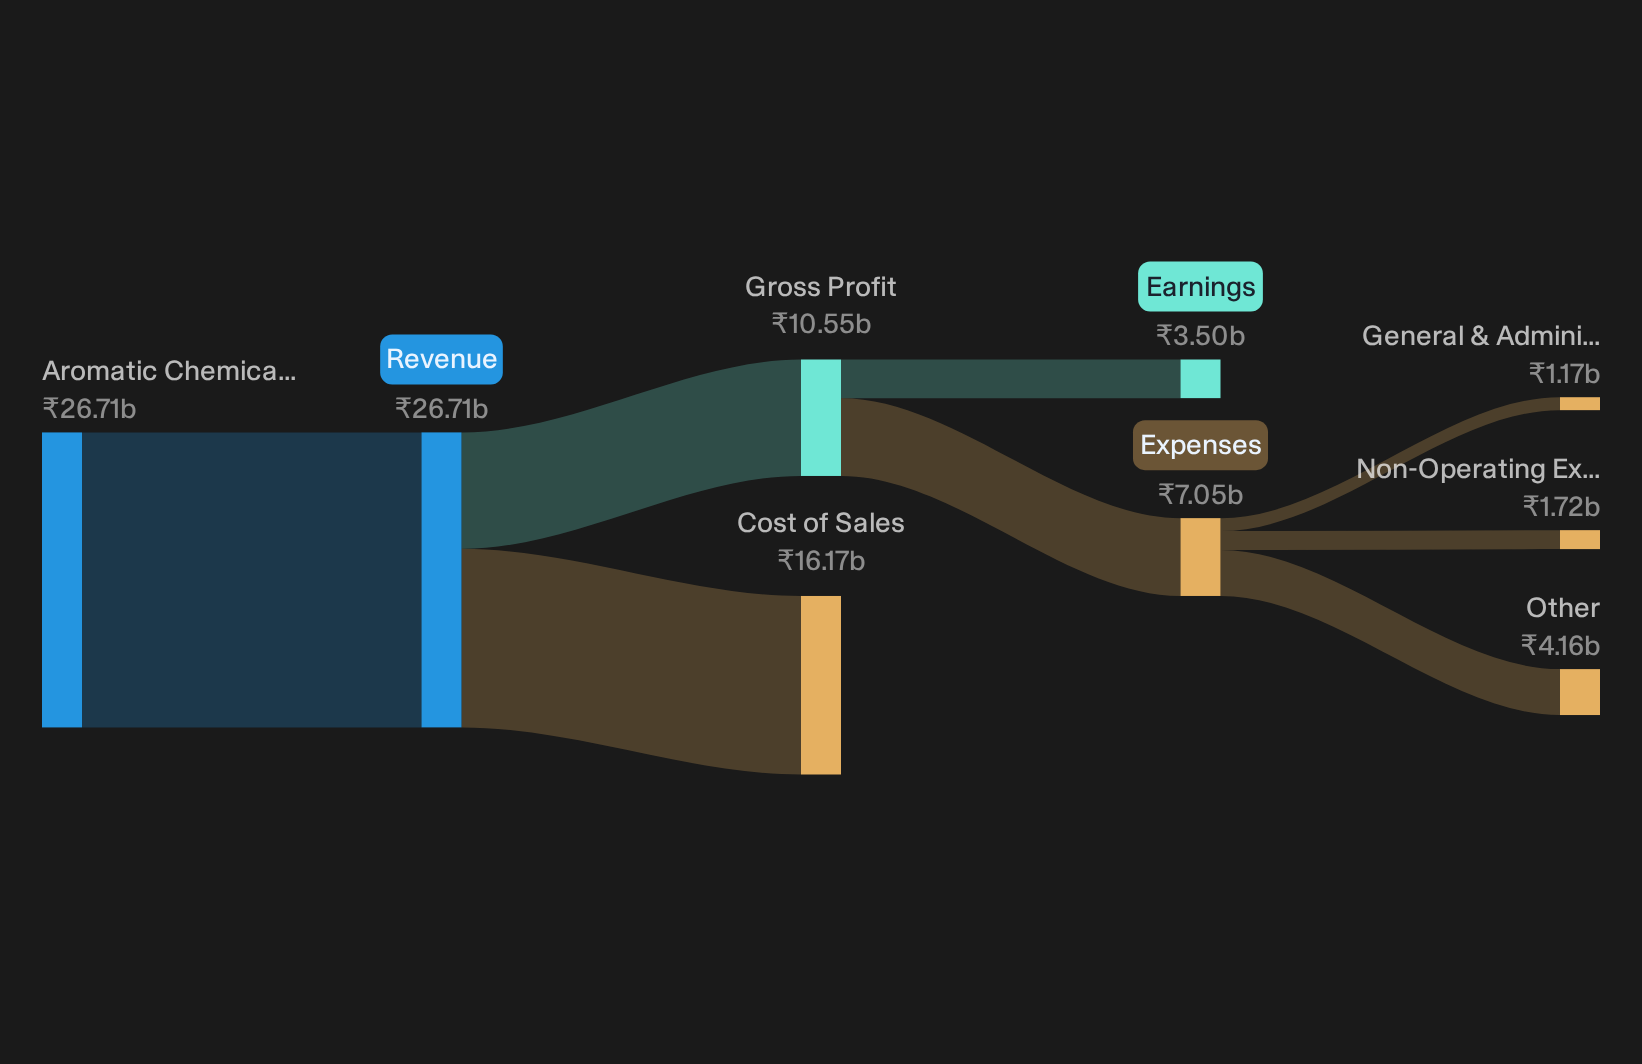
Privi Speciality Chemicals generates its entire reported top line of about ₹26.7b from aromatic chemicals. This gives it pure play exposure to export oriented specialty chemistry, and the stock carries a market value of roughly ₹134.6b.
"Ongoing capacity expansion from roughly 48,000 tonnes to 54,000 tonnes, combined with continuous process intensification and debottlenecking, increases operating leverage as fixed costs are spread over higher output, which can allow earnings to grow faster than volumes."
What happens to that earnings potential depends heavily on how one less visible cost side pressure plays out over the next few years.
That cost question sits at the centre of the real debate, which is unpacked in the full narrative for Privi Speciality Chemicals and shows how input volatility could reshape the earnings trajectory.
eClerx Services (NSEI:ECLERX)
eClerx Services brings the screener theme into the services world, acting as an export hub for data analytics, AI enabled process management and customer operations work that global clients choose to run from India.
eClerx Services generates its entire ₹43,348 million in revenue from data management, analytics solutions and process outsourcing services, and the stock carries a market value of about ₹176.3b.
"Strong demand for specialized compliance, KYC, and risk management services, particularly in the BFSI segment, positions eClerx to benefit from ongoing increases in regulatory complexity globally, potentially driving sustained revenue growth and higher average contract sizes."
What happens to eClerx Services margins and contract quality will hinge on how quickly its higher value AI heavy work offsets cost and pricing pressure.
If that shift in work mix is what really moves the needle, the full narrative for eClerx Services shows how eClerx Services could see earnings power move independently of simple headcount growth.

Piramal Pharma (NSEI:PPLPHARMA)
Piramal Pharma plugs neatly into the export-heavy pharma leg of this India-focused screener, with a footprint that runs from Mumbai across the US, Europe, Japan and other key markets.
Piramal Pharma operates a global pharma platform spanning contract development and manufacturing, complex generics, and consumer healthcare products. All reported revenue of about ₹92.1b comes from its Pharma segment, with a market value near ₹276.7b.
Piramal Pharma gives this export-oriented theme a pure pharmaceutical angle, with global manufacturing sites and a mix of outsourced development work, complex hospital products and everyday consumer brands that link Indian production capacity to overseas healthcare demand.
"The company's recent capacity expansion in key segments, such as the new Sevoflurane manufacturing lines targeting emerging markets and ongoing sterile fill/finish investments in the US, is intended to position it to capture rising demand for essential and complex pharmaceutical products as healthcare access broadens in both emerging and developed markets."
What happens to Piramal Pharma margins now hinges on how one less visible pressure shapes the balance between high-value CDMO work and capital-heavy expansion.
If that trade off is what really matters for Piramal Pharma, read the full narrative for Piramal Pharma to see how capacity bets could accelerate or quietly cap earnings power.

Seeking Fresh Alternatives Before Others?
Fresh ideas move first, and slow money often misses the breakout. Use this window while momentum is building and stories are still under the radar for now. Act now.
- Track cash rich compounders before they are widely talked about by screening for resilient balance sheets using the list of solid balance sheet and fundamentals (197 results).
- Spot income workhorses while yields remain elevated by running through the curated 155 dividend fortresses and checking which payouts still look well covered.
- Target future facing chips, data centers and backbone suppliers by scanning the handpicked 89 AI infrastructure stocks before AI infrastructure enthusiasm becomes fully mainstream.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com