


3 Insurance Stocks Tied To Sanctions Risk Retail Investors Should Watch
Every time Washington rewrites the rulebook on sanctions and tariffs, it quietly rewires global cash flows. The latest U.S. move on Russia and Iran hands the White House sweeping power over trade penalties, which can unsettle exporters, energy supply chains, and investors who ignore political risk. This article explains that shift and highlights 3 global insurers tied to political-risk and trade-credit cover that could be meaningfully affected by this new law.
The insurers in this article are only a starting sample, since the full screen surfaced 12 more global political-risk and trade-credit insurance providers with equally compelling narratives that are not covered below. To see the wider field and identify your own highest-conviction ideas, head straight into the Global Political-Risk and Trade-Credit Insurance Providers screener.
International General Insurance Holdings (IGIC)
International General Insurance Holdings writes specialty cover tied to global trade, including energy, marine, ports and political violence, which lines up with the sanctions and war-risk theme. Revenue is anchored in specialty short tail at about $244 million, long tail at roughly $133 million, and reinsurance near $85 million. The group is valued around $1.1 billion.
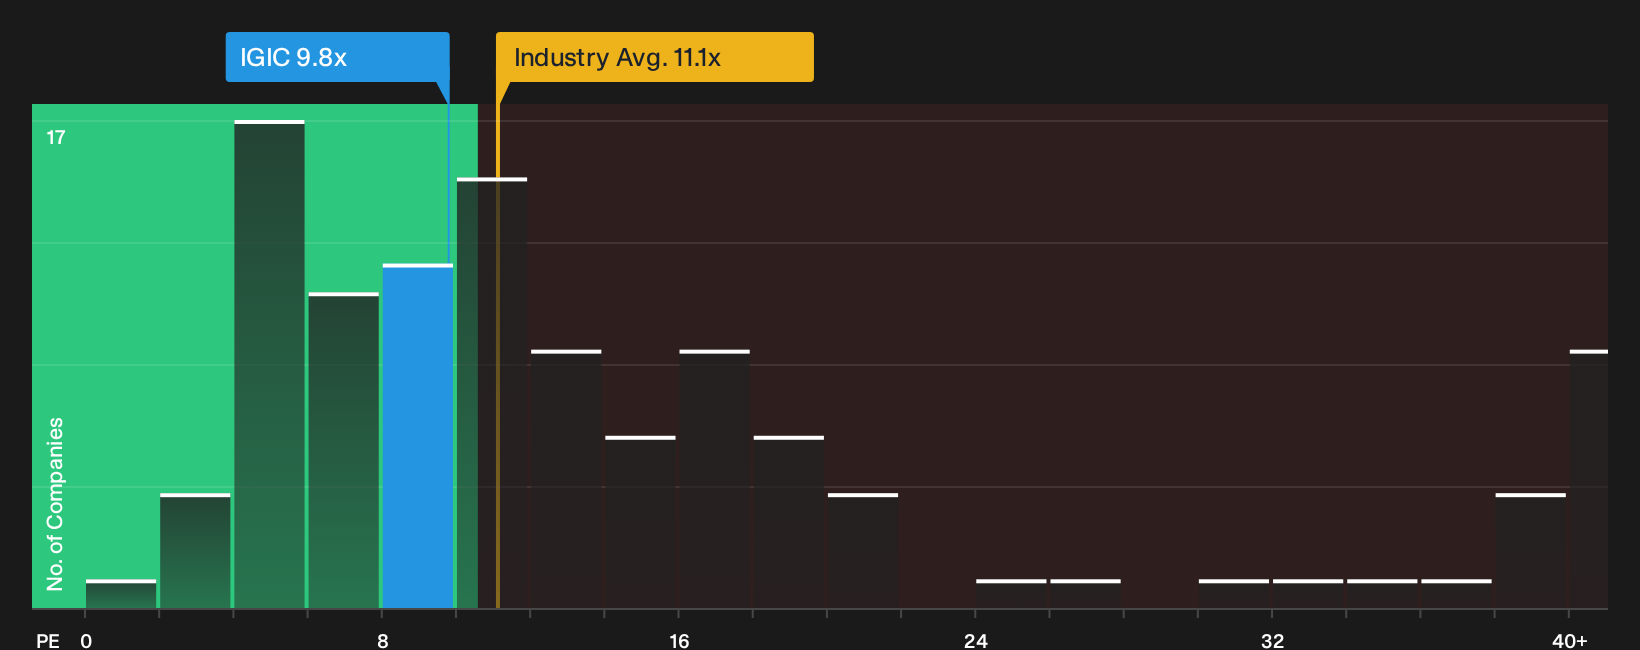
For investors watching how sanctions and tariffs reshape trade flows, International General Insurance Holdings offers focused exposure to marine, energy and political-violence risks linked to those cross-border routes, while trading on a single digit P/E multiple. A key consideration is how pricing in those niche books may respond if geopolitical friction remains prolonged.
If you want to see how that single digit P/E compares with its risk and reward profile, check the 3 key rewards and 1 important warning sign for the full picture.
Beazley (LSE:BEZ)
Beazley is a London based specialty insurer that fits this political risk and trade credit theme through its MAP and other cross border lines, with revenue spread across MAP Risks at about $946 million, Cyber Risks at roughly $976 million, Property Risks near $1.5b, Specialty Risks around $2.1b, and a market value close to £7.8b.
Where International General Insurance gives concentrated exposure to energy and marine routes, Beazley offers a broader mix of cyber, property and specialty cover that still ties closely to shifting sanctions and trade patterns. This is why its risk decisions matter so much for this theme.
"Growing reliance on complex reinsurance structures, including additional property excess of loss cover and over US$1b of cyber catastrophe protections, helps limit volatility but also increases ceded premium and reinsurance costs."
The real swing factor is how one quiet pressure on Beazley’s profitability shapes future pricing power and appetite for these specialty risks.
That quiet pressure is exactly what the full narrative for Beazley unpacks, revealing where Beazley’s risk appetite might be accelerating or masking potential areas of upside.

CNA Financial (CNA)
CNA Financial is a Chicago based commercial insurer with exposure to the same cross border risks that sit behind political risk and trade credit cover, writing property and casualty across the US, Canada, the UK and Europe. It generates about $5.7b from Specialty, $6.6b from Commercial, $1.5b from International and $1.3b from Life & Group, with a market value near $13b.
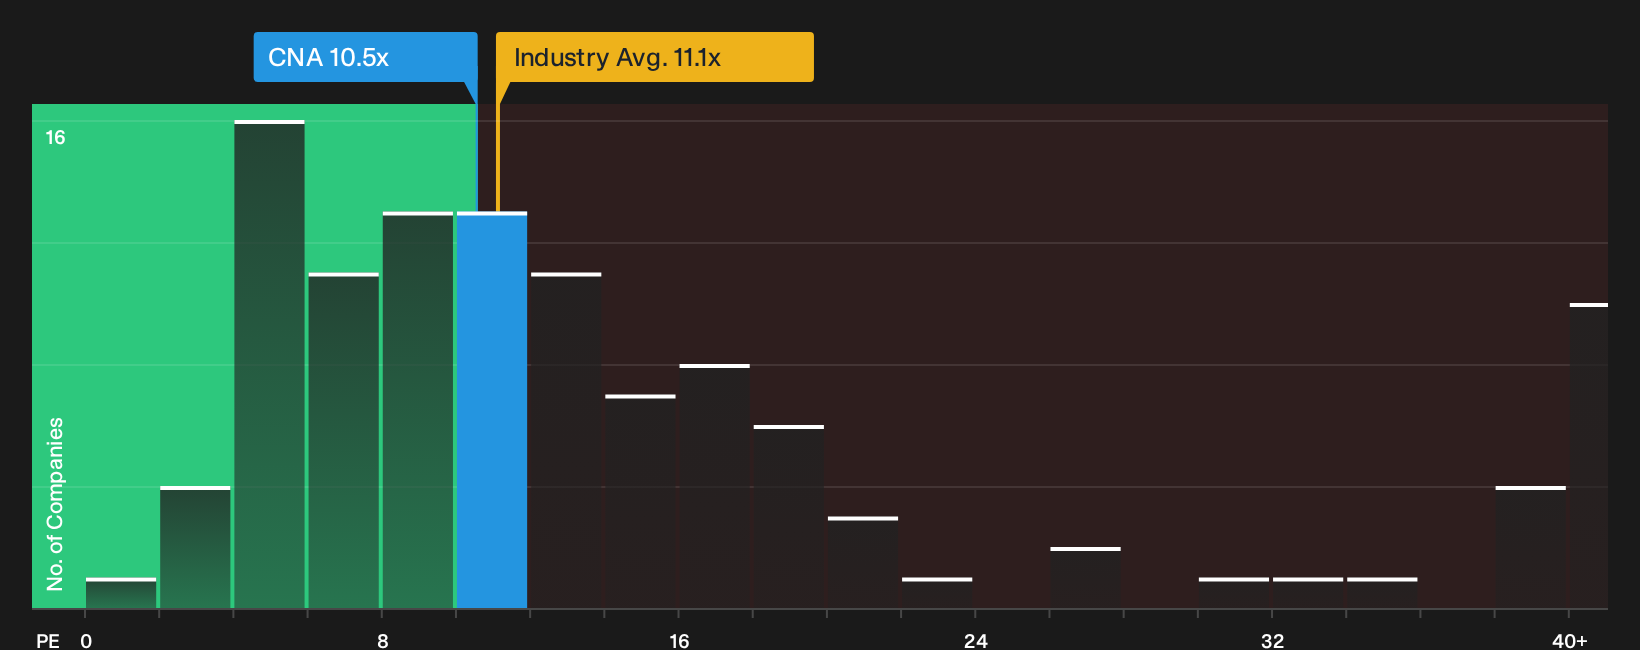
CNA Financial provides broad commercial cover that touches global trade routes, from property and marine to liability for professional and industrial clients. This ties it to the sanctions and tariff theme even if label driven political risk is not the main pitch. The stock trades on roughly a 10.5x P/E with earnings recently up 41%, which puts more weight on how one unseen pressure shapes future underwriting margins.
That unseen pressure on CNA Financial’s underwriting makes the 4 key rewards and 2 important warning signs the next stop if you want to spot where earnings power could be decoupling from headline ratios.
Seeking Alternatives Beyond Political Risk?
Fresh themes are already building breakout momentum while they are still under the radar for now. Do not get caught watching from the sidelines. Consider taking action based on your own research and objectives.
- Spot potential turning points in overlooked high yield payers by scanning the 6 dividend fortresses before prices move and income hunters crowd in.
- Track where capital is quietly shifting by reviewing the 30 resilient stocks with low risk scores and see which businesses could keep compounding while others hit turbulence.
- Target real assets with structural demand by running through the 36 elite gold producer stocks before gold producers react to the next sentiment swing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com