


What Analog Devices Earnings Beat Means For Shareholders
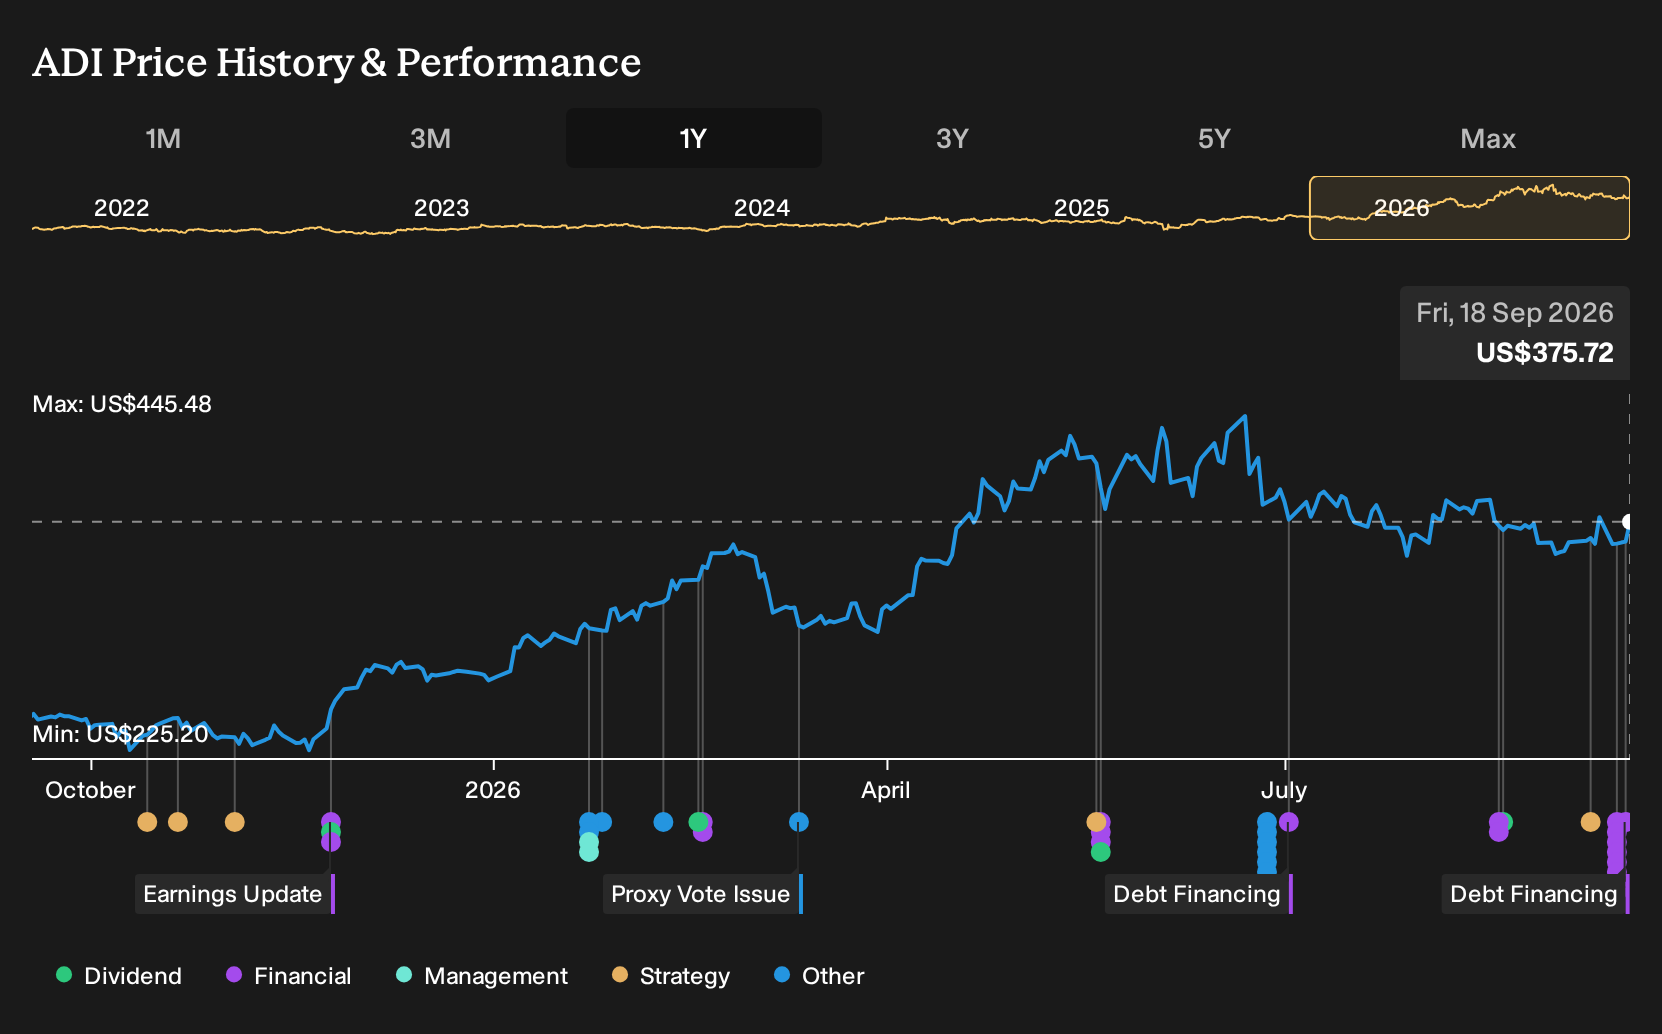
- Analog Devices issued US$3b of unsecured senior notes in September 2026 across four maturities from 2029 to 2036, with fixed coupons between 5.100% and 5.750% and semi-annual interest payments.
- The bond deals follow stronger than expected quarterly results and guidance, providing Analog Devices with an expanded pool of long term capital to support its industrial focused growth plans and broader operating needs.
- We will now look at how Analog Devices' recent earnings guidance and industrial positioning could influence the longer term investment narrative.
Scan how Analog Devices is using long term debt to fund industrial exposure, then size up peers with similar balance sheet profiles through our hand picked list of solid balance sheet and fundamentals (23 results).
Analog Devices Investment Narrative Recap
To own Analog Devices, you need to believe in long term demand for high value analog and mixed signal chips across industrial, automotive, and AI infrastructure, and in management’s ability to keep margins healthy as the business scales. The latest bond issue adds long dated funding but does not meaningfully alter that core thesis.
The key near term swing factor remains execution in Industrial, which accounted for US$1.97b in Q3 and 49% of total revenue, alongside delivery against the Q4 revenue guide of about US$4.3b and roughly 52% adjusted operating margin. The biggest current risk is heavier investment and competition compressing margins if demand softens.
The clearest link to that story is the new US$3b of unsecured senior notes maturing between 2029 and 2036 with coupons between 5.100% and 5.750%. This lifts fixed obligations but also locks in long term capital that can support internal manufacturing, R&D and industrial capacity tied to automation, AI and electrification trends.
As an investor, you would likely watch how Analog Devices balances this higher interest burden against its goal of maintaining high quality earnings and strong operating efficiency. If capital spending or inventory build run ahead of industrial and automotive demand, the added leverage could magnify earnings volatility, especially around any future inventory corrections or policy driven swings in EV and aerospace orders.
Analog Devices' narrative projects US$19.2b revenue and US$7.6b earnings by 2029. This implies 14.7% yearly revenue growth and an earnings increase of about US$4.3b from US$3.3b today.
Discover how Analog Devices' fair value indicates a 20% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Debt skeptics see a different story for Analog Devices. You might worry that more borrowing amplifies pressure if OEMs push harder into in-house chips. The most cautious analysts were modelling about US$20.3b revenue and US$7.0b earnings by 2029, compared with US$19.2b and US$7.6b in the baseline. Opinions already vary widely and may shift further as this new funding round beds in.
Explore 7 other Analog Devices fair value estimates, including one that suggests as much as 42% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Analog Devices research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Analog Devices. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Analog Devices' overall financial health at a glance.
Looking For More Ideas Beyond Analog Devices?
If you want to pressure test your Analog Devices thesis, it can help to line it up against other companies with different balance sheets, cash flow profiles, and income streams. The Simply Wall St Screener lets you filter for exactly the mix of quality, value, and resilience that fits your own approach.
- For investors who want quality and a margin of safety, start with a focused set of 33 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If income is a priority, narrow your watchlist to companies offering reliable payouts through our curated group of 6 dividend fortresses that combine yield with balance sheet strength.
- For a more cautious approach, zero in on resilience by scanning a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com