


How Investors May Respond To Nisshinbo Holdings (TSE:3105) Earnings Outlook Raised
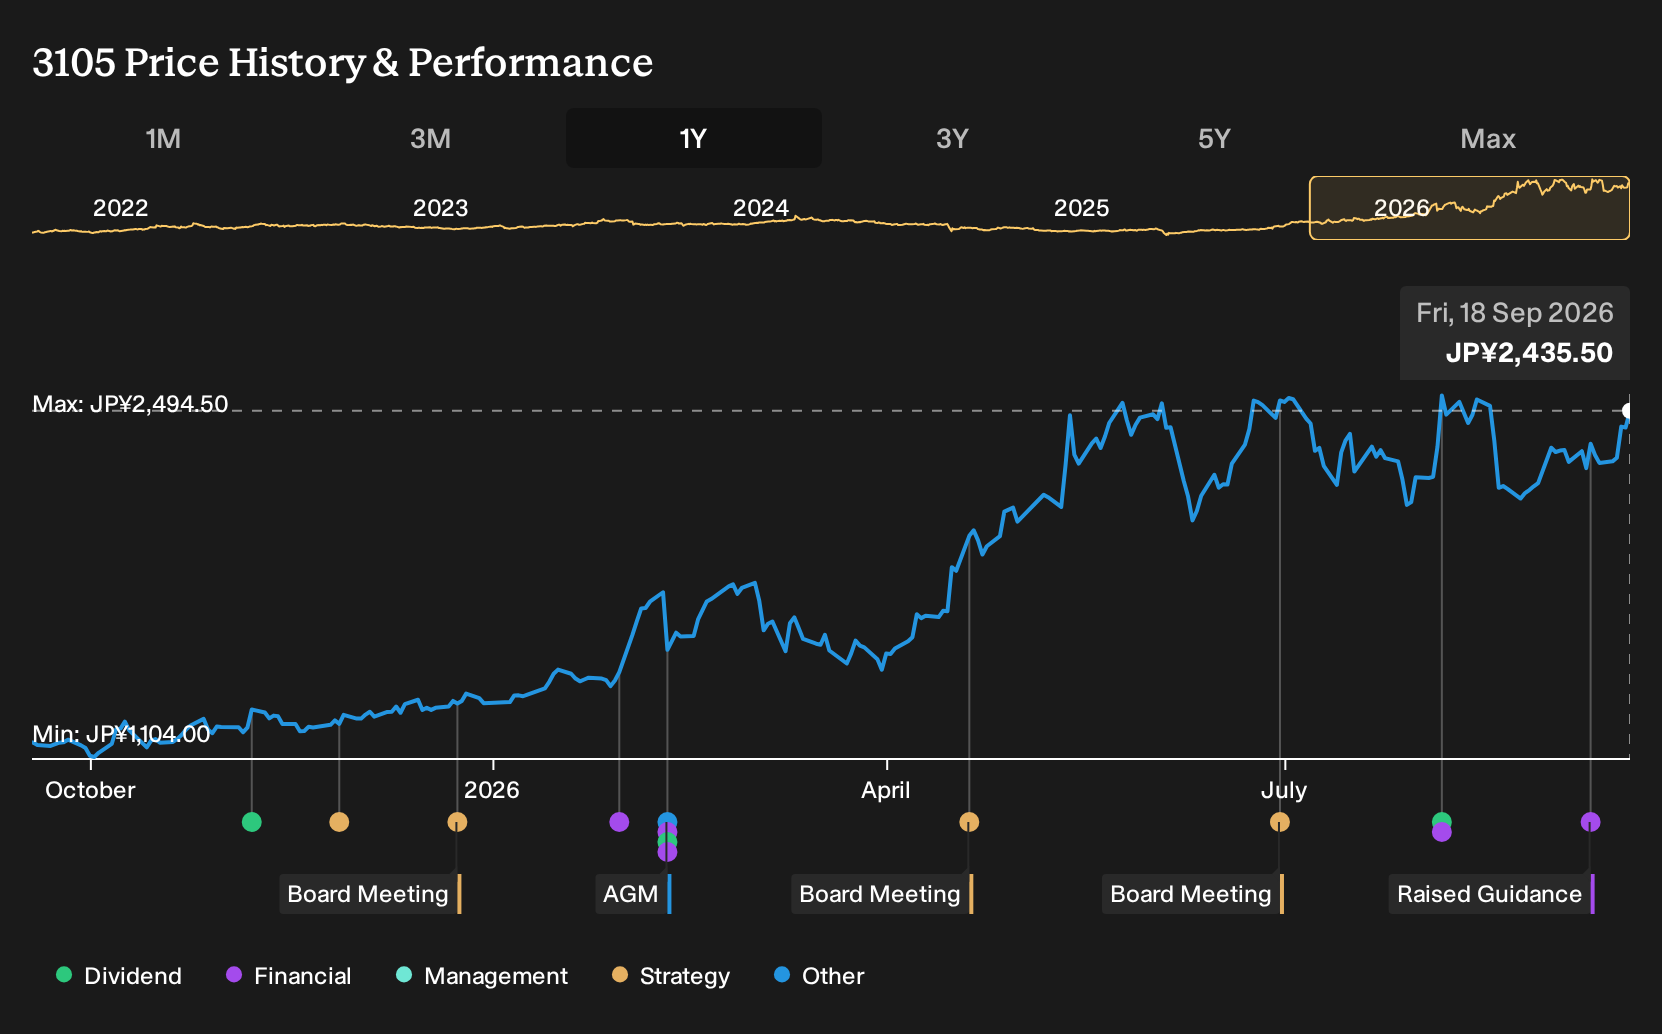
- Nisshinbo Holdings revised its 2026 full year forecast in September 2026, keeping net sales and operating profit targets unchanged while lifting profit attributable to owners of parent to ¥14,000 million and basic EPS to ¥89.61.
- The higher profit outlook rests mainly on an extraordinary ¥3,821 million gain from selling investment securities, which improves headline earnings without altering the core operating run rate.
- This article examines how Nisshinbo Holdings' investment narrative is influenced by this one off investment securities gain and the upgraded profit guidance.
What Is Nisshinbo Holdings' Investment Narrative?
To own Nisshinbo Holdings, you need to be comfortable with a diversified industrial group that earns its keep through execution in wireless communications, semiconductors, auto brakes, and a mix of niche materials and real estate. The raised 2026 profit guidance hinges on a ¥3,821 million extraordinary gain, so it lifts reported earnings without changing the operating targets for net sales or operating profit. That means the near term story still comes down to demand in core segments, pricing discipline, and how efficiently management runs this relatively capital intensive set of businesses.
In the short term, the catalyst is whether Nisshinbo Holdings can turn its forecast earnings growth into sustained cash generation while keeping Return on Equity, currently described as low at 7.4%, moving in the right direction. Forecast profit growth of 11.8% a year, higher than the broader JP market expectation of 8.8%, supports that narrative. However, slower expected revenue expansion of 3.5% a year points to a grind rather than a surge, which makes execution on margins, capital spending, and semiconductor cycle timing even more important.
Yet beneath the upbeat guidance and valuation support, there is a less comfortable wrinkle once you focus on ...
There's only one way to know the right time to buy, sell or hold Nisshinbo Holdings. Head to Simply Wall St's company report for the latest analysis of Nisshinbo Holdings's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Nisshinbo Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nisshinbo Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nisshinbo Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Nisshinbo Holdings?
After assessing how Nisshinbo Holdings' updated guidance fits your portfolio, it can help to scan a broader set of listed businesses that match your risk profile and return goals.
- For investors who want clear value with support from cash flows and balance sheets, review our 17 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and smoother portfolio swings matter most to you, consider stocks in the 21 resilient stocks with low risk scores that score well on resilience.
- For those who prefer robust finances and less fragile funding structures, check companies in the list of solid balance sheet and fundamentals (20 results) to see which ones fit your checklist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com