


Coca-Cola (KO) Stock Looks Fairly Priced After Its 89% Run
Coca-Cola has been a strong performer over the past few years, and the stock now trades with a long run of gains behind it. With that backdrop, the question is whether the current share price is still aligned with the cash flows the business is expected to generate.
- Over the past 5 years, Coca-Cola has delivered an 88.6% total return. This puts real pressure on investors to check whether the current valuation still lines up with the cash its business can produce.
- Planned US$10b of infrastructure investment in the United States by 2030 and the conditional approval for Coca-Cola HBC to expand into 14 new African markets may support expectations for future cash generation, but also shape the timing and scale of those cash flows.
- What if you looked at Coca-Cola through its earnings instead? See what Coca-Cola's 26.5x P/E says about the price.
The issue now is whether Coca-Cola's recent share price level can be justified by the cash flows implied by a Discounted Cash Flow (DCF) view over the coming years.
If you want a broader set of ideas alongside Coca-Cola while still focusing on valuation and balance sheet strength, a simple next step is to scan solid balance sheet and fundamentals stocks screener (23 results).
Is Coca-Cola Fairly Priced on Cash Flow?
The Discounted Cash Flow model values Coca-Cola by projecting the cash it can return to shareholders and then discounting those flows back to today. Coca-Cola is currently generating last twelve month free cash flow of about $14.2b. The DCF framework assumes this level of cash generation grows steadily rather than swinging sharply up or down.
Analysts expect Coca-Cola's free cash flow to edge higher over the coming decade, which broadly supports a valuation in line with the current share price of $88.06. The planned $10b US infrastructure spend by 2030, together with the expansion of Coca-Cola HBC into 14 new African markets, helps explain why the market is valuing those future cash flows roughly in line with the DCF output. Find out what Coca-Cola could be worth using our Discounted Cash Flow (DCF) estimate.
The Coca-Cola Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Coca-Cola valuation puzzle leaves off by spelling out what kind of path for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on the market. Each Narrative links a particular fair value estimate to a clear storyline about Coca-Cola's potential catalysts and key risks, so you can track over time which version of the future seems to be playing out. These sit on Simply Wall St's Community page and turn those assumptions into concrete scenarios you can monitor as new information arrives.
Community views on Coca-Cola are split between a modest upside story and a sharper concern that the current price already more than reflects the fundamentals.
Bull case: 7% undervalued
"The ramp-up of U.S. fairlife capacity in 2026 and strong performance in value-added dairy internationally positions Coca-Cola to capture more share of fast-growing, high-margin dairy and functional beverage segments..."
Discover why this Narrative puts Coca-Cola at 7% undervalued.
Bear case: 33% overvalued
"Current price appears fairly valued to slightly undervalued for patient investors which is a strong buy on dips below $78..."
Explore why this Narrative puts Coca-Cola at 33% overvalued.
Coca-Cola's valuation still leaves one key angle unresolved
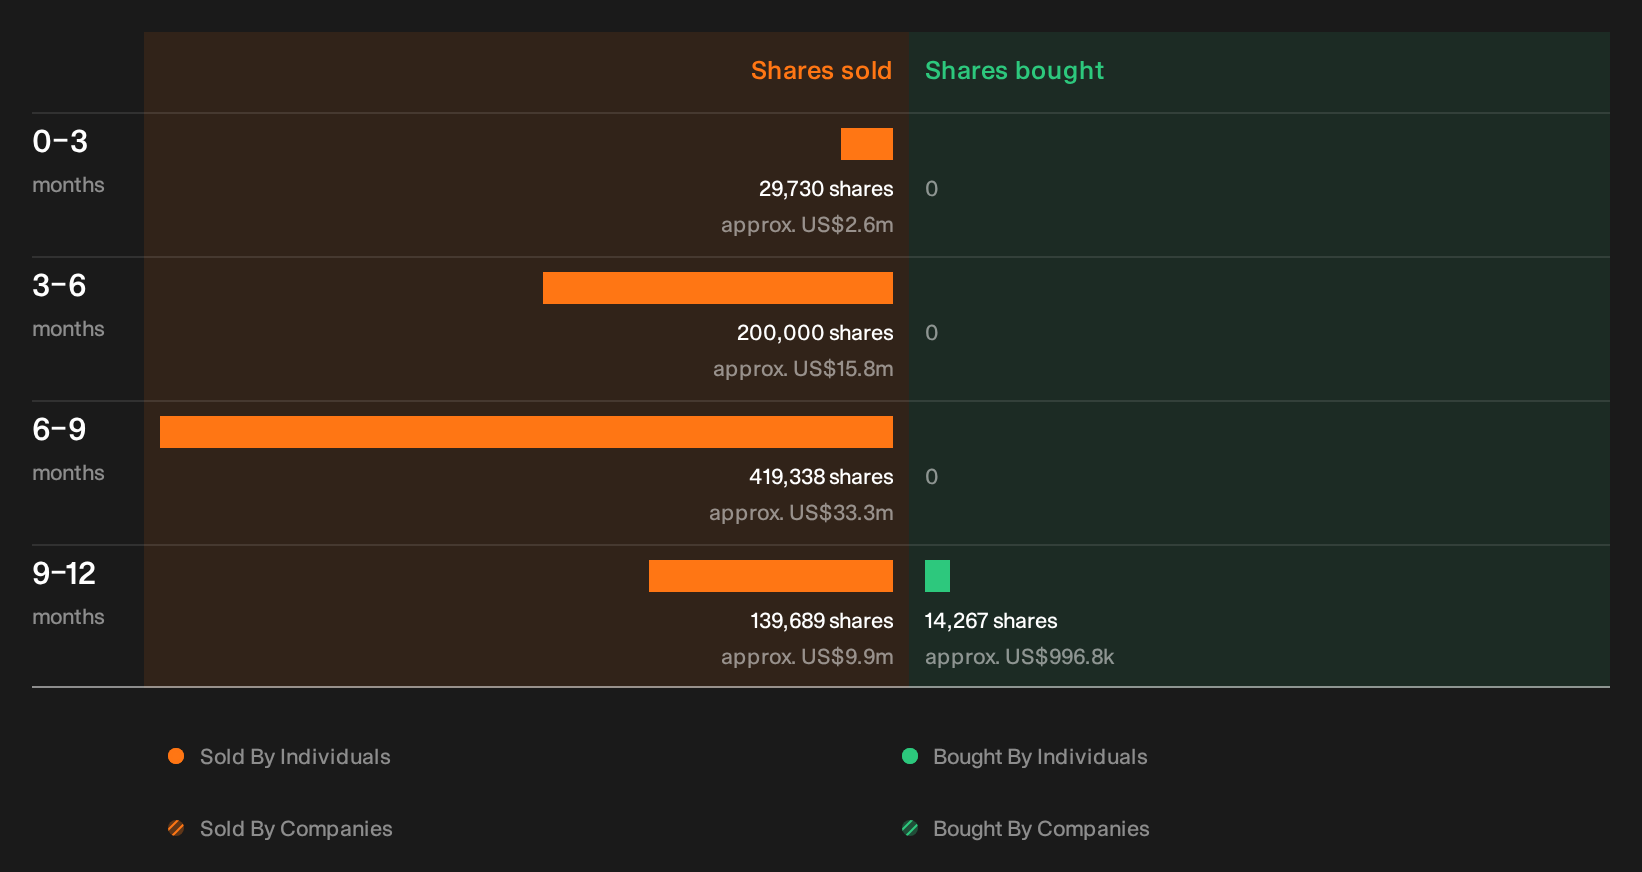
Price, cash flow and growth stories all paint part of the picture for Coca-Cola, but the recent trading activity by those closest to the business raises a separate question that deserves your attention. See the recent insider selling flagged for Coca-Cola.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com