


Is SBA Funding Approval Altering The Investment Case For Capital Southwest (CSWC)?
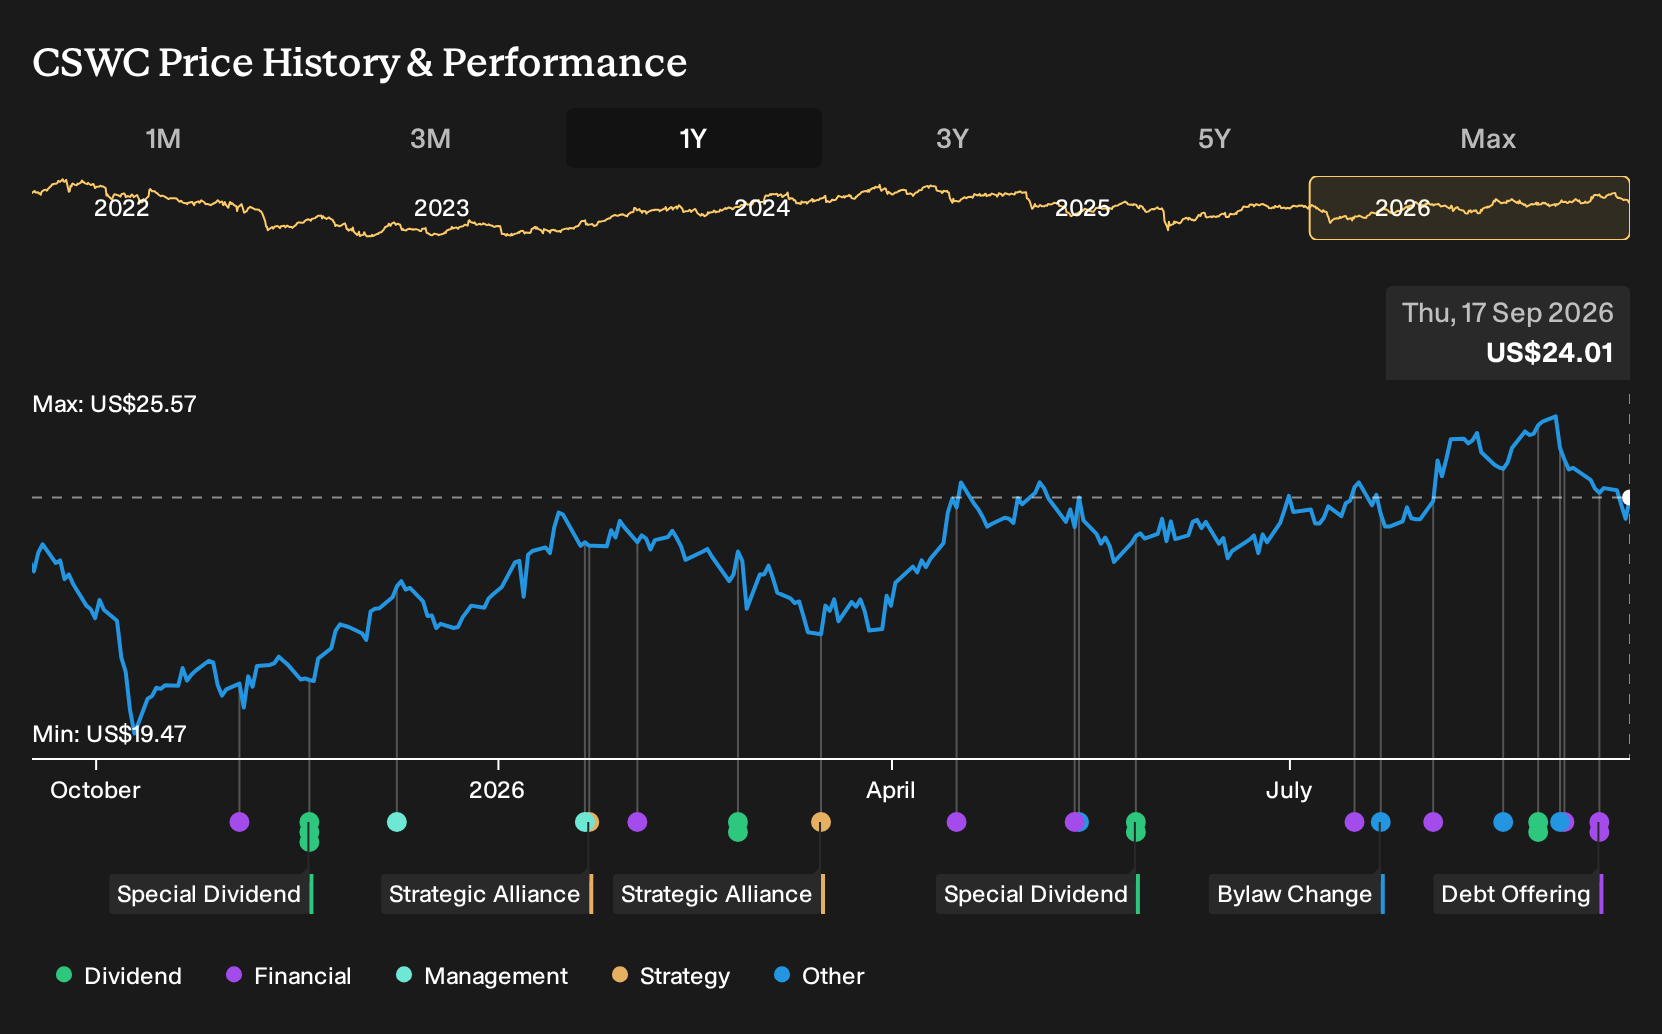
- Capital Southwest reported that the SBA approved an increase in SBIC II’s leverage commitment from US$175 million to US$250 million, expanding capacity to fund SBIC eligible lower middle market investments under existing underwriting and diversification standards.
- The larger SBIC commitment, together with SEC relief that excludes SBA guaranteed debentures from senior securities, reshapes how Capital Southwest can structure funding while staying within Investment Company Act asset coverage rules.
- Investors can now assess how Capital Southwest’s investment narrative may be influenced by the expanded SBA leverage capacity for its SBIC II vehicle.
Scan how Capital Southwest’s SBIC move fits into a wider opportunity set by comparing it with a hand picked 29 high quality undervalued stocks that also pair balance sheet strength with disciplined lending models.
Capital Southwest Investment Narrative Recap
To own Capital Southwest, you need to be comfortable with a lower middle market lender that leans on first lien credit, equity co investments and a relatively high payout. The expanded SBA leverage commitment matters mainly if management can keep credit quality and diversification intact while putting more SBIC capital to work without compressing returns.
The near term swing factor still looks like loan yields versus funding costs as competition pushes on spreads and interest expense stays meaningful. The biggest risk is that generous dividends and interest obligations outstrip cash earnings if deal activity slows or equity gains soften, regardless of how much extra SBIC capacity is available.
The recent 6.750% notes due 2031 fit directly into this picture. You now have a lender with more SBIC borrowing headroom and a sizeable new unsecured bond, so the mix and cost of liabilities matter even more for interest coverage and net investment income resilience.
For you as a shareholder, the key question is whether Capital Southwest can use the SBA facility and the new notes to scale its lower middle market portfolio while holding underwriting discipline. Execution on credit selection, fee income and non cash earnings quality will likely drive how sustainable the current dividend profile really is.
Capital Southwest's narrative projects US$308.9 million in revenue and US$175.1 million in earnings by 2029, based on analyst consensus. This implies 10.0% yearly revenue growth and an earnings increase of about US$63.3 million from US$111.8 million today.
Discover how Capital Southwest's fair value indicates a 4% potential upside to its current price before the discount to Capital Southwest closes.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between US$24.90 and about US$29.74, so even this small sample shows a wide personal range. Set these views against risks like spread compression, equity dilution and the new 6.750% notes, then explore how different investors frame Capital Southwest’s prospects.
Explore another Capital Southwest fair value estimate, including one that indicates as much as 24% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so rely on your own judgment.
- A great starting point for your Capital Southwest research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Southwest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Southwest's overall financial health at a glance.
Looking For More Ideas Beyond Capital Southwest?
If you want to sanity check your view on Capital Southwest against a wider field, the Simply Wall St Screener lets you line up other businesses with different risk and income profiles and see what really earns a spot on your watchlist.
- If capital preservation comes first for you, scan a 30 resilient stocks with low risk scores that score well on resilience so you can focus on steadier return profiles.
- If income is the main objective, compare Capital Southwest with a curated 6 dividend fortresses designed for investors who want higher yields backed by underlying fundamentals.
- If you prefer to hunt for mispriced opportunities, sort through a 16 high quality undiscovered gems that combine quality metrics with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com