


Bullish (BLSH) Stock May Still Look Overvalued On Its Sales Story
Bullish has seen its share price swing sharply in recent months, and the question now is whether the current US$34.91 level lines up with the sales the business is generating. For anyone tracking the stock, the key issue is how that price stacks up against what investors are paying for Bullish's revenue today.
- Over the past year the share price has fallen 46.8%, which puts the focus squarely on whether the revenue base can support even the current valuation.
- The business model leans on its ability to convert trading activity into fee income, which can shape how much investors are prepared to pay for each dollar of Bullish's sales.
- The analysts covering Bullish have run their own numbers. See what analysts think Bullish's shares could be worth.
The stock's next move may depend on whether Bullish's sales justify the price investors are currently asked to pay.
If you are weighing Bullish against other options where the focus is on valuation and quality, a good next step is to scan 29 high quality undervalued stocks as another research starting point.
Does Bullish Look Pricey on Sales?
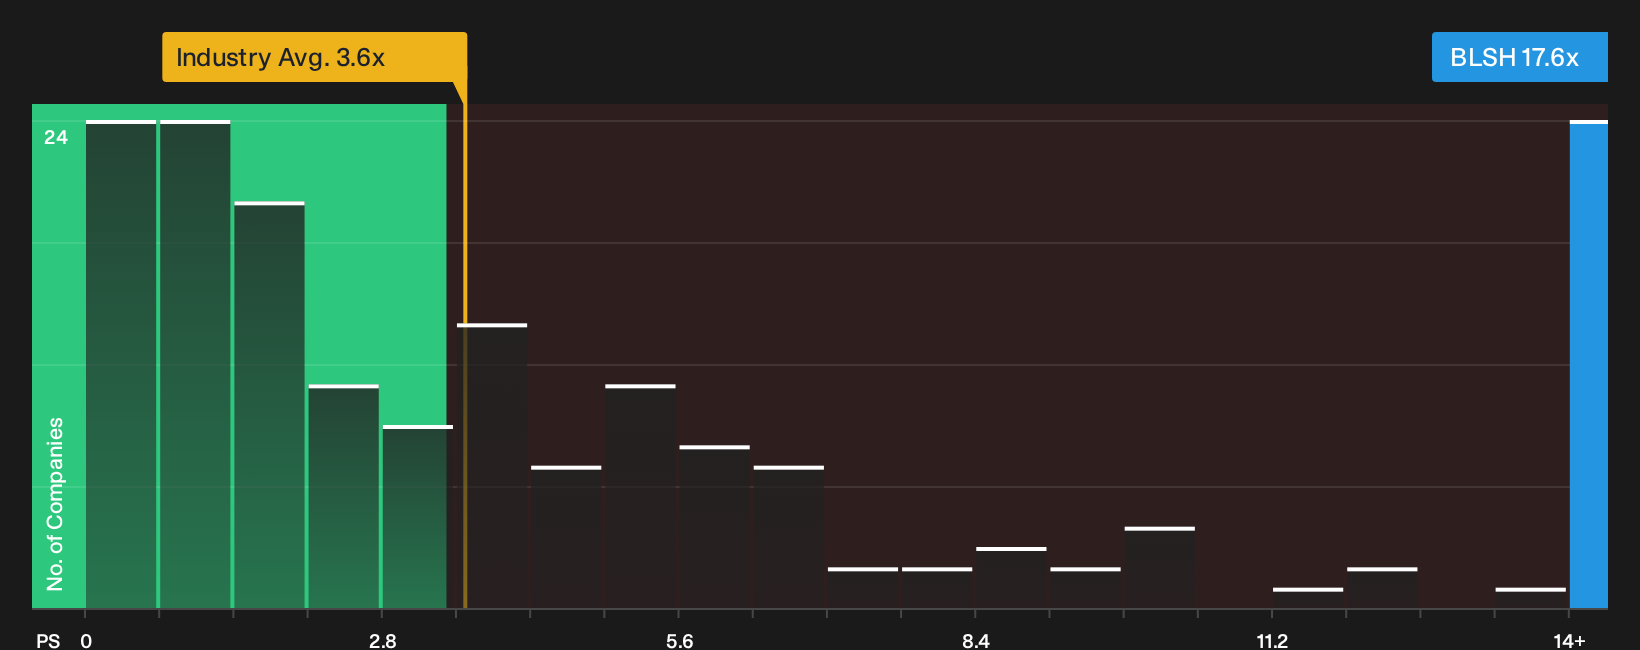
P/S is a useful lens for Bullish because investors are mainly paying for its ability to turn trading activity into fee revenue rather than steady earnings. On this measure, the stock trades on a P/S of 17.6x, while the broader Capital Markets industry sits at around 3.6x and close peers cluster near 4.0x. That is a very large gap between what the market currently pays for each dollar of Bullish's sales and what it pays for similar businesses in the sector.
A more tailored fair multiple for Bullish, which factors in its profitability profile, size and risk, lands materially lower than the price the market is assigning to the shares. The model is heavily penalising the company for its earnings track record and risk profile, so the result is better read as a strong warning that Bullish looks overvalued on this framework rather than a precise target number. For anyone considering the stock, the key question is whether the quality and durability of Bullish's revenue stream genuinely merit paying such a rich P/S tag. Explore the numbers behind Bullish's P/S valuation.
The Bullish Narrative: What Would Justify Today's Price?
Narratives on Bullish pick up where the valuation puzzle leaves off. They spell out what sort of future for revenue growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price, and each scenario links a fair value to a specific mix of potential catalysts and risks so you can track over time which storyline about Bullish's business is actually unfolding.
A clear, number-driven narrative on Bullish puts concrete assumptions around revenue, margins and execution on the table so you are not just reacting to the P/S headline. It also gives you a framework you can revisit as quarterly results and trading updates arrive. This makes it easier to judge whether Bullish's actual progress still lines up with the story you are betting on.
Share your own Narrative for Bullish and set out the assumptions behind your valuation.
Before you act on Bullish's valuation, one more piece of the puzzle matters
The checklist on Bullish has also picked up specific concerns that sit outside the sales multiple debate, and those issues can change how you frame the whole opportunity. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com