


Why Everyone Is Watching Dynatrace (DT) Today
Sopra Steria’s new observability and AIOps practice with Dynatrace (DT) puts the software group in front of large European enterprises, just as Pictet Asset Management begins active governance engagement.
Dynatrace’s recent announcements come after a strong run in the share price, with a 33.24% 3 month share price return and a 30.32% year to date move. Longer term, total shareholder returns of 19.33% over three years and a 14.84% 1 year figure point to momentum that investors are now reassessing in light of fresh partnerships and active governance engagement.
Scan how Dynatrace compares with other observability and AI software plays by reviewing our hand-picked 60 AI infrastructure stocks, which now feeds enterprise demand for always-on, compliant digital operations.
After a move like Dynatrace has just logged, the debate sharpens fast. Is the recent rally already pricing in the Sopra Steria tie-up and Pictet’s engagement, or does the valuation still leave meaningful upside on the table?
Most Popular Narrative: 5.1% Undervalued
Against Dynatrace’s last close at $55.19, the most followed narrative pegs fair value at about $58.18. The story leans modestly positive while still asking whether AI observability and buybacks can sustain that gap.
The company's unified platform approach, particularly the growing success of Grail-powered log management (over 100% YoY log consumption growth and targeting $100M in annualized consumption), is driving multi-product adoption and higher customer stickiness, which should improve net retention rates, recurring revenue, and long-term earnings predictability.
See why 52 investors see Dynatrace as 5% undervalued.
Result: Fair Value of $58.18 (UNDERVALUED)
Still, the bullish Dynatrace story can unwind quickly if hyperscalers and open source tools apply pricing pressure, or if larger, slower enterprise deals slip or disappear.
Find out about the key risks to this Dynatrace narrative.
Another View on Dynatrace’s Valuation
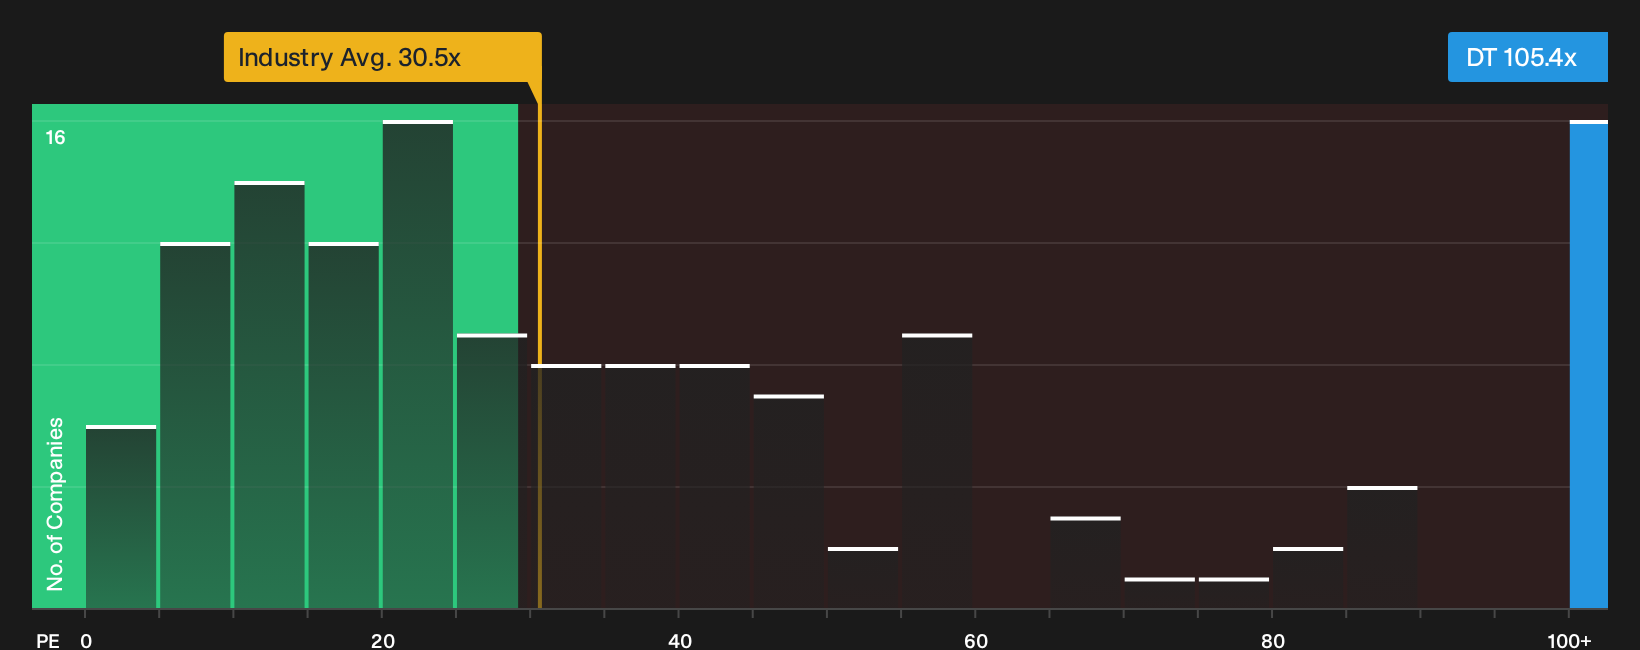
The fair value story so far leans on cash flow and analyst assumptions, yet the market is also putting a heavy P/E tag on Dynatrace. The stock trades on about 105.4x earnings, while the fair ratio is 37.4x, the US Software group sits near 30.5x, and peers are around 38.5x. That is a wide valuation gap, so how comfortable are you paying growth prices that far above what the ratio could move toward over time?
To see how those earnings multiples line up against the rest of the sector in hard numbers, take a look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether Dynatrace’s current optimism really balances the concerns raised through recent engagement and valuation checks? Act quickly and weigh both sides by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Dynatrace style investment ideas?
If Dynatrace has sharpened your appetite for higher quality opportunities, do not stop with one ticker. Broader idea flow can support more informed portfolio decisions.
- Target durable cash generators by scanning our 6 dividend fortresses that focus on payout strength with resilience front of mind.
- Look for potential pricing inefficiencies across the market using our curated 16 high quality undiscovered gems before they attract wider attention.
- Emphasise risk awareness by reviewing a 11 resilient stocks with low risk scores that concentrates on businesses with sturdier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com