


Empire State Realty OP (ESBA) Could Be 69% Undervalued On A Weak Share Price Run
Empire State Realty OP (ESBA) has drawn attention after recent trading left the units about 34% below their intrinsic estimate, with the price last closing at US$4.14.
Over the past year, Empire State Realty OP has seen share price momentum cool. The 1-year total shareholder return has declined 43.35%, and the year-to-date share price return is down 33.76%. Shorter-term performance has also weakened, including an 18.18% decline over 90 days and an 8.41% fall over the last month.
Spot potential REIT rebounds by scanning a curated pool of 33 high quality undervalued stocks that, like Empire State Realty OP, currently trade at steep discounts to their estimated worth.That kind of slide can reset expectations fast. For Empire State Realty OP, currently reported at a 69% discount to intrinsic value, does the balance of risk and potential reward still lean toward buyers?
Preferred Price-to-Sales of 1.5x: Is it justified?
On a simple yardstick, Empire State Realty OP trades on a P/S ratio of 1.5x, which screens as inexpensive against peers at the last close of $4.14.
The P/S ratio compares the market value of the equity with the revenue the partnership generates, so it is often used for real estate businesses where earnings can be noisy. For Empire State Realty OP, that noise is clear, with a reported net profit margin of 0.6% compared with 8.5% a year earlier and large one off items affecting results, which makes revenue based valuation a practical cross check.
Context matters. ESBA is described as trading 69.2% below an internal fair value estimate and is considered undervalued by the SWS DCF model. At the same time, its 1.5x P/S looks inexpensive versus both a 4x peer average and a 3.6x North American REIT industry average. This combination points to a market that is pricing the partnership far more cautiously than its sector, even though the preferred multiple is already well below typical levels.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 1.5x (UNDERVALUED)
Still, Empire State Realty OP faces pressure from weak multi year total returns and a slim profit of US$5.06m on revenue of US$782.82m.
Find out about the key risks to this Empire State Realty OP narrative.
Another View on Empire State Realty OP’s Value
There is a very different signal coming from the SWS DCF model. On that framework, Empire State Realty OP at $4.14 is compared with an estimated future cash flow value of $13.45, which points to a wide undervaluation. If public markets are this far below that cash flow view, how much risk are investors really taking, versus the potential upside implied by that gap?
Look into how the SWS DCF model arrives at its fair value.
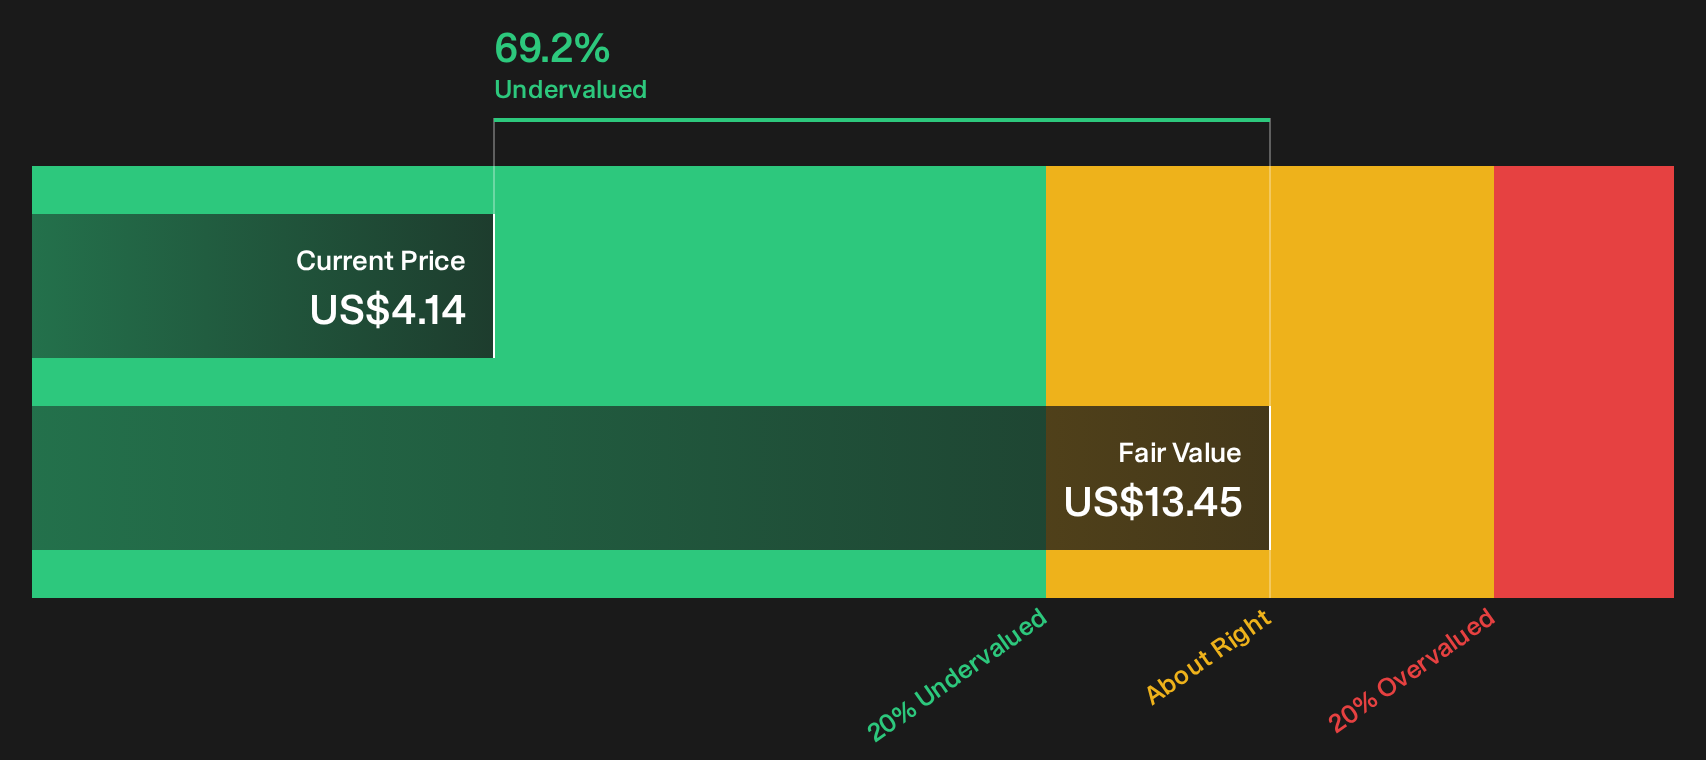
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Empire State Realty OP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Empire State Realty OP can feel confusing, so treat this as a prompt to move fast, pull up the numbers and pressure test the story yourself. To weigh the balance of concern against optimism, start by breaking down the 1 key reward and 4 important warning signs
Looking for more Empire State Realty OP style ideas?
If Empire State Realty OP has you rethinking value, do not stop there. Broaden your watchlist with a few focused screens that surface different types of opportunities.
- Target quality at a discount by scanning a curated pool of 33 high quality undervalued stocks that combine lower prices with stronger fundamentals than the broader market.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (22 results) so you can focus on businesses that rely less on heavy borrowing to fund operations.
- Get ahead of the crowd by hunting through 16 high quality undiscovered gems before attention turns their way and the most obvious mispricings close.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com