


SL Green Realty (SLG) Leased 1.8 Million Square Feet In Manhattan For 2026
- SL Green Realty (NYSE: SLG) reported nearly 1.8 million square feet of Manhattan office leases for 2026 at higher rental rates.
- Management highlighted a strong forward leasing pipeline, with a mix of new and renewal deals across key Midtown and Downtown assets.
- High profile tenants committed to multi year agreements, reinforcing occupancy across several of SL Green's flagship Manhattan properties.
- SL Green's 2026 Manhattan office leasing milestone with higher rents is worth weighing alongside the rest of our findings. We have also spotted 3 warning signs (1 major) worth knowing about at SL Green Realty.
You can also explore other office focused stocks that appear more resilient on several risk measures through 11 resilient stocks with low risk scores.
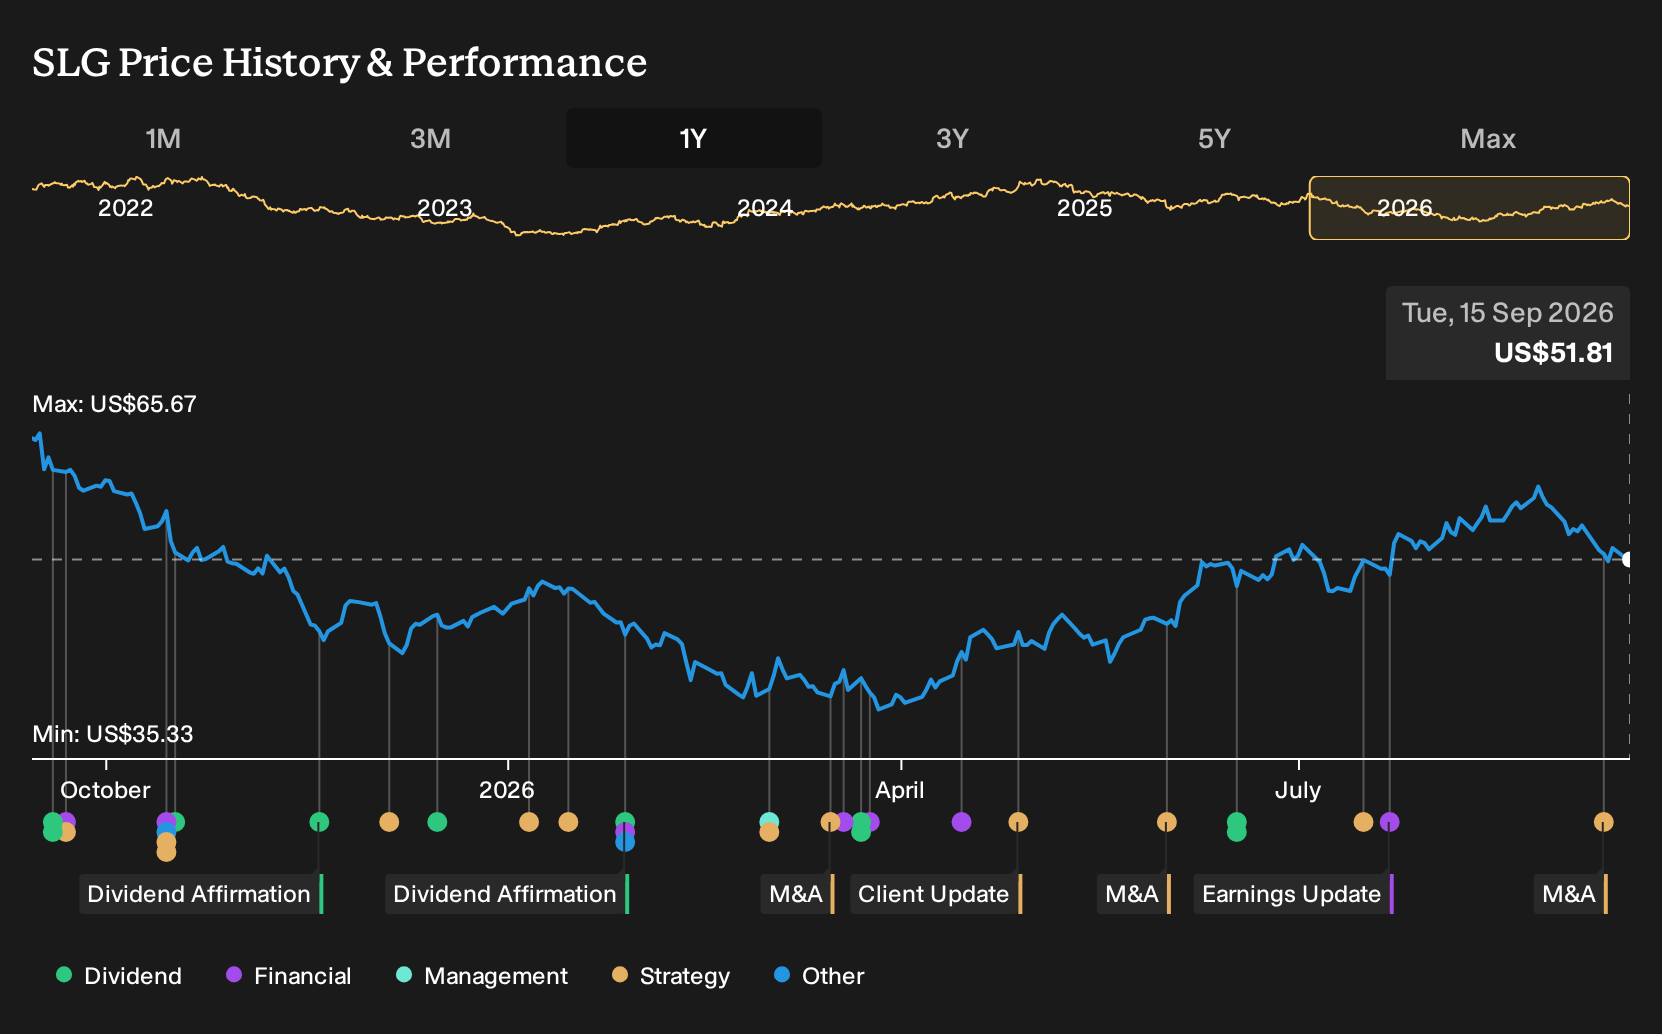
SL Green Realty is a US based office REIT with a $4.0b market cap that focuses on acquiring, operating and improving commercial properties across Manhattan. Leasing traction like this sits directly in the middle of how the portfolio is run and monetised.
See which insiders are buying and selling SL Green Realty following this latest news.
How SL Green’s 2026 leasing surge tilts the bull and bear story
SL Green Realty’s Narrative asks investors to decide whether high quality Manhattan assets can turn strong tenant demand into steadier cash flows in the face of heavy interest costs. This 2026 leasing update goes straight to that tension between premium buildings and a stretched balance sheet.
"The company is poised to benefit from renewed and expanding tenant demand for high-quality office space in key Manhattan corridors, with evidence of diverse industries... "
See how the full story points towards a $56.00 fair value for SL Green Realty.
The 1.76 million square feet of 2026 leases at 15.8% higher rents directly supports the bull case that SL Green can keep capturing premium pricing in a tight Manhattan market. For investors comparing it with office owners like Vornado or Boston Properties, this kind of rent reset helps the story around higher net operating margins and demand for top tier towers.
The bear case has never been about leasing headlines. It is about whether that rental strength arrives fast enough to offset interest payments that analysts already flag as poorly covered. A pipeline of more than 1.0 million square feet helps sentiment on occupancy, but it does not resolve risks around refinancing, complex investment income or future move outs.
The real signal here only matters relative to which Narrative you believe: a premium Manhattan leasing story overcoming funding pressure, or a debt burden that keeps the upside on a short leash.
Add SL Green Realty to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com