


Is Assurant (AIZ) A Bargain After Its Recent Run Up?
Assurant (AIZ) is back in focus after recent trading left the stock at about $286.11. This has drawn attention to how its insurance mix and global footprint might be shaping current market expectations.
Recent gains have been steady rather than flashy, with a 9.15% 90 day share price return feeding into a 20.36% year to date move. Assurant’s 1 year total shareholder return of 41.29% and 3 year total shareholder return of 112.85% point to momentum that long term holders have already felt.
Scan for other insurers showing similar momentum to Assurant by checking our curated list of 11 resilient stocks with low risk scores that combine resilient balance sheets with consistent shareholder returns.
Assurant’s recent climb invites a basic question. Are investors reacting to sturdier protection earnings and a broad international footprint, or has sentiment simply warmed faster than the underlying business justifies on valuation metrics?
Most Popular Narrative: 13% Undervalued
Based on the most followed narrative, Assurant’s fair value of $330 sits above the recent $286.11 close. This puts the focus squarely on how durable its earnings drivers really are.
Assurant is capitalizing on the proliferation of connected devices and increasing device protection needs, demonstrated by 2.4 million net new device protection subscribers, international acquisitions expanding repair capabilities, and strong new partnerships, which positions the company for sustained revenue growth and improved recurring earnings in its Lifestyle segment.
See why 7 investors see Assurant as 13% undervalued.
Result: Fair Value of $330 (UNDERVALUED)
Still, if lender placed products face tougher regulation or big tech pushes deeper into device protection, the upbeat Assurant narrative could be knocked off course.
Find out about the key risks to this Assurant narrative.
Another View on Assurant’s Valuation
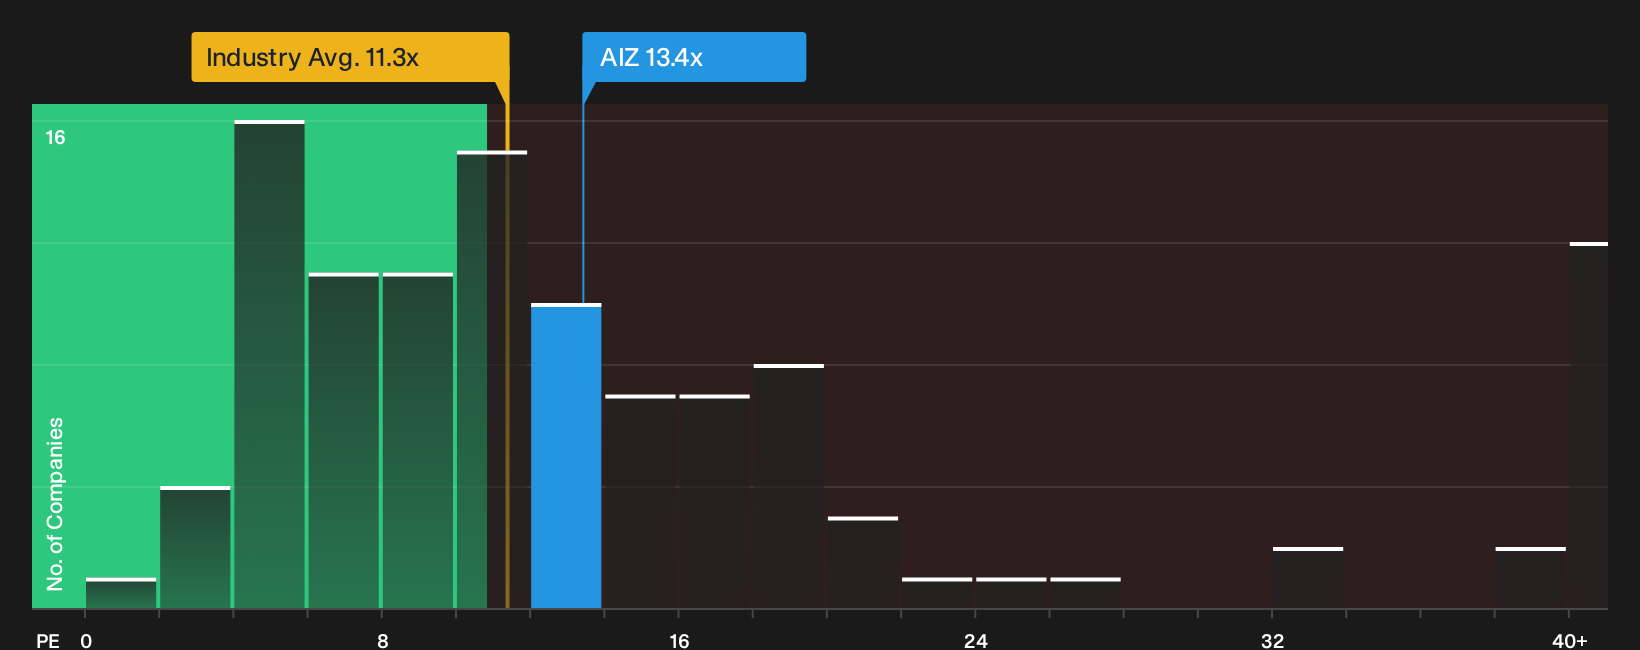
That 13% undervalued story for Assurant does not line up neatly with how the current P/E looks. The stock trades on about 13.4x earnings, which is above the US Insurance sector at 11.4x, yet also below peers at 15.2x and above a fair ratio of 11.7x. That mix points to both room for optimism and some valuation risk. Which reference point matters most for you?
See what the numbers say about this price in our valuation breakdown, then weigh that against your own expectations for Assurant’s earnings power over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Assurant’s story so far. Act while sentiment is fresh by checking the data for yourself and weighing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Assurant?
If Assurant has sharpened your focus on valuations and quality, expand your watchlist with a few targeted stock ideas sourced directly from the Simply Wall St screener.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (22 results) that can help anchor your portfolio when markets get noisy.
- Hunt for potential mispricings by reviewing a 34 high quality undervalued stocks that may line up better with your return and risk expectations.
- Stack your income potential by checking a 6 dividend fortresses that aim to combine higher yields with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com