


Cohen & Steers (CNS) Pulls Back On ETF And Expansion Hopes While Valuation Stays In Focus
Cohen & Steers (CNS) shares closed at US$72.34 on 15 September 2026 after a recent pullback, with the stock down about 14.6% over the past month and 2.7% over the past 3 months.
For context, Cohen & Steers has a year to date share price return of 13.8%. However, the recent 7 day and 30 day share price declines of 7.5% and 14.6% show momentum fading in the short term, even as the 1 year total shareholder return sits at 8.2%.
Scan how Cohen & Steers compares with other asset managers reacting to similar sentiment shifts by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) in this space.
Cohen & Steers looks like a solid specialist in real assets after years of measured growth, yet the recent double digit pullback raises a sharper question: Is this quality franchise still being priced as one?
Most Popular Narrative: 3.5% Undervalued
Cohen & Steers last traded at $72.34 while the most followed valuation story pegs fair value at about $75. That small gap puts the recent pullback in a different light, because the narrative leans on earnings quality and balance between growth plans and real asset exposure.
Strategic expansion into active ETFs and broader product diversification (including the launch of integrated listed/private real estate strategies) is expected to attract new investor segments and improve client retention, supporting future AUM growth and revenue stability.
Ongoing investments in global distribution, particularly in Asia-Pacific and Europe, and recent foreign office upgrades are expected to drive international client inflows and scale, with potential for margin expansion as global business grows.
See why 4 investors see Cohen & Steers as 4% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, the Cohen & Steers story can crack if institutional outflows persist or if higher distribution and product costs keep squeezing profitability, despite the current real assets focus.
Find out about the key risks to this Cohen & Steers narrative.
Another View: What Cohen & Steers’ P/E Is Really Saying
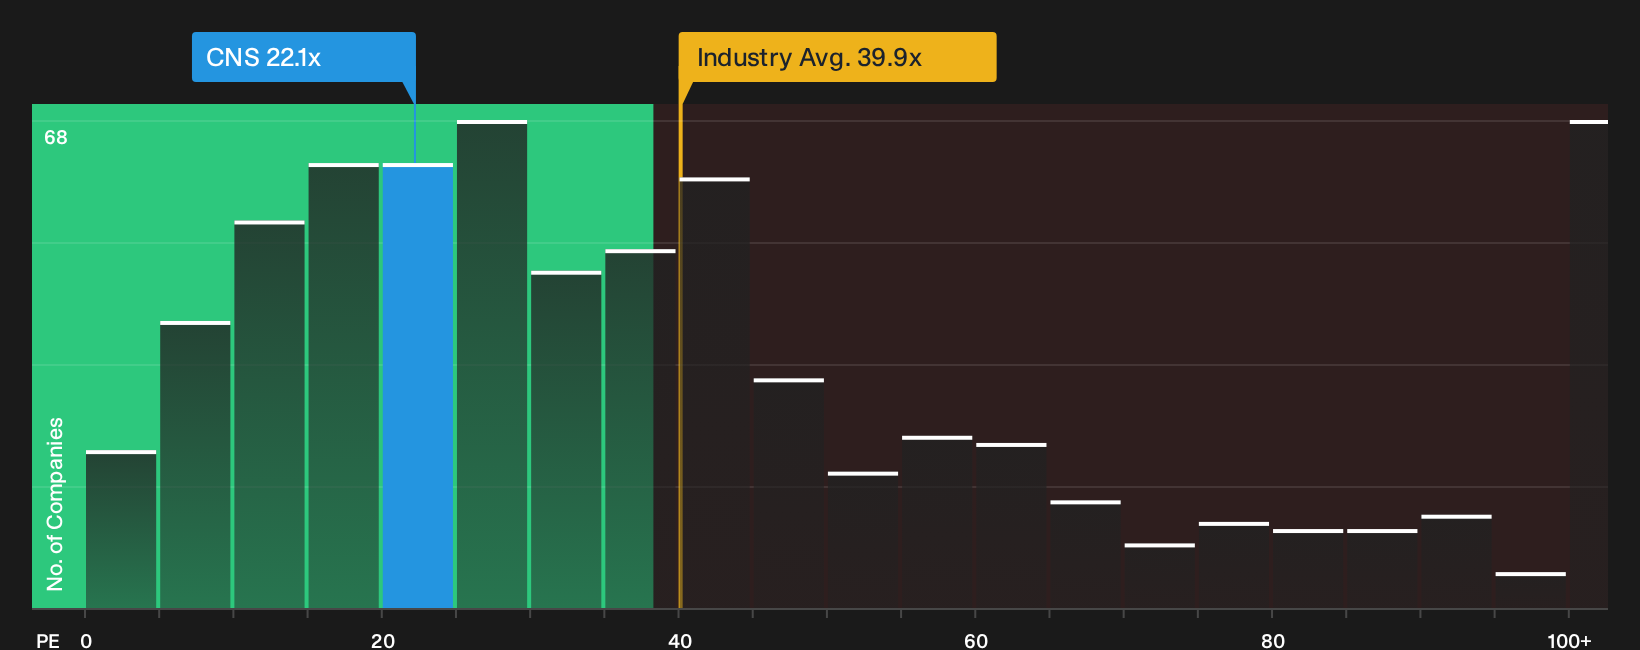
The DCF style fair value story points to about 3.5% undervaluation, yet the simple earnings multiple paints a tougher picture. Cohen & Steers trades on a P/E of 22.1x, while the fair ratio sits at 12.6x and peers average 9.8x. That gap suggests investors today are paying a premium that could just as easily compress as hold. Which version of “fair” do you trust more right now?
For a closer look at how this earnings based premium stacks up against broader market data, including the Capital Markets industry at 39.6x, it is worth digging into the valuation breakdown in more detail, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Cohen & Steers so far. If you care about weighing both the upside and the red flags, you will want to see the 2 key rewards and 3 important warning signs.
Looking for more Cohen & Steers style investment ideas?
If Cohen & Steers has you thinking harder about valuation, risk and income, now is the moment to widen your watchlist before the next move starts.
- Target resilient balance sheets and consistent fundamentals by scanning the list of solid balance sheet and fundamentals (22 results) that filters for financially robust businesses.
- Hunt for quality trading at appealing prices through the 34 high quality undervalued stocks that spotlights stronger fundamentals than the share price suggests.
- Build a cash flow focused portfolio using the 6 dividend fortresses featuring higher yield candidates designed for income driven investors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com