


3 Life Insurance Stocks Worth Watching As Bond Yields Stay Higher For Longer
Government bond yields are no longer just background noise. They are reshaping what investors are willing to pay for future earnings and putting long duration growth stories under real scrutiny. That same move in rates can reshape the risk and reward profile for certain life insurers and annuity providers. This article unpacks the rate backdrop and reveals three stocks exposed to this story, helping you decide whether they deserve a closer look.
The stocks covered below are just a small sample of the idea. The full screen surfaced 15 more life insurers and annuity providers with equally compelling stories that are not included here.
If you want to quickly identify which life insurance and annuity businesses best fit your own rate view and risk profile, head straight to the Global Life Insurers and Annuity Providers Benefiting from Higher-for-Longer Yields screener to filter, analyze, and focus on your highest conviction candidates.
Daiichi Life Group (TSE:8750)
Daiichi Life Group is one of the clearest examples of how a large life insurer with sizeable bond portfolios can turn higher-for-longer yields into a funding advantage for long term savings products.
Daiichi Life Group generates most of its revenue from its Domestic Insurance Business at ¥9,286.7b, with ¥3,681.4b from Overseas Insurance and ¥617.4b from Other Business, supported by a sizeable ¥6,824.4b market cap.
"The company's strategic shift toward asset management and alternative investments, along with improving fixed income yields from portfolio rebalancing, is expected to enhance investment spreads and recurring income, benefiting net margins and long-term profitability."
What really moves the needle for Daiichi Life Group now is how a single pressure on long duration liabilities ultimately feeds through to those margins.
That margin story is only part of it, and the full narrative for Daiichi Life Group examines how rate moves, asset mix shifts, and product design could be quietly reshaping Daiichi Life Group.

Legal & General Group (LSE:LGEN)
Legal & General Group is a key player in the higher for longer yields theme, since its bulk annuities and retirement products are tightly linked to the returns it can earn on long dated bonds in the UK and beyond.
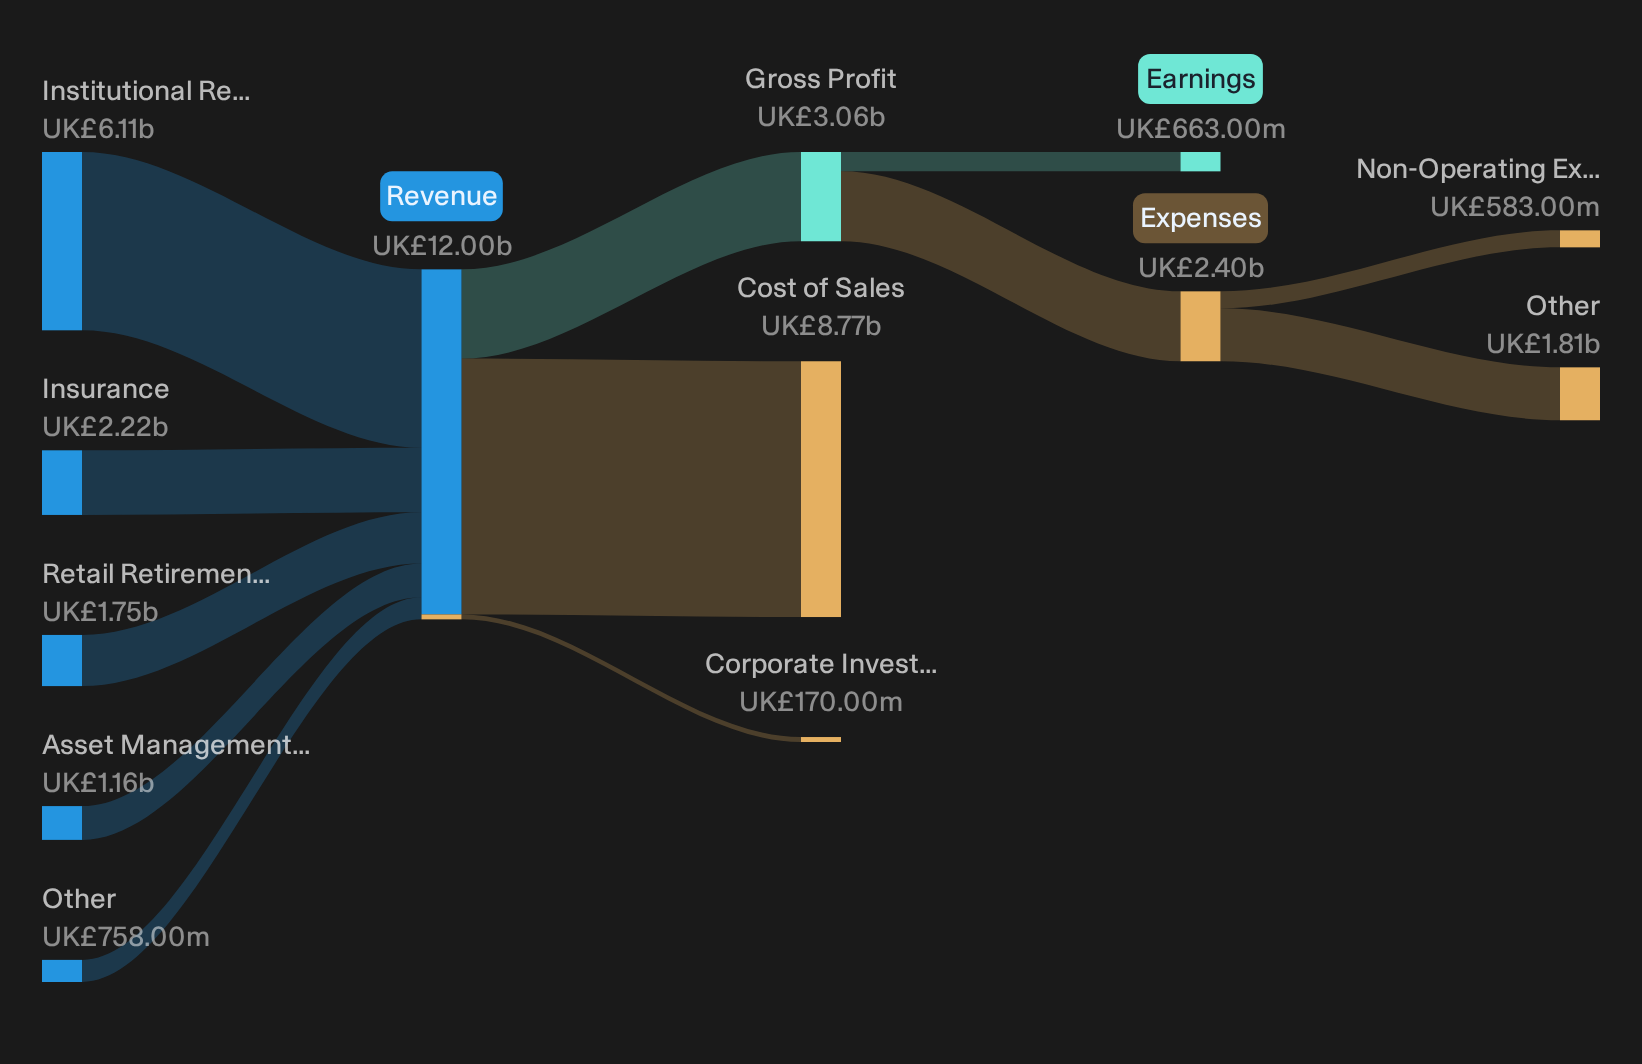
Legal & General Group runs a broad retirement and investment platform, with £6.1b revenue from Institutional Retirement, £2.2b from Insurance, £1.8b from Retail Retirement and £1.2b from Asset Management, underpinned by a market value of about £15.9b.
"Ongoing demographic shifts, especially ageing populations in the UK and developed markets, continue to drive strong structural demand for Legal & General's retirement solutions and bulk annuities. With a robust £42bn pipeline and expectations for the market beyond 2028, this supports predictable, long-term patterns in revenue and core operating profits."
What really matters next is how one subtle shift in the balance between funding costs and guaranteed payouts shapes those future margins.
When that funding and payout balance starts to shift, the full narrative for Legal & General Group shows how Legal & General Group’s margin story could be quietly accelerating.
Standard Life (LSE:SDLF)
Standard Life is closely aligned with the higher for longer yields theme because its long term retirement and annuity promises rely on reinvesting premiums into bond portfolios, where sustained higher coupons can significantly influence future earnings quality.
Standard Life focuses on long term savings and pensions across Retirement Solutions, Pensions & Savings, With Profits, and Europe & Other segments, with £2.7b reported from Retirement Solutions against losses in other units, and a market value of about £9.3b.
"The planned increase in IFRS operating profit target from £900 million to £1.1 billion by 2026, driven by a cost-saving strategy and expanding revenue from underlying businesses, supports optimism in improving earnings growth."
An important question is what happens to margins if pressure on funding costs and long dated asset spreads develops differently from what management is planning for.
If that funding pressure intrigues you, the full narrative for Standard Life explains how Standard Life’s earnings path could be quietly moving away from headline profit targets.

Seeking Alternatives Beyond Life Insurers?
Fresh ideas move first. By the time every chart shows momentum and headlines shout breakout, the early entry window is already dropping. Scan what is flying under the radar for now and get in early.
- Spot future dividend workhorses before yield chasers pile in by scanning the 16 dividend fortresses built to highlight income ideas that still look underappreciated.
- Track real businesses in AI, not just hype, using the curated 76 profitable AI stocks that aren't just burning cash to focus on companies already turning algorithms and infrastructure into cash flows.
- Hunt for pricing power and balance sheet strength with the carefully filtered list of solid balance sheet and fundamentals (20 results) so you are not caught holding fragile stories when momentum cools.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com