


Yü Group And 2 Other Undiscovered Gems With Promising Potential
The United Kingdom's market landscape has recently been influenced by global economic pressures, with the FTSE 100 and FTSE 250 experiencing declines amid weak trade data from China, highlighting vulnerabilities tied to international demand. Despite these challenges, the search for promising small-cap stocks remains crucial as investors look for opportunities that can thrive in uncertain conditions. In this article, we explore three such companies—Yü Group and two other undiscovered gems—that may offer potential value due to their unique positioning and growth strategies within this complex environment.
Top 10 Undiscovered Gems With Strong Fundamentals In The United Kingdom
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Serabi Gold | NA | 22.72% | 54.70% | ★★★★★★ |
| AltynGold | 27.47% | 28.92% | 35.78% | ★★★★★★ |
| Integrated Diagnostics Holdings | 7.96% | 15.27% | 4.96% | ★★★★★☆ |
| Yü Group | 10.53% | 36.12% | 50.56% | ★★★★★☆ |
| LSL Property Services | 39.76% | -14.51% | -16.54% | ★★★★★☆ |
| PayPoint | 182.83% | 21.49% | 0.42% | ★★★★★☆ |
| Pinewood Technologies Group | 0.10% | -49.74% | -0.64% | ★★★★★☆ |
| Halyk Bank of Kazakhstan | 71.22% | 19.19% | 19.30% | ★★★★☆☆ |
| Distribution Finance Capital Holdings | 15.26% | 36.11% | 48.64% | ★★★★☆☆ |
| ASA International Group | 219.68% | 17.56% | 44.83% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
Yü Group (AIM:YU.)
Simply Wall St Value Rating: ★★★★★☆
Overview: Yü Group PLC, with a market cap of £305.06 million, operates through its subsidiaries to supply energy and utility solutions primarily in the United Kingdom.
Operations: The company generates revenue primarily from its Retail segment, contributing £700 million, with additional income from Smart and Metering Assets segments at £10.90 million and £1.80 million respectively. Intra-segment Trading reflects a negative impact of -£12.30 million on the overall revenue structure.
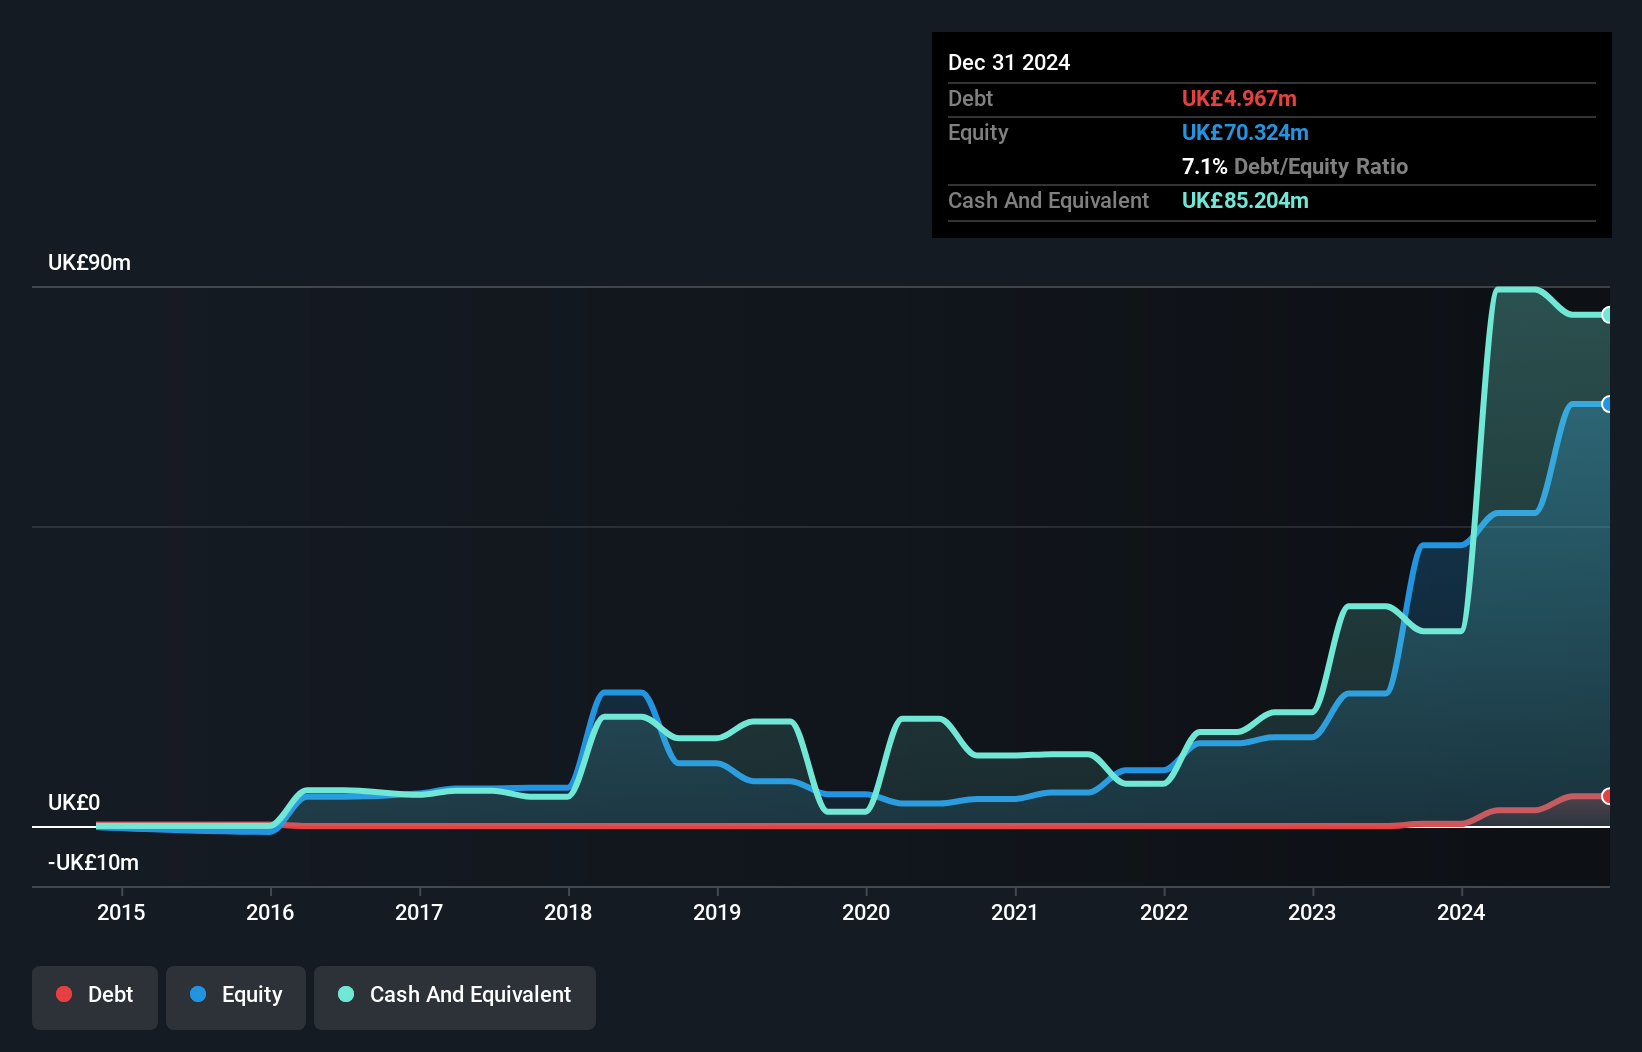
Yü Group, a smaller player in the UK energy sector, is making waves with its robust financials. The company trades at 50.7% below its estimated fair value, suggesting potential for appreciation. Over the past year, earnings grew by 7.2%, outpacing the Renewable Energy industry's -20% performance. With a debt-to-equity ratio rising to 10.5% over five years, Yü Group still holds more cash than total debt, indicating prudent financial management. Forecasts suggest earnings could grow by 13.88% annually, signaling promising prospects ahead for this dynamic entity in an evolving industry landscape.
- Click here and access our complete health analysis report to understand the dynamics of Yü Group.
Review our historical performance report to gain insights into Yü Group's's past performance.
LSL Property Services (LSE:LSL)
Simply Wall St Value Rating: ★★★★★☆
Overview: LSL Property Services plc, with a market cap of £258.59 million, operates as a business-to-business platform offering residential market services in the United Kingdom through its subsidiaries.
Operations: LSL Property Services generates revenue primarily through its business-to-business platform in the residential market sector within the UK. The company's financial performance is influenced by various revenue streams associated with these services.
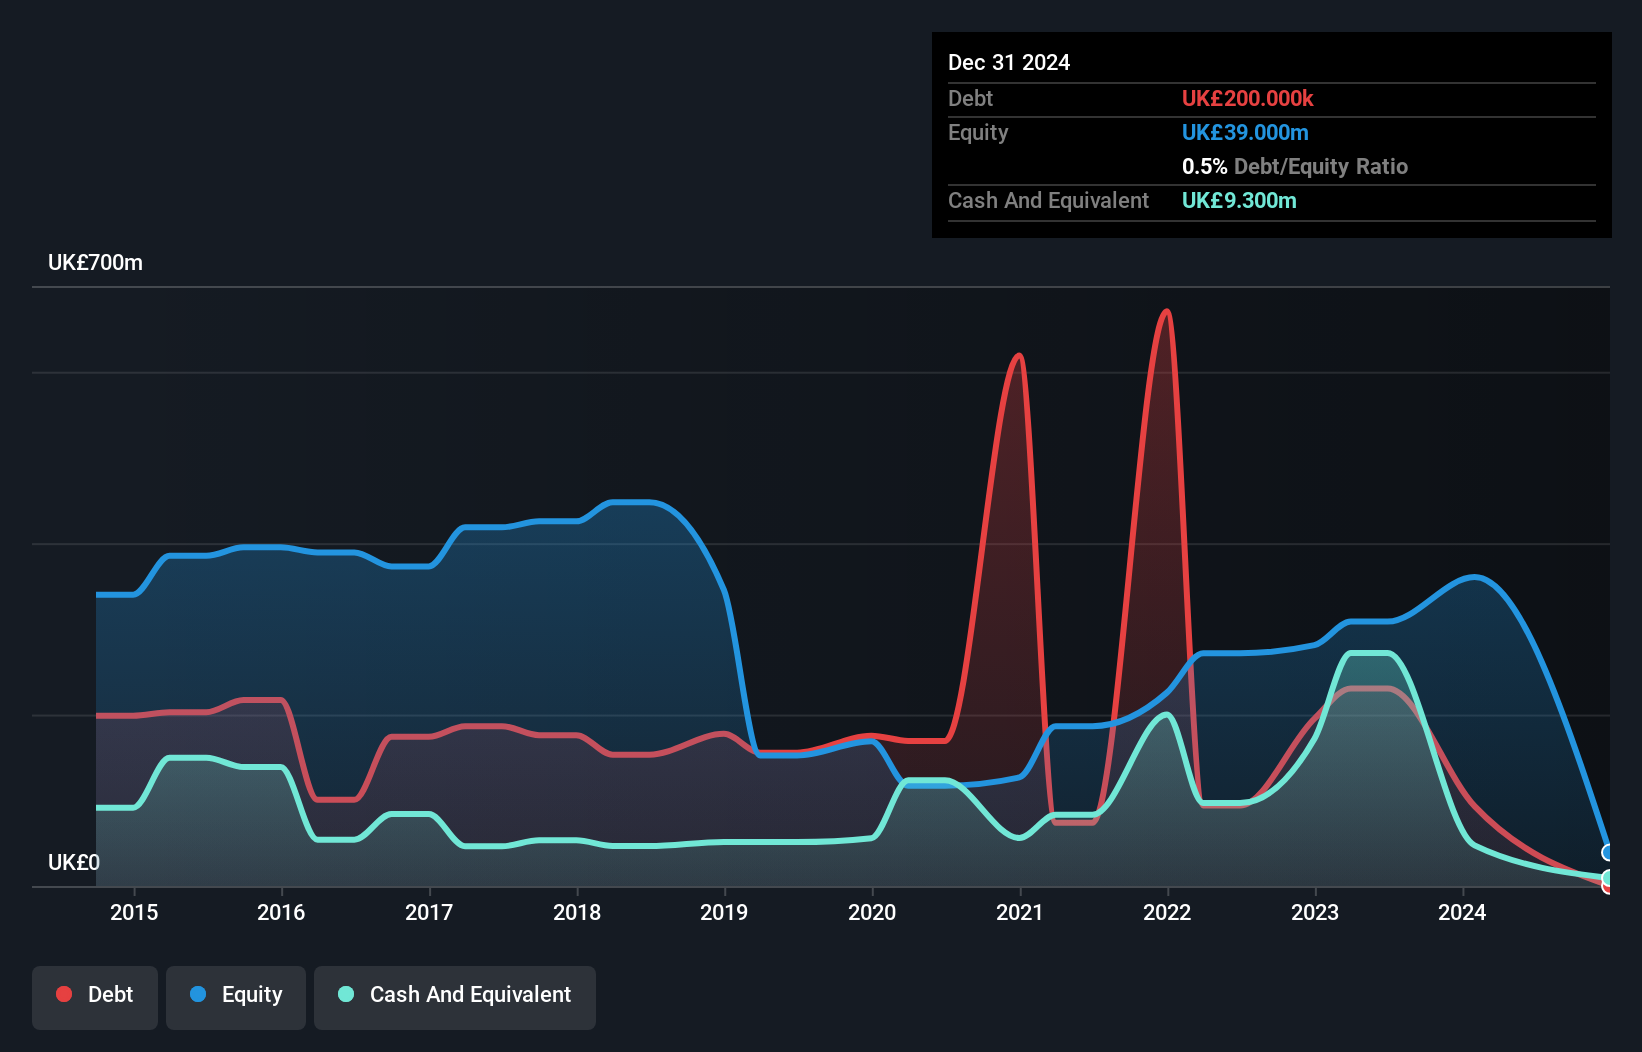
LSL Property Services, a smaller player in the UK real estate sector, has shown resilience with earnings growth of 7.3% over the past year, outpacing the industry average of -4.4%. The company reported a net income of £8.61 million for H1 2026, up from £8.19 million last year, with basic EPS rising to £0.086 from £0.08. Despite an increased debt-to-equity ratio from 3.2% to 39.8% over five years, LSL remains well-positioned financially by earning more interest than it pays and having more cash than total debt; it's trading at a significant discount to its estimated fair value by 53%.

Pinewood Technologies Group (LSE:PINE)
Simply Wall St Value Rating: ★★★★★☆
Overview: Pinewood Technologies Group PLC is a cloud-based dealer management software provider with operations spanning the United Kingdom, Europe, Africa, Asia, and the Middle East and has a market capitalization of £519.09 million.
Operations: Pinewood Technologies Group generates revenue primarily from its Pinewood segment (£36.10 million) and Seez segment (£4.40 million).
Pinewood Technologies Group, a nimble player in the automotive software sector, has seen its earnings soar by 708.9% over the past year, outpacing industry norms. Despite trading at 76.2% below estimated fair value and possessing more cash than total debt, Pinewood faces challenges with high operating costs and volatile share prices. The acquisition of Seez AI is set to bolster their market presence, particularly in North America. However, projected earnings declines of 23.1% annually for the next three years could strain profit margins despite anticipated revenue growth of 28.6%.
Key Takeaways
- Click this link to deep-dive into the 10 companies within our UK Undiscovered Gems With Strong Fundamentals screener.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com