


Manufacturing Expansion Could Be A Game Changer For Eaton (ETN)
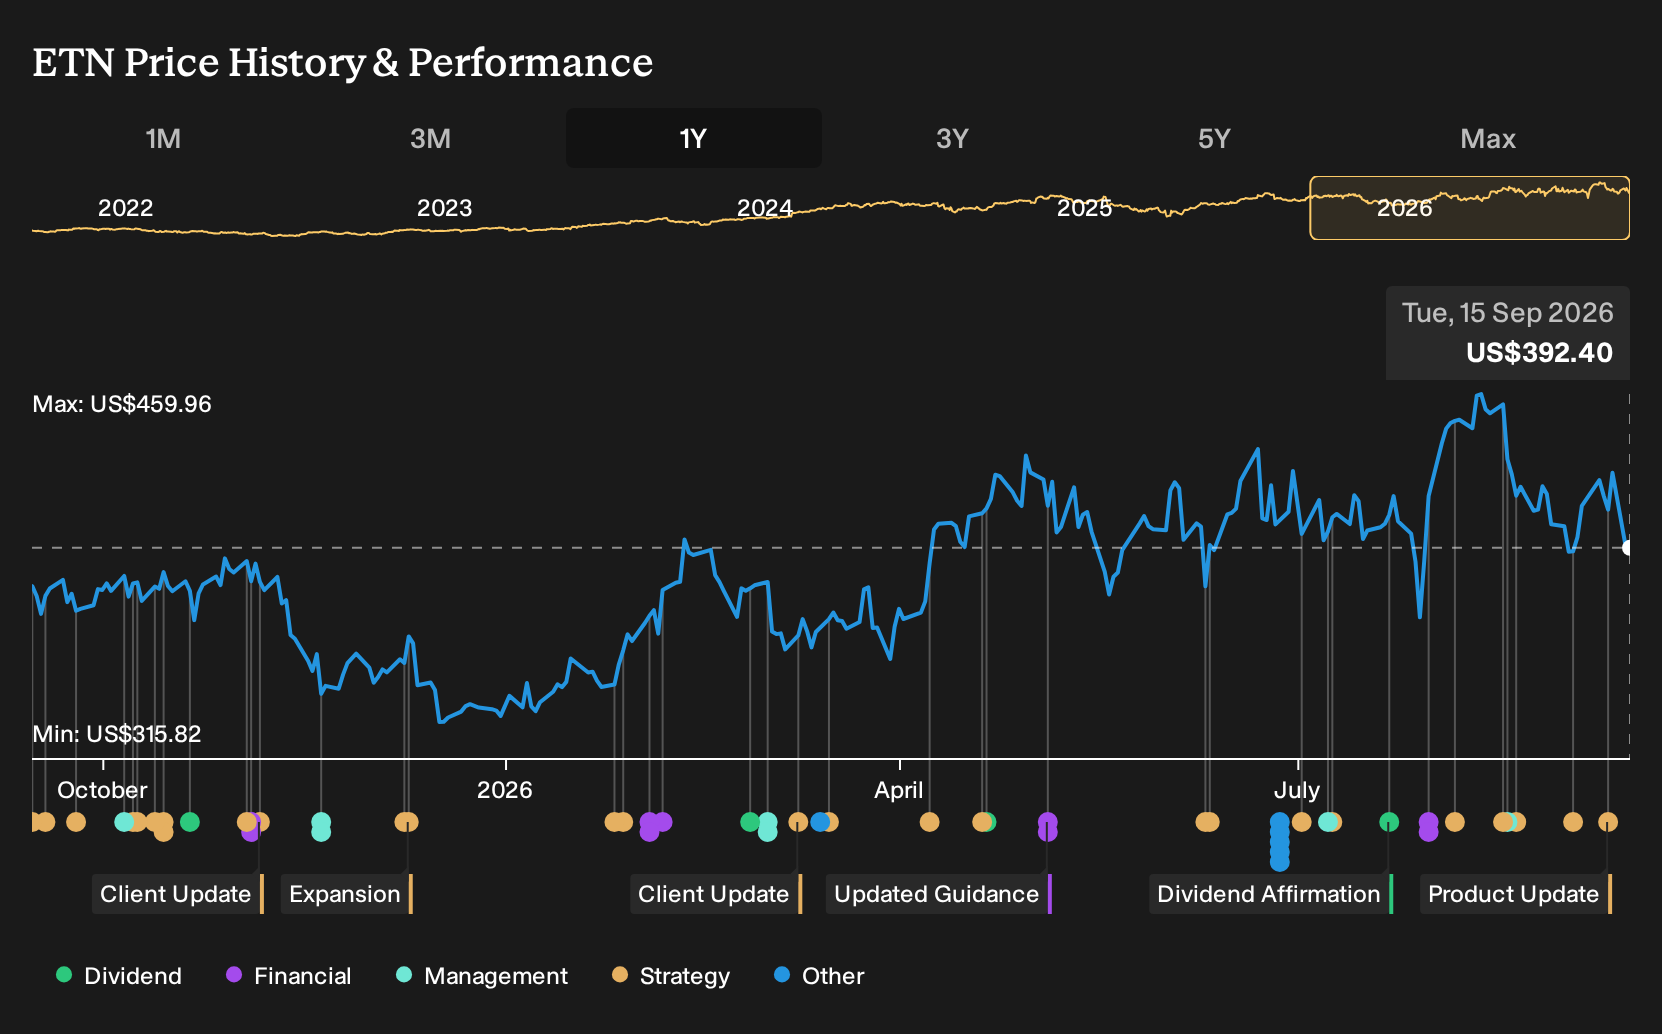
- Eaton has committed more than US$242 million to a new 1 million square foot facility in North Little Rock, Arkansas, aiming to double Fibrebond custom electrical enclosure capacity and create over 1,200 manufacturing, electrical and operations roles with structured technical training.
- The move ties Eaton directly into data center, utility, industrial and digital communications demand with onshore capacity, workforce development and closer control of its enclosure supply chain.
- The focus now turns to how Eaton's investment narrative is affected by this large scale U.S. capacity build out and job creation.
Scan beyond Eaton to compare this capacity and digital build out with other power grid and data center suppliers by reviewing our curated 38 power grid technology and infrastructure stocks right alongside this news.
Eaton Investment Narrative Recap
Eaton appeals to shareholders who buy into a long runway for electrification, grid hardening and data center build outs, supported by heavy upfront spending on plants, software and talent. The Arkansas facility and related Fibrebond capacity fit that story, but they likely keep near term margins under pressure while new sites work through early inefficiencies.
The biggest near term swing factor remains data center and large project timing in Electrical Americas, where order lumpiness can affect quarterly revenue and backlog visibility. Key risk sits in underperforming vehicle and eMobility operations and high investment spend, which could cap margin progress if execution or demand timing disappoints.
The Workbench 360 announcement is the clearest operational link to Eaton’s new enclosure capacity because it targets the design and project workflows that eventually turn into equipment orders. By embedding Eaton data and engineering support into Autodesk tools, the firm is trying to keep its hardware and software tightly connected throughout the building lifecycle.
For catalysts, this matters if Workbench 360 helps Eaton stay specified into more projects and reduces friction across design, construction and operations. The opportunity is that better visibility into equipment status and digital twins could support smoother ramps at the new Arkansas plant. The risk is execution complexity in digital tools while integration and capex already pressure costs.
Eaton's narrative projects US$42.2b revenue and US$7.0b earnings by 2029. This assumes 12.0% yearly revenue growth and an earnings increase of US$3.2b from US$3.8b today.
Uncover why Eaton's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts treat Eaton’s Workbench 360 style digital push as the real upside swing factor. Before this news, the most optimistic forecasts already penciled in 14.3% yearly revenue growth, US$42.6b sales and US$7.3b earnings by 2029. Those views are more upbeat than consensus and they might shift again as you explore alternative scenarios.
Explore 8 other Eaton fair value estimates, including one that suggests up to 36% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eaton research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking For More Ideas Beyond Eaton?
If Eaton's story has you thinking about how to position your portfolio for the next phase of electrification and infrastructure spending, it can help to line it up against other potential opportunities using a consistent framework.
Use the Simply Wall St Screener to widen your field of view and compare Eaton with other stocks that match different risk, income and quality profiles.
- If you want quality on sale, scan for companies that pair solid fundamentals with attractive pricing by checking out 34 high quality undervalued stocks.
- If resilience matters most to you, focus on businesses with stronger balance sheets and steadier financial profiles through the list of solid balance sheet and fundamentals (22 results).
- If you prefer a steadier income stream, filter for higher yielding payers that still meet core fundamental checks using the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com