


Is AI Marketing Partnership Altering The Investment Case For Estée Lauder (EL)?
- On 14 September 2026, The Estée Lauder Companies announced a global partnership with Profound, an AI marketing platform, to monitor and optimize how its full brand portfolio appears across major generative AI assistants such as ChatGPT and Gemini.
- The agreement gives Estée Lauder a consolidated view of how accurately its products, ingredients, and claims surface in AI-driven recommendations, which could influence how effectively consumers discover its brands across digital channels.
- This development may help shape Estée Lauder's investment narrative through its focus on AI-native discovery and content optimization.
Scan how Estée Lauder's AI-focused pivot compares with other beauty and consumer stocks leaning into digital discovery by zeroing in on our hand-picked 15 high quality undiscovered gems in this theme.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies, you need to believe its heavy spending on digital, AI and restructuring eventually turns a complex global portfolio into a cleaner, higher margin machine. The near term swing factor still sits in execution, especially how effectively these tools lift demand across travel retail, China and key Western markets where sentiment and conversion remain mixed.
The Profound partnership mostly speaks to medium term positioning rather than an immediate catalyst. In the short term, the bigger pressure points remain high fixed costs, debt, one off charges and a dividend that is not well covered by current earnings. If revenue traction lags these commitments, earnings volatility can stay elevated.
Among recent updates, the expanded role for Brian Franz as Chief Technology & Transformation Officer ties in most clearly with the Profound deal. He already oversees technology, data and analytics, as well as the Shopify and Accenture relationships, which sit at the core of Estée Lauder Companies’ push to align e commerce, shared services and AI driven marketing.
Investors watching catalysts may treat this leadership move as a test of whether the company can turn multiple digital projects into a single, efficient operating model across brands, travel retail and online partners like Amazon. The risk sits in complexity. Integration missteps, slow cost benefits or uneven execution could blunt the upside from the new AI marketing partnership.
Estée Lauder Companies' current analyst narrative points to revenues of $17.1b and earnings of $1.6b by 2029, based on forecast annual top line growth of 4.3% and an earnings increase from $182.0m today to that $1.6b level, which is roughly 8.8 times higher.
Uncover how Estée Lauder Companies' fair value indicates a 7% potential upside to its current price that may not last much longer.
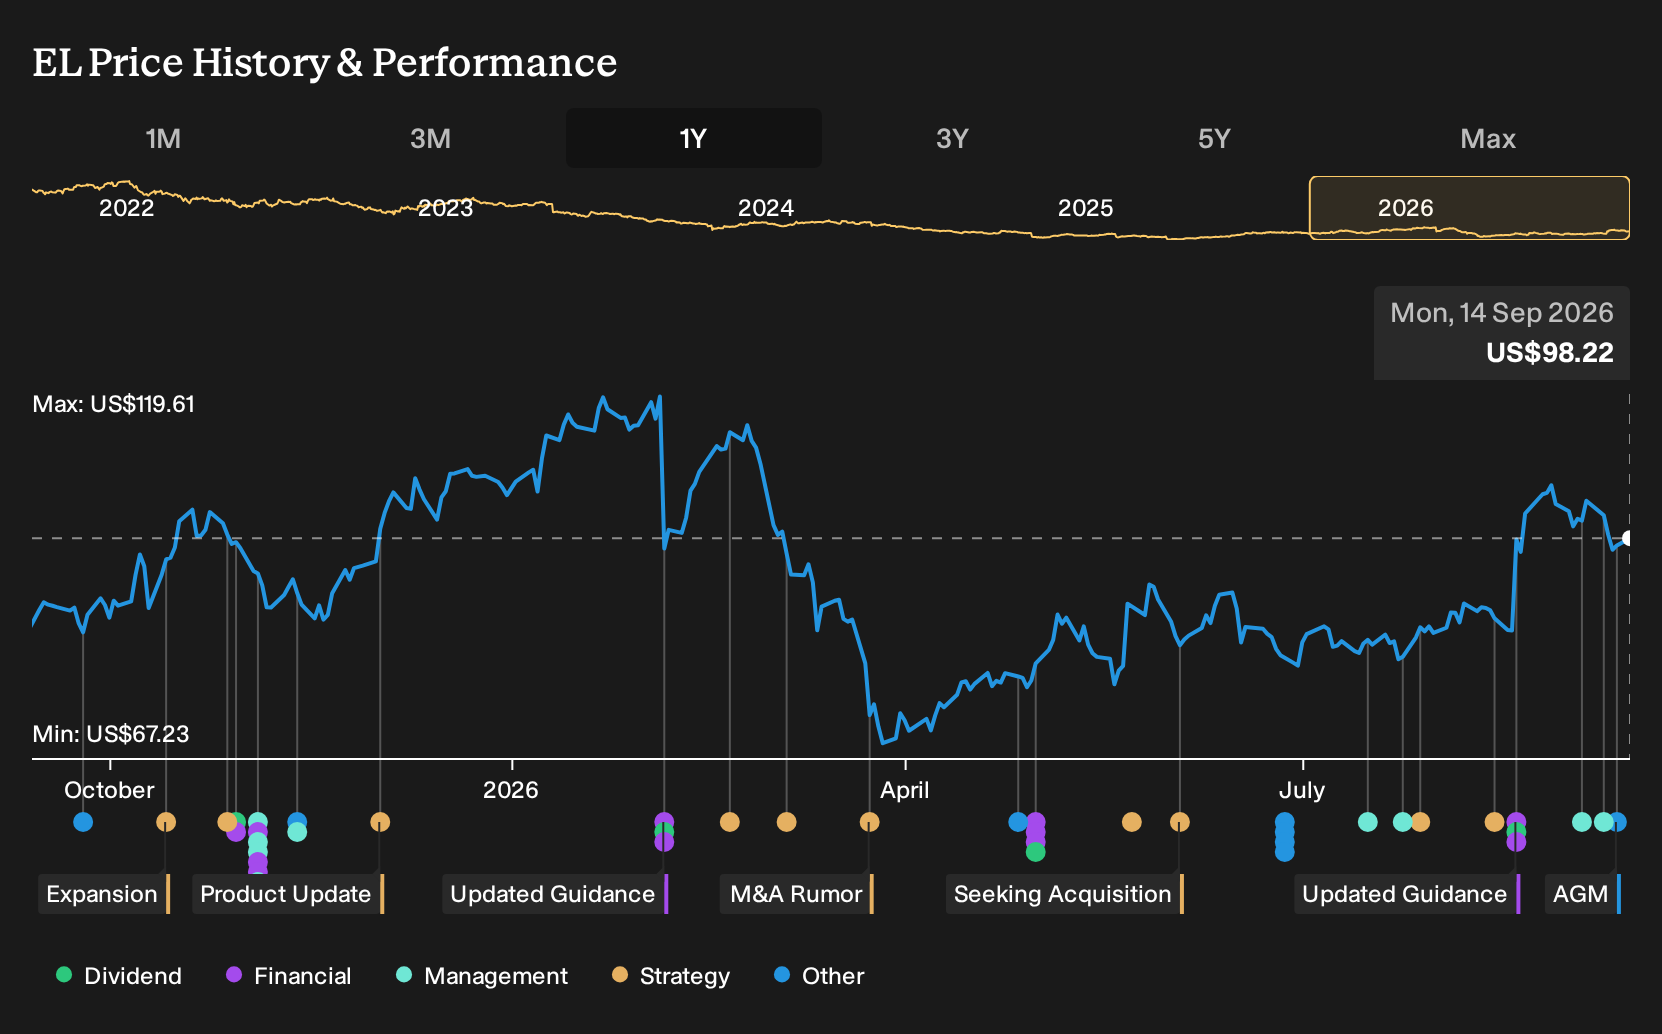
Exploring Other Perspectives
For Estée Lauder Companies, the bearish analysts fixate on travel retail volatility as the swing factor. They see revenue closer to $16.2b and earnings of about $1.5b by 2029, versus the higher consensus path. Those views were set before this Profound AI deal, so you may want to see how forecasts shift as AI discovery scales.
Explore 4 other Estée Lauder Companies fair value estimates, including one that suggests it could be worth just $97.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking for more Estée Lauder style investment ideas?
If Estée Lauder Companies has sharpened your focus on quality, income or resilience, it can be useful to line it up against a wider watchlist built around the same themes.
- For investors who care most about quality at a sensible entry point, scan a curated set of 35 high quality undervalued stocks that pair fundamentals with more grounded pricing.
- If durability matters more than excitement, stress test your portfolio against a 11 resilient stocks with low risk scores that screens for resilience first.
- When balance sheet strength is the priority, broaden your opportunity set with a list of solid balance sheet and fundamentals (23 results) that can complement stocks like Estée Lauder Companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com