


Sakata Seed (TSE:1377) Wraps Up Buyback, Is The Stock Still Undervalued?
Sakata Seed (TSE:1377) has just wrapped up a share repurchase tranche, buying 118,900 shares, or 0.28% of its equity, for ¥521.93 million under the program announced in mid July.
The buyback comes at a time when Sakata Seed’s short term share price momentum has been firm, with a 90 day share price return of 5.78%. The 1 year total shareholder return of 20.61% points to steadier long term compounding as dividends are included.
Scan how Sakata Seed’s buyback compares with peers by reviewing companies that also combine returning cash to shareholders with strong fundamentals through our curated list of solid balance sheet and fundamentals (19 results).
Sakata Seed appears to be a solid, globally diversified seeds business, and it is now shrinking its share count with buybacks. The key question is whether the current ¥4,390 price still leaves enough value on the table.
Price to Earnings of 15.3x: Is it justified?
Sakata Seed trades on a P/E of 15.3x at a last close of ¥4,390, which screens as inexpensive versus both its own fundamentals and direct peers.
The P/E ratio compares the current share price with earnings per share. For a seeds and horticulture specialist like Sakata Seed, it gives you a quick read on how much investors are currently willing to pay for each unit of profit.
On the numbers provided, the stock is described as good value relative to the JP Food sector average P/E of 17.3x and to its peer group on 19.2x. The valuation is also flagged as attractive versus an estimated fair P/E of 16.6x. That is a level the market could move towards if sentiment on its earnings stream lines up with that model.
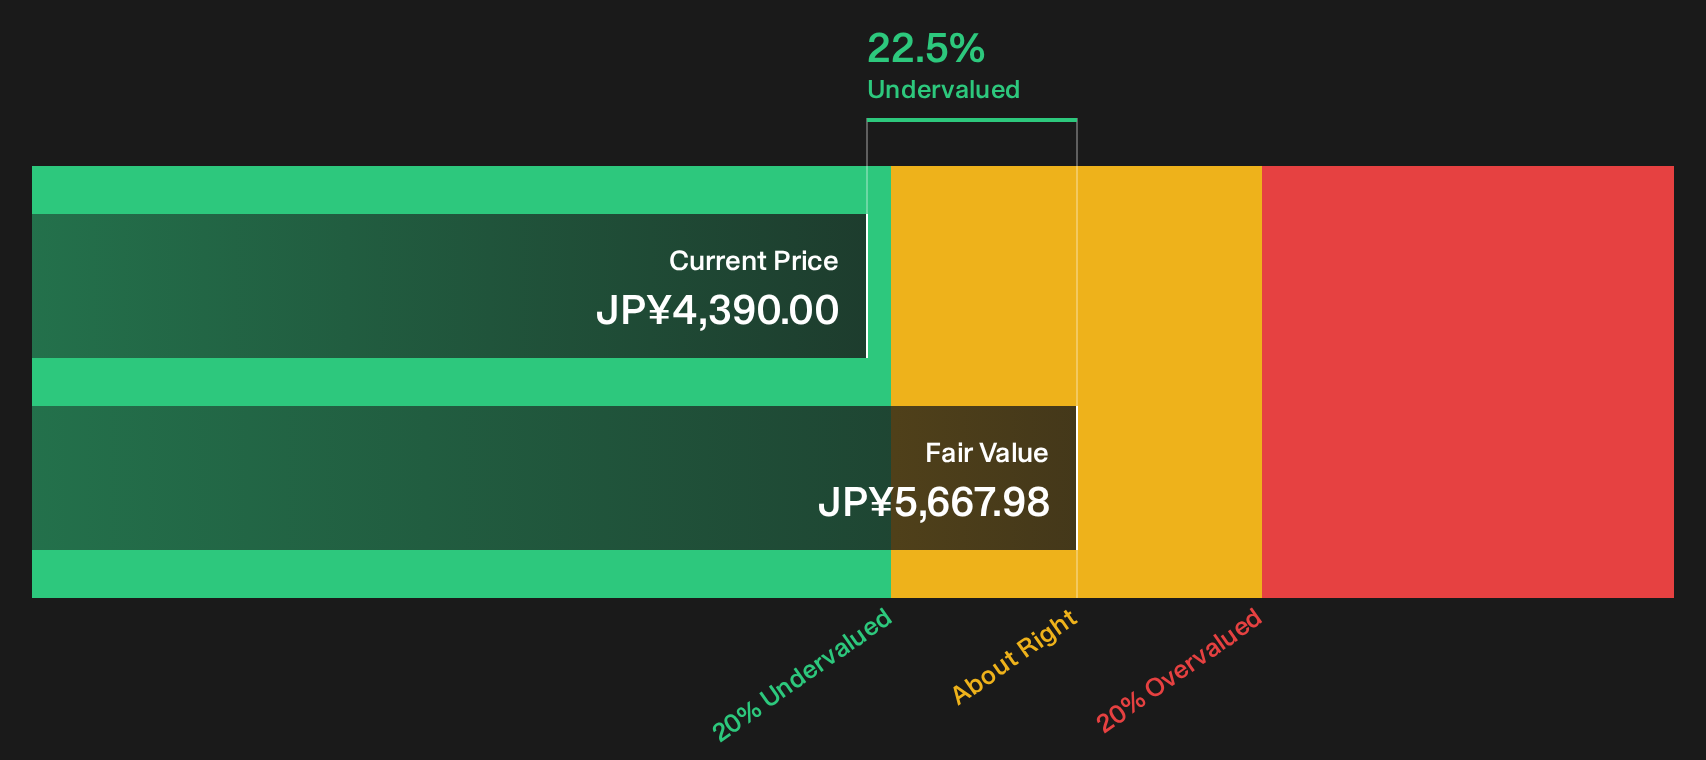
The combination of these checks, plus the indication that the shares trade 22.5% below an internal fair value estimate and below an SWS DCF future cash flow value of ¥5,667.98, suggests the current multiple is on the low side of what these frameworks imply.
Explore the SWS fair ratio for Sakata Seed.
Result: Price-to-earnings of 15.3x (UNDERVALUED)
Still, the Sakata Seed story could be knocked off course if overseas wholesale revenue of ¥84,904 million stalls, or if global horticulture demand softens.
Find out about the key risks to this Sakata Seed narrative.
Another View on Sakata Seed’s Value
There is a second lens to look through. Sakata Seed also screens as undervalued on our DCF model, with the shares at ¥4,390 compared with an internal future cash flow value estimate of ¥5,667.98. That gap raises a simple question for you: Is the discount compensation for risk, or an opening?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sakata Seed for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling mixed after all of this on Sakata Seed, with both upside and risk on the table? You can move quickly, review the underlying data, and decide where you stand by checking the full breakdown of 4 key rewards and 1 important warning sign.
Looking for more Sakata Seed style investment ideas?
If Sakata Seed has sparked your interest, do not stop here. Broaden your watchlist and give yourself more options by scanning other opportunities through the Simply Wall Street Screener.
- Target resilient balance sheets and steady fundamentals by reviewing a curated list of solid balance sheet and fundamentals (19 results) that filters out weaker financial profiles.
- Hunt for quality at a discount by scanning the 18 high quality undervalued stocks that flags companies where fundamentals and valuation screens look compelling.
- Focus on income potential and stability by checking the 17 dividend fortresses to see which payers combine yield with supportive financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com