


Is L'Oréal (ENXTPA:OR) Undervalued As Arizona Lawsuit Risks Come Into Focus?
The Arizona Attorney General’s consumer fraud lawsuit against L'Oréal (ENXTPA:OR) over alleged cancer risks in certain hair relaxer products puts legal, reputational and potential financial exposure directly in focus for shareholders.
The L'Oréal share price has moved only modestly in recent months, with a 1-day share price return of 1.15% and a year-to-date share price gain of 4.15%. The 1-year total shareholder return is slightly down 0.33%, which hints that recent momentum has softened even as the group promotes new campaigns like “Work Your Magic” and prepares to address investors at the Barclays Global Consumer Staples Conference.
Seize this moment to compare L'Oréal's legal and reputational risk profile with 100 resilient stocks with low risk scores that have been hand-picked for stronger perceived resilience.L'Oréal is trading near recent levels even as legal headlines build, which leaves you weighing a starter position today against holding out for a sharper pullback. How does the current valuation compare with that choice?
Most Popular Narrative: 9% Undervalued
L'Oréal's most followed valuation narrative points to a fair value above the recent €379.85 close, which puts the current share price at a discount and makes the long term earnings path central to any decision you take.
Acceleration of double-digit sales and volume growth in emerging markets, such as Mexico, Brazil, India, and Thailand, is expanding L'Oréal's addressable market and directly supporting long-term sustainable revenue and earnings growth.
Ongoing rapid shift to online channels, with e-commerce accounting for nearly 29% of first-half sales and growing at double the pace of the market, enhances direct-to-consumer margins and customer acquisition efficiency, bolstering both profitability and top-line expansion.
See why 85 investors see L'Oréal as 9% undervalued.
Result: Fair Value of €417.08 (UNDERVALUED)
Still, L'Oréal's narrative could be knocked off course if competition in China bites harder than expected or if advertising spend erodes the margin story.
Find out about the key risks to this L'Oréal narrative.
Another View on L'Oréal’s Valuation
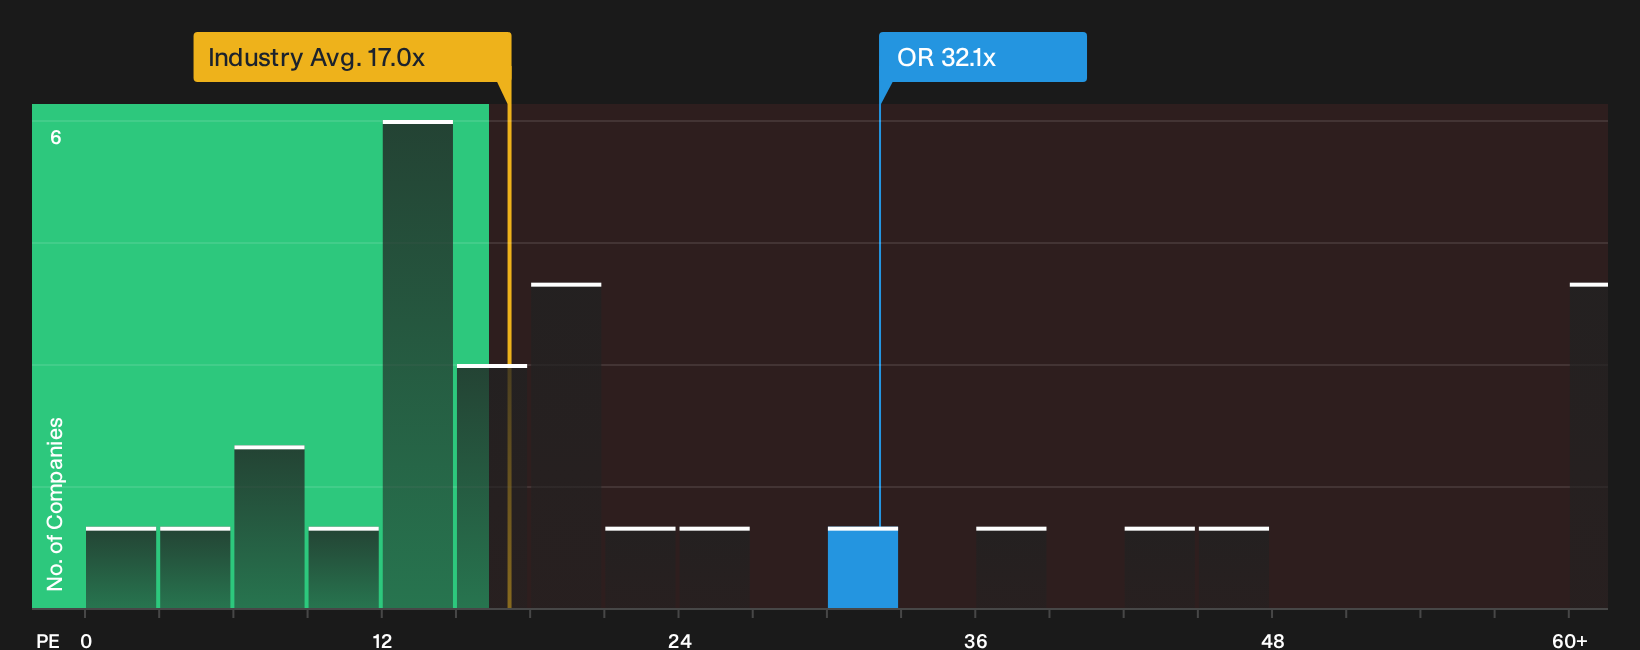
The earlier story leans on fair value estimates pointing to L'Oréal as 14.8% below one intrinsic value mark, yet the market is still paying a P/E of 32.1x compared with 26.2x for peers and 17x for the wider European personal products group. If the fair ratio is 33.2x, it is worth considering whether you are comfortable paying a premium today for growth that is only slightly ahead of the French market.
To see how that premium stacks up in hard numbers, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of legal risk and valuation debate around L'Oréal leaves you undecided, act quickly by checking the underlying data and pressure testing your thesis. To see the optimistic factors already identified for the business, review the 3 key rewards.
Looking for more investment ideas beyond L'Oréal?
If L'Oréal is only one piece of your watchlist, broaden your options now before the next move in the market leaves you reacting instead of prepared.
- Spot potential upside early by scanning 617 high quality undiscovered gems that pair strong fundamentals with lower profile coverage.
- Strengthen your downside protection with a list of solid balance sheet and fundamentals (194 results) that can better handle shocks when conditions turn rough.
- Target quality at a discount by using the 182 high quality undervalued stocks to focus on businesses with robust cash flows and appealing pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com