


AMD (AMD) Stock Looks Pricey Even With Cash Flow Upside
Advanced Micro Devices has delivered a very large 3 year return, yet its valuation checks disagree on whether the current share price leaves enough cushion. The Discounted Cash Flow (DCF) intrinsic value estimate points to some upside, while market based multiples lean expensive for AMD.
- A roughly 3 year return of about 4x suggests AMD has rewarded investors heavily and now trades with expectations that are already ambitious.
- The new AI infrastructure partnership in Saudi Arabia can support long term cash flow potential. However, any slowdown or delay in AI related demand could make today’s price look full.
- A low overall valuation score, with only 1 out of 6 checks screening as attractive, points to a stock that does not screen as a broad bargain even if one intrinsic value model shows AMD as undervalued by about 19%.
The issue now is whether AMD’s recent gains have already absorbed most of the upside suggested by the intrinsic value estimate, or if the market is still underpricing its long term cash generation potential.
Spot similar AI-driven stories by scanning the 89 AI infrastructure stocks that filters for hardware players riding the same data center and infrastructure wave as Advanced Micro Devices.Does Advanced Micro Devices Look Undervalued on Cash Flow?
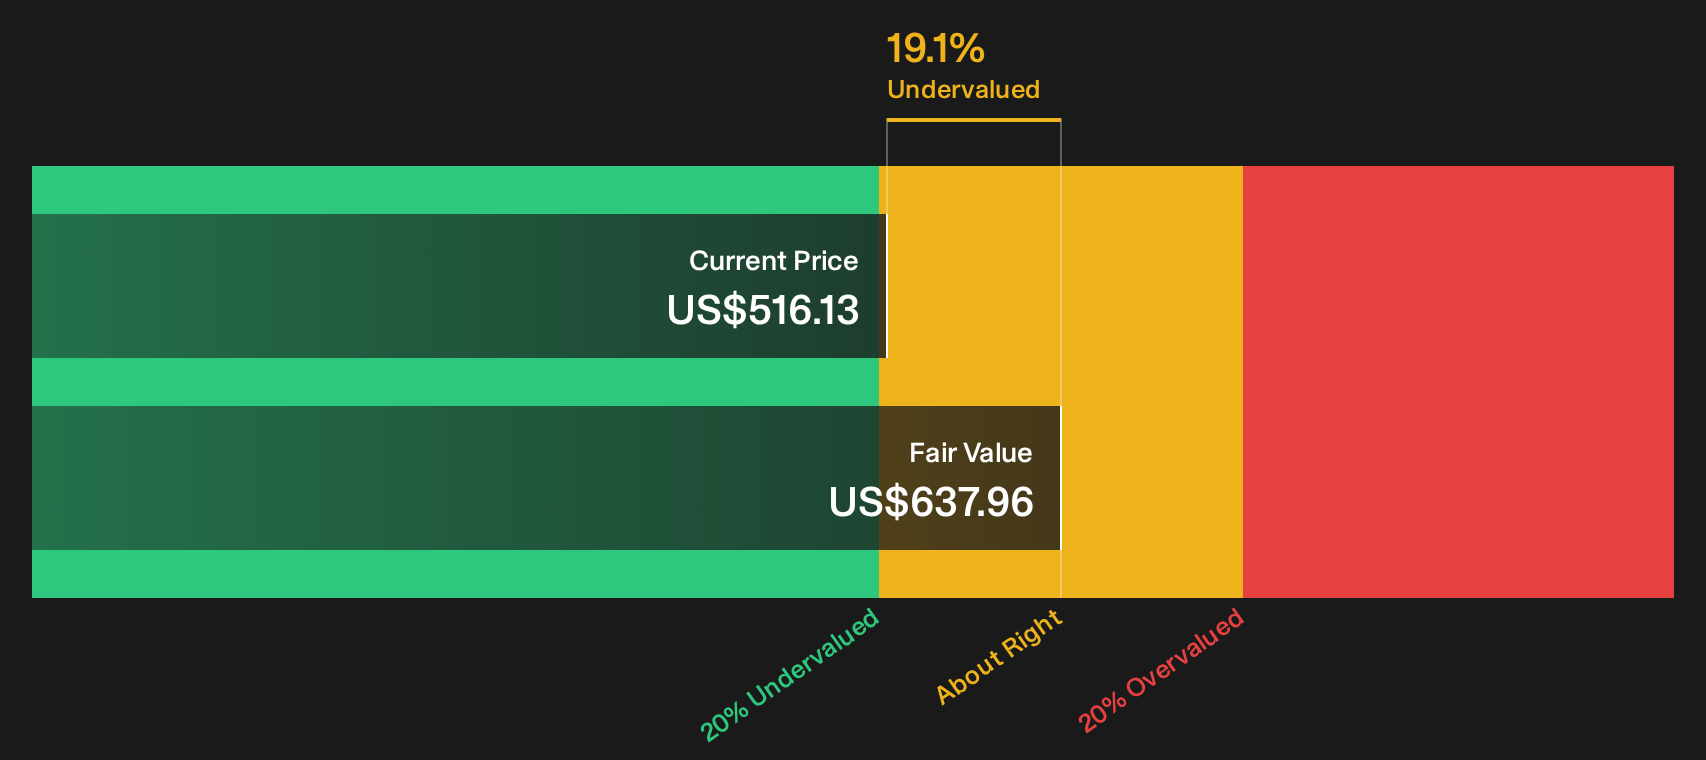
The Discounted Cash Flow (DCF) approach projects Advanced Micro Devices’ future free cash generation and then pulls those cash flows back to today’s dollars. Advanced Micro Devices is currently producing about $8.7b in free cash flow over the last twelve months, and the model assumes that cash flows grow from this base over time. On those projections, the 2 Stage Free Cash Flow to Equity model lands on an intrinsic value of about $638 per share.
Set against the current market price, that estimate suggests the stock is approximately 19.1% undervalued. The recent AI infrastructure launch in Saudi Arabia, which targets 1 GW of capacity by 2030, helps explain why cash flow assumptions lean supportive for Advanced Micro Devices even if the share price already embeds high expectations.
On this DCF view, Advanced Micro Devices stock appears undervalued relative to the cash flows analysts expect it to generate.
Our Discounted Cash Flow (DCF) analysis suggests Advanced Micro Devices is undervalued by 19.1%. Track this in your watchlist or portfolio, or discover 32 more high quality undervalued stocks.
Is Advanced Micro Devices Getting Expensive on Earnings?
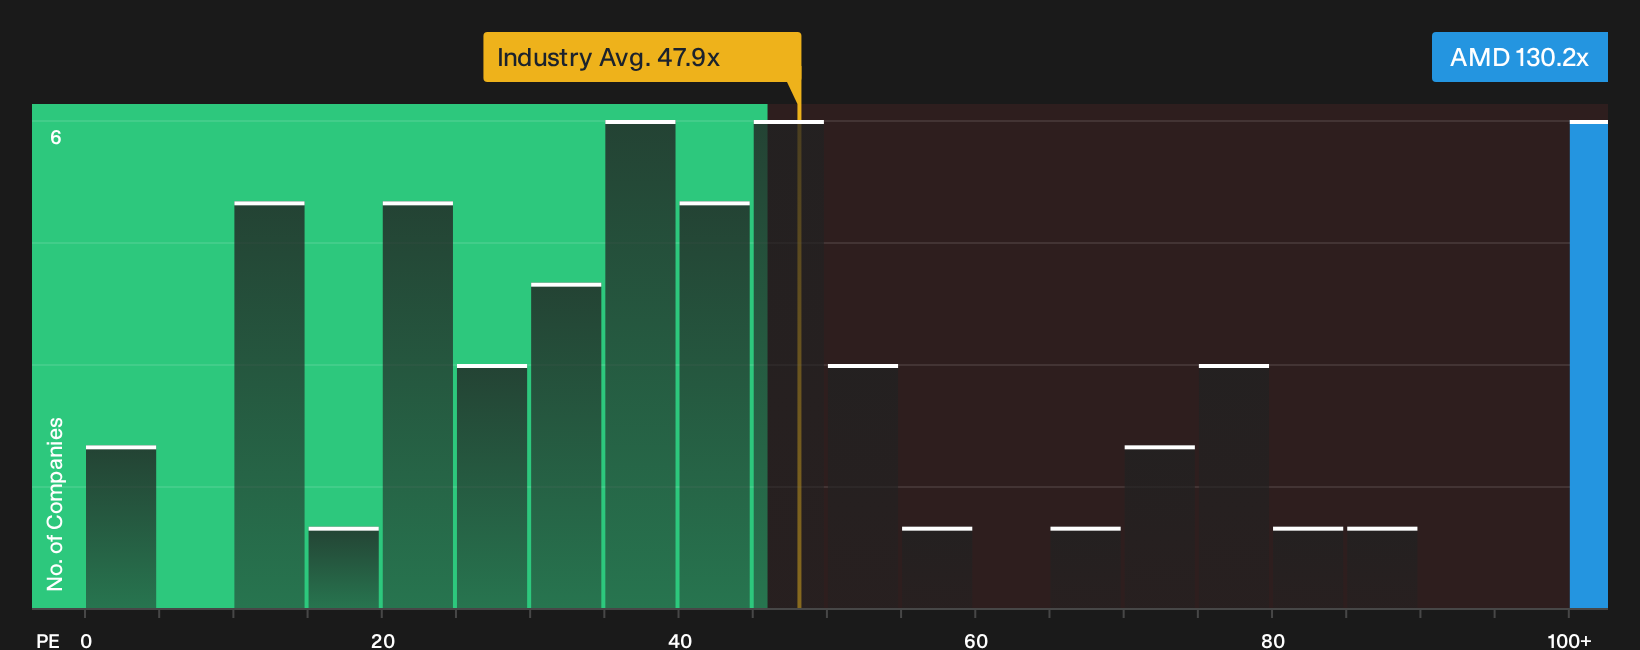
P/E is one way to gauge what you are paying for each dollar of Advanced Micro Devices earnings. On this metric, the stock carries a P/E of 130.2x, which is above both the semiconductor sector average of 47.9x and the peer group on about 46.5x.
A more tailored fair P/E for AMD, which blends its growth profile, margins, size and risk into a single benchmark, sits near 61.7x. That is less than half of the current earnings multiple. The gap indicates that investors are already assigning a substantial premium for Advanced Micro Devices future profit potential compared with what this framework would typically support for a semiconductor business.
On the P/E lens alone, Advanced Micro Devices stock appears overvalued relative to both sector norms and its own fair multiple estimate.
See what the numbers say about this price — find out in our valuation breakdown.
The Advanced Micro Devices Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Advanced Micro Devices pick up where the valuation split leaves you by spelling out which paths for growth, margins and earnings would need to play out for the stock to deserve a meaningfully higher or lower price than today, and they live on Simply Wall St's Community page. Each narrative treats fair value as a thesis about Advanced Micro Devices' business that you can watch over time, rather than as a one-off number.
Community views on Advanced Micro Devices could hardly be further apart, with one camp focused on execution risk and the other on AI upside.
Bull case: 16% undervalued
"Significant, sustained growth in AMD's Data Center and AI segments, driven by rapid adoption of EPYC CPUs and Instinct GPUs for cloud, enterprise, and emerging AI workloads, as well as a strong product roadmap (MI350/MI400), suggests durable revenue and earnings expansion over the long term…"
Read the full Bull Case to see why Advanced Micro Devices could be undervalued
Bear case: 15% overvalued
"While the valuation is stretched, the fundamental growth in data centre revenue and the raised long-term TAM suggest that the premium may be justified if execution remains flawless…"
Read the full Bear Case to see why Advanced Micro Devices could be overvalued
Do you think there's more to the story for Advanced Micro Devices? Head over to our Community to see what others are saying!
The Bottom Line
Advanced Micro Devices now screens as undervalued on a Discounted Cash Flow (DCF) view, yet screens overvalued on earnings multiples, which keeps the valuation debate wide open. The intrinsic value estimate leans on cash flow potential over time, while the P/E premium reflects how much investors are already paying for that AI story today. Broader checks remain weak, so the positive DCF signal sits alongside a relatively thin margin for error. The crux from here is whether Advanced Micro Devices can turn its AI and data center roadmap into sustained cash generation strong enough to justify, or exceed, the current earnings multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com