


What Is Drawing Fresh Attention To DoorDash (DASH)?
DoorDash (DASH) is back in focus after SKIMS, the apparel label co founded by Kim Kardashian, selected the delivery platform as its first on demand partner for nationwide store fulfillment.
For context, DoorDash shares now trade at US$201.95, with the 90 day share price return up 20.14% even as the 30 day move is down 6.94%. That mix of shorter term softness against a much stronger 3 year total shareholder return of 149.54% suggests momentum has cooled recently but has not reversed the longer trend.
Scan beyond DoorDash and see how other consumer platforms with on demand exposure are priced right now with our curated list of 15 high quality undiscovered gems.
DoorDash keeps signing high-profile partners and continues to show a very strong 3-year shareholder return, yet the share price has cooled in the short term. Is that strength already fully priced in, or not?
Most Popular Narrative: 20.6% Undervalued
On the most followed narrative, DoorDash’s fair value of about $254 sits well above the last close at $201.95. This frames the SKIMS deal inside a much larger long range thesis.
Rapid expansion into new verticals (grocery, retail, convenience, pharmacy) and international markets is yielding faster growth rates and improving unit economics, which should diversify and accelerate topline revenue while supporting net margin expansion.
Read the complete narrative. Read the complete narrative.
Curious what sits behind that gap between fair value and today’s share price? The story leans heavily on stepped up earnings power, richer margins, and a different profit mix than DoorDash shows today.
Result: Fair Value of $254 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the DoorDash narrative could be knocked off course if expansion costs stay heavy or if tighter gig work rules squeeze delivery economics.
Find out about the key risks to this DoorDash narrative.
Another View: DoorDash Through A P/E Lens
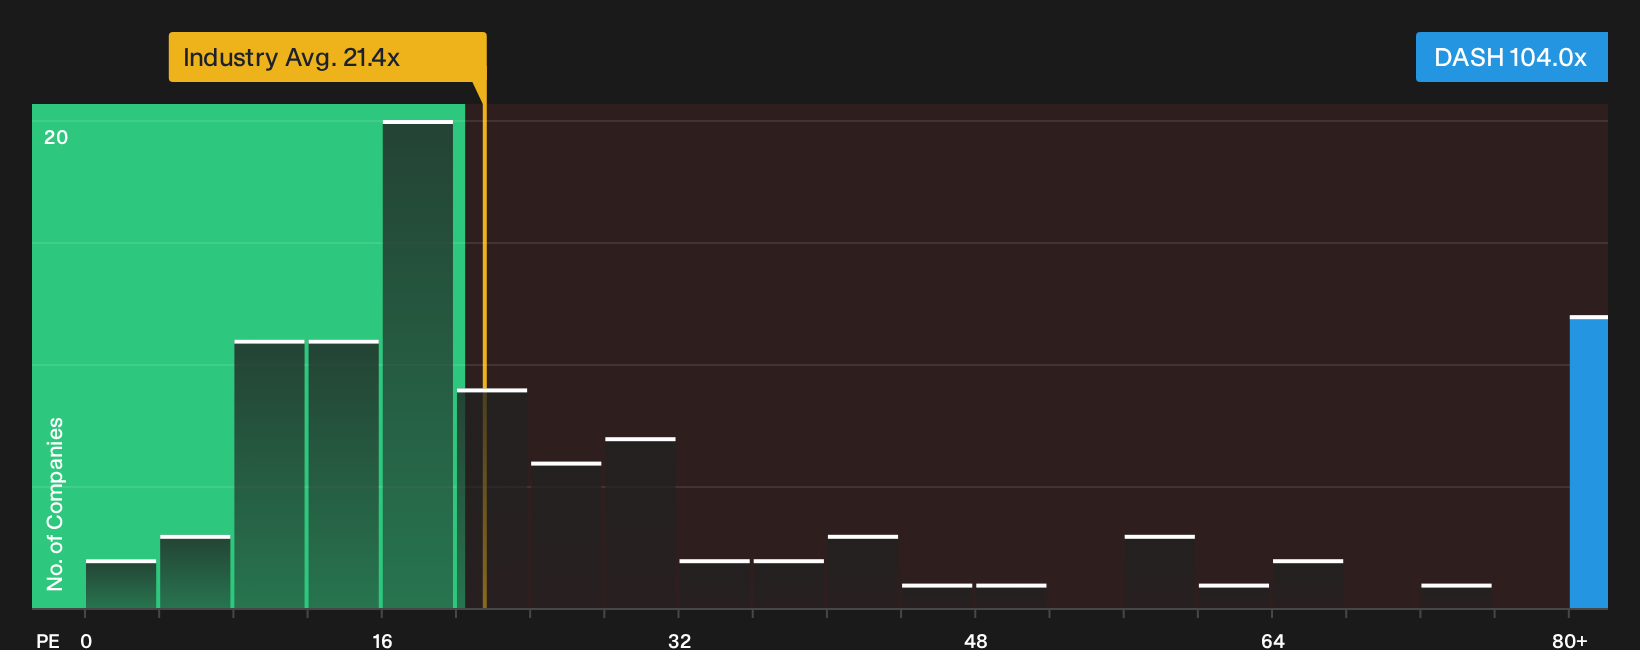
The DCF narrative paints DoorDash as materially undervalued, yet the market is asking a very different price. At about 104x current earnings, the P/E is far above the US Hospitality sector at 21.4x and the peer average at 31.4x, and even well above the 46.4x fair ratio estimate. That kind of premium can signal confidence in future growth, or it can simply raise the bar uncomfortably high for what needs to go right.
For investors weighing that gap between earnings-based pricing and story-driven fair value, the valuation breakdown helps show where expectations cluster and where they might be stretched, especially if sentiment toward richly valued platforms shifts quickly. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around DoorDash are clear, with both risks and rewards in play. Move quickly, review the numbers, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DoorDash?
If DoorDash has your attention, do not stop there. Broaden your watchlist with other focused opportunities that could sharpen your overall portfolio decisions.
- Target steady cash generators by tracking companies built on reliable payouts through 6 dividend fortresses.
- Hunt for quality businesses where price and fundamentals still look compelling using the 32 high quality undervalued stocks.
- Prioritize resilience by focusing on companies that pair conservative balance sheets with disciplined operations through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com