


EnerSys (ENS) Stock May Be 2% Above Fair Value On Cash Flow
EnerSys has delivered a strong run over the past five years, yet the share price now sits close to an intrinsic value estimate that points to only a small premium over the current market level. At the same time, earnings-based multiples still screen the stock as undervalued, so the setup is less obviously cheap than the past returns might suggest.
- EnerSys has returned roughly 147.0% over five years, which puts pressure on any new buyer to be comfortable with what is already priced in.
- The investment case can benefit if the business converts a greater share of earnings into steady cash flow, while any hit to profitability or heavier capital spending may weaken that support.
- The broader checks show a mixed picture rather than a clear bargain or clear overvaluation, with the 4.0 value score sitting in the middle of the range.
The issue now is whether EnerSys at around US$179 per share offers enough valuation support after this long run to justify taking on fresh risk.
Balance EnerSys in your watchlist by scouting other potential value setups that combine solid fundamentals with reasonable pricing through our curated 32 high quality undervalued stocks.
Is EnerSys Fairly Priced on Cash Flow?
The Discounted Cash Flow model for EnerSys starts with what the business is already producing in cash and asks what that stream is worth today. Over the last twelve months, EnerSys generated about $678.7 million in free cash flow, and the forecast path in the model assumes that this cash generation moderates rather than ramps sharply higher over time.
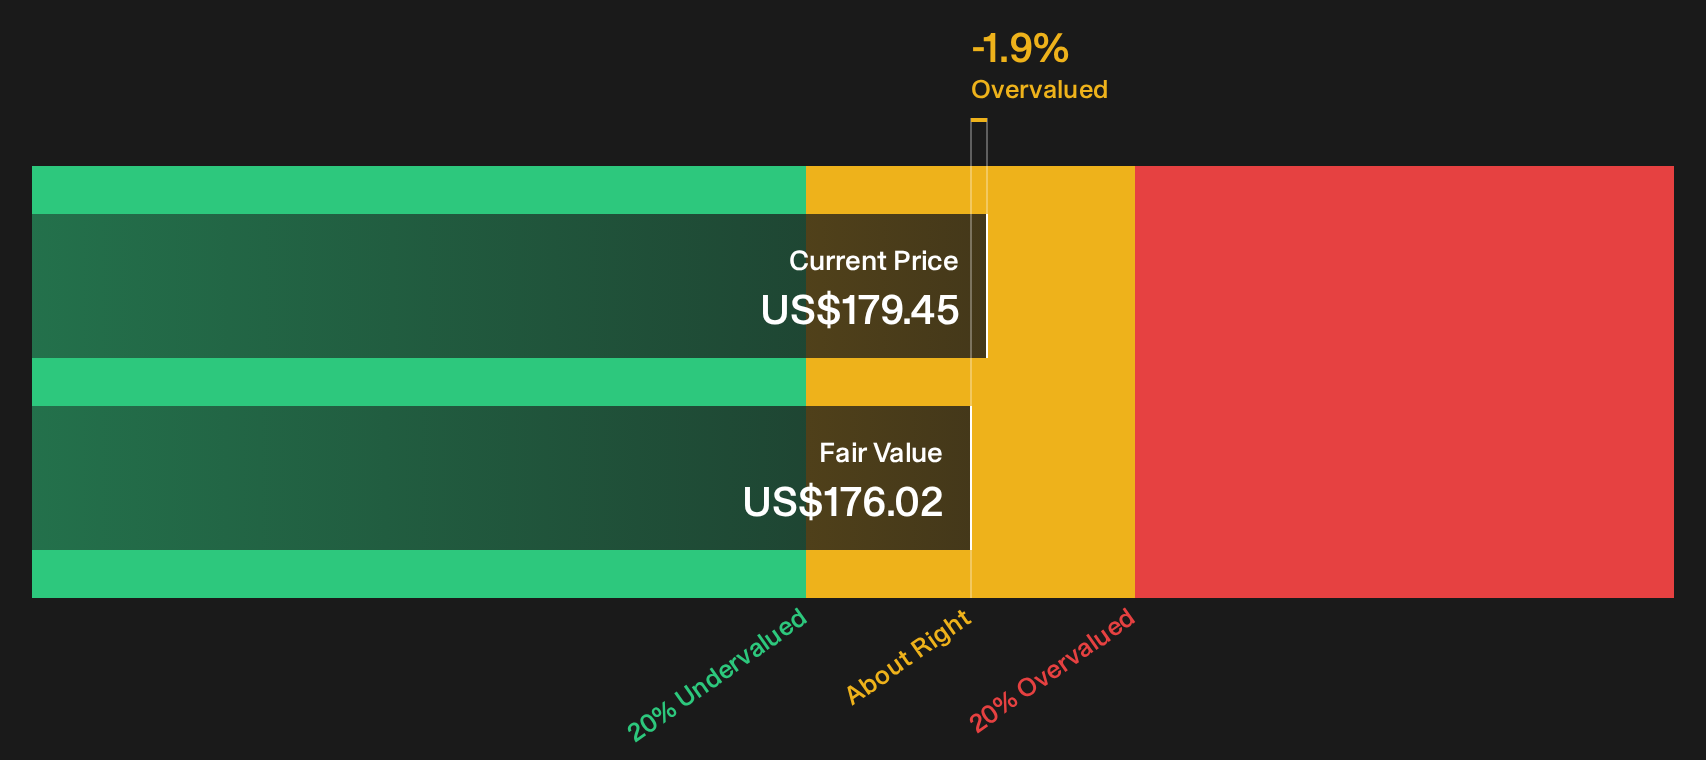
Using those inputs, the DCF points to an intrinsic value of roughly $176 per share, compared with a current trading level around $179. That small 1.9% premium suggests the market price is broadly aligned with the cash flow outlook, leaving only a thin margin for error if free cash flow softens or capital needs rise from here.
On balance, the Discounted Cash Flow workup indicates EnerSys appears about fairly valued at current levels.
EnerSys is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Is EnerSys Still Cheap on Earnings?
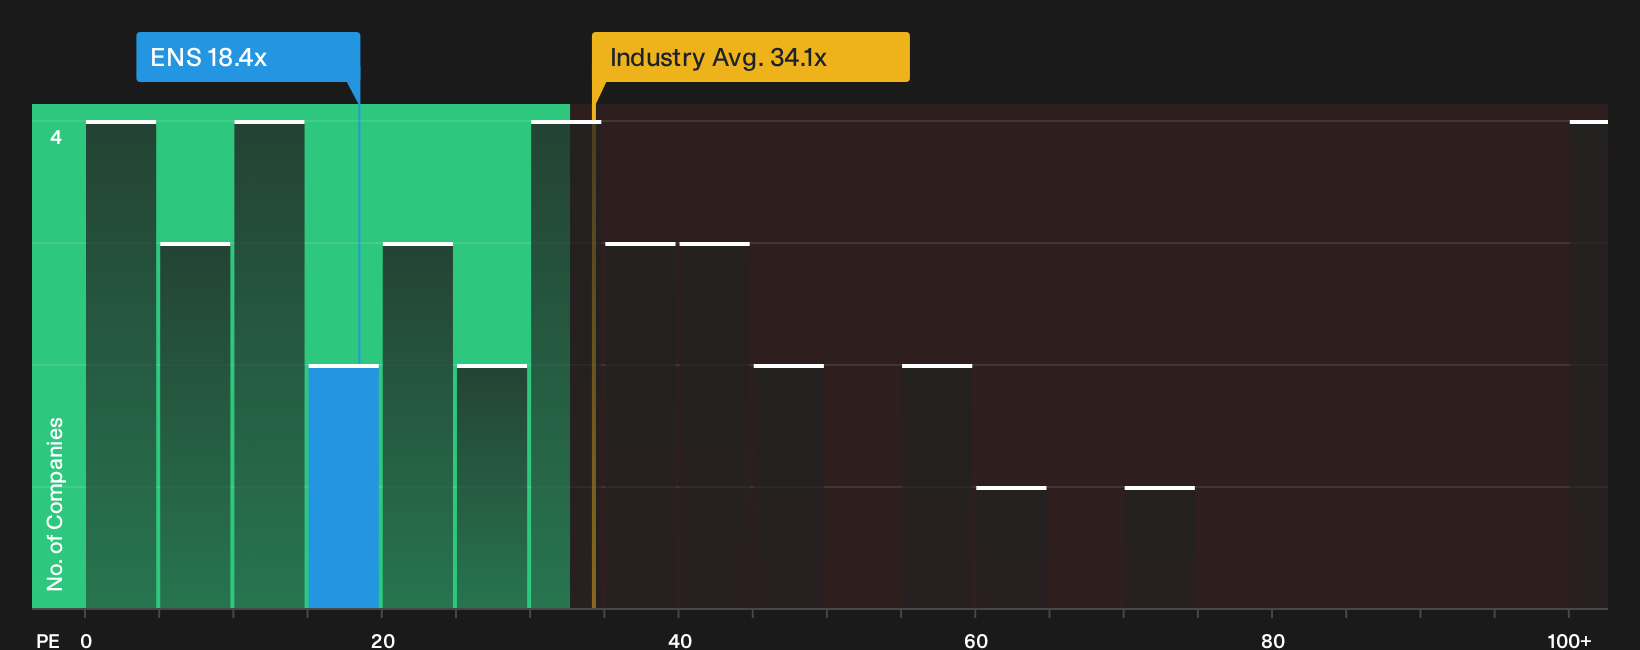
The P/E ratio is a useful lens for EnerSys because earnings remain the core yardstick many investors use to weigh what they are paying for each dollar of profit. On this measure, EnerSys trades on roughly 18.4x earnings, which is well below the Electrical industry average of about 34.1x and the broader peer group around 47.1x.
The modelled fair P/E ratio for EnerSys is 24.2x, which reflects what investors might pay given its sector, profitability profile and risk mix. That is above the current 18.4x level, so the gap implies the stock is pricing in a discount relative to what this framework suggests could be justified for the business.
On this earnings multiple, EnerSys appears undervalued compared with both its tailored fair P/E and the going rate for peers in the Electrical industry.
See what the numbers say about this price — find out in our valuation breakdown.
The EnerSys Narrative: What Would Justify Today's Price?
EnerSys' Simply Wall St Narratives pick up where the valuation puzzle leaves off. They spell out which expectations on future growth, margins and earnings would need to play out for the share price to sit meaningfully above or below where it trades today, and each one treats fair value as a thesis you can track over time rather than a one-off snapshot on a chart.
One of the top community narratives on EnerSys: 12% undervalued
"EnerSys refined its plans for a U.S. lithium cell manufacturing facility in Greenville, South Carolina, with a focus on aerospace, defense, and specialized industrial applications that require a secure U.S.-based supply chain..."
Read one of the top narratives on EnerSys
Do you think there's more to the story for EnerSys? Head over to our Community to see what others are saying!
The Bottom Line
EnerSys looks close to intrinsic value on a Discounted Cash Flow (DCF) view, so the easy valuation upside on cash generation alone appears limited for now. The P/E work still signals undervalued against peers, which points more to sentiment and relative positioning rather than to a clear mispricing of the business itself. With broader checks landing in a mixed zone, the real hinge for both bulls and bears is whether earnings quality and cash conversion stay strong enough to justify any future rerating of the multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com