


Prosperity Bancshares (PB) Faces A Valuation Test, Does The Undervalued Case Hold Up?
Prosperity Bancshares (PB) drew investor attention after its recent share move, with the stock around $71.35. This prompted fresh questions about how its banking-focused business lines support that valuation.
Recent trading has been softer, with the share price down 4.9% over the past month and 2% over the last week. However, Prosperity Bancshares still shows an 8.9% one year total shareholder return and a 37.8% three year total shareholder return, suggesting longer term holders have fared much better than short term traders reacting to the latest move around $71.35.
Scan how Prosperity Bancshares compares with other regional financials by reviewing a curated group of list of solid balance sheet and fundamentals (23 results).
Prosperity Bancshares now sits between bulls who point to recent revenue and net income growth and bears who focus on the softer near term share move. Which side do the current valuation markers lean toward next?
Most Popular Narrative: 12% Undervalued
Prosperity Bancshares is framed as undervalued in the most followed fair value narrative, with that view anchored to a discount rate of 7.1% and a higher intrinsic value than the recent $71.35 close.
Repricing of a sizable bond portfolio and rollover of existing loans at higher yields, combined with a disciplined deposit pricing strategy and low-cost core deposit base, are set to meaningfully increase net interest margin and net interest income through 2026. Continued operational efficiency, evidenced by a declining efficiency ratio and strong cost controls, positions the company to expand net margins and drive robust earnings irrespective of rate environment volatility.
Want to see what sits behind that bond repricing story and margin lift argument. The narrative leans on a specific mix of revenue growth, profitability and valuation assumptions that tie this fair value back to today’s price without leaving much room for guesswork.
Result: Fair Value of $80.85 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Prosperity Bancshares story can be knocked off course if credit quality weakens further, or if loan and deposit declines prove harder to reverse.
Find out about the key risks to this Prosperity Bancshares narrative.
Another View On Prosperity Bancshares’ Valuation
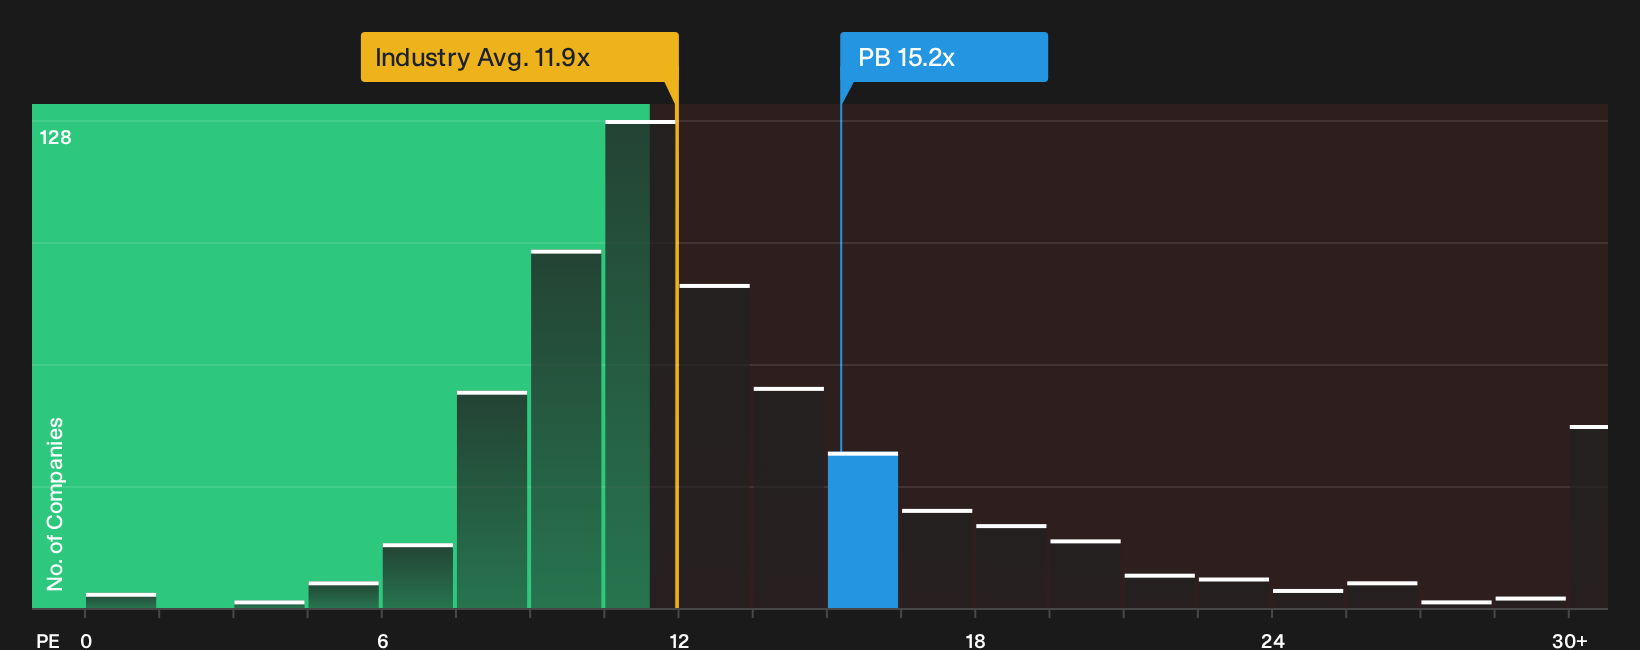
Multiples tell a different story. Prosperity Bancshares trades on a P/E of 15.2x, which is higher than both the US Banks industry at 11.9x and its peer group at 12x, even though the fair ratio for the stock is estimated at 16.3x. That gap leaves investors weighing whether they see valuation risk or a narrow opportunity if sentiment shifts toward that fair ratio.
For a closer look at how this pricing compares with the numbers that underpin it, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does that mix of optimism and caution around Prosperity Bancshares feel balanced to you, or a little off? Act promptly, review the underlying figures and recent trends yourself, then weigh both sides of the story by checking the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Prosperity Bancshares?
If Prosperity Bancshares has sharpened your thinking, do not stop there. Use the Simply Wall Street Screener to uncover fresh opportunities that match your goals.
- Target potential upside by scanning a curated shortlist of 15 high quality undiscovered gems that pair strong fundamentals with lower market attention.
- Prioritise resilience by filtering for 11 resilient stocks with low risk scores that score well on financial strength and business stability.
- Strengthen your income game by zeroing in on 6 dividend fortresses built around higher yields and resilient payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com