


Packaging Corporation Of America (PKG) Stock Looks Rich At Current Levels
Packaging Corporation of America has delivered a powerful 91.4% return over the past five years, yet current valuation checks lean expensive, which puts recent share gains at odds with what the broader metrics are suggesting.
- A 91.4% gain over five years highlights how strongly the stock has rewarded patient holders, which raises the bar for any new upside from here.
- Future pricing power and cost discipline can support earnings resilience, while any hit to volumes or margins may quickly pressure what investors are currently willing to pay for those profits.
- A value score of 2 out of 6 suggests Packaging Corporation of America leans expensive on the broader checks rather than screening as a clear bargain.
For investors, the debate is whether Packaging Corporation of America’s strong multi year run leaves enough valuation headroom for attractive returns over the next five years.
Balance those strong Packaging Corporation of America gains by scanning a curated list of sturdier valuations through 32 high quality undervalued stocks before you commit fresh capital at richer prices.
Does Packaging Corporation of America Look Pricey on Earnings?
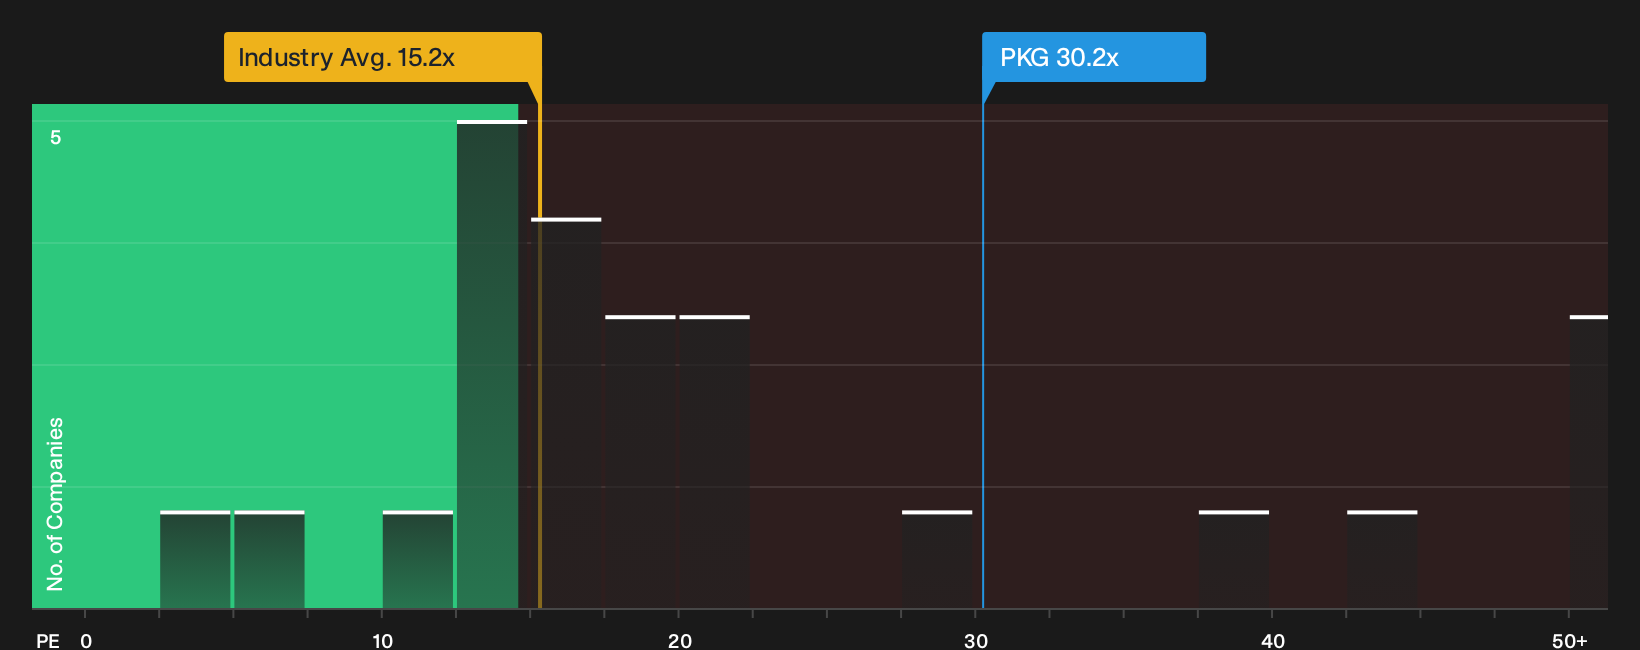
The P/E ratio suits Packaging Corporation of America because earnings are a core anchor for how investors value this mature, cash generative business. On that basis, the stock trades on about 30.2x earnings, which is well above the packaging industry average of roughly 15.2x and also ahead of the peer group level around 22.2x. That pricing implies investors are already paying a premium for each dollar of profit relative to many other packaging companies.
A more tailored fair P/E multiple for Packaging Corporation of America, which factors in its sector, size and risk profile, is closer to 27.0x. The current 30.2x level is higher than that reference point, so the shares screen as overvalued on this earnings yardstick even before considering any additional optimism reflected in the price.
On the P/E measure, Packaging Corporation of America stock appears overvalued compared with both its fair multiple and wider industry levels.
See what the numbers say about this price — find out in our valuation breakdown.
The Packaging Corporation of America Narrative: What Would Justify Today's Price?
Packaging Corporation of America’s current P/E debate sets up the role of Simply Wall St Narratives. These link today’s valuation to the specific paths for future earnings, margins and growth that would need to play out for the stock to be worth materially more or less than its present price on the screen. Rather than relying on a single multiple or model line, each narrative spells out the assumptions behind its fair value view so you can track those expectations against actual results over time on the Community page.
Community views on Packaging Corporation of America sit far apart, with one camp focused on pricing power and efficiency and the other on structural demand and cost risks.
Bull case: 9% undervalued
"The successful startup of the new efficient box plant in Glendale, Arizona, is expected to increase productivity, reduce costs, and enhance service capabilities..."
Read the full Bull Case to see why Packaging Corporation of America could be undervalued
Bear case: 27% overvalued
"Despite recent revenue and margin gains, long-term advances in digitalization and new fulfillment models such as reusable containers and automation threaten to structurally lower demand for traditional corrugated packaging..."
Read the full Bear Case to see why Packaging Corporation of America could be overvalued
Do you think there's more to the story for Packaging Corporation of America? Head over to our Community to see what others are saying!
The Bottom Line
Packaging Corporation of America now screens as overvalued on the main earnings multiples, which means fresh buyers are relying on that premium holding or stretching further. The broader valuation checks lean weak, so the burden of proof sits with future execution rather than a built-in discount. Everything comes back to one question: Can Packaging Corporation of America defend margins and pricing power enough to keep investors comfortable paying this kind of multiple for a mature packaging business?
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com