


Job Cuts Might Change The Case For Investing In Uber Stock (UBER)
- Uber Technologies is cutting about 3,300 corporate roles, roughly 10% of its global staff, to simplify its structure and redirect resources into a €4b-class autonomous vehicle program and related growth projects.
- The restructuring coincides with Uber’s push into Level 4 robotaxis in Madrid and large euro bond issuances. This points to a capital plan that leans on debt funding while keeping operating costs under tighter control.
- We will now look at how Uber Technologies' workforce cuts to fund autonomous vehicles could reshape the broader investment narrative.
Scan how Uber Technologies is repositioning around autonomous mobility, then compare it with other potential breakout opportunities in 89 AI infrastructure stocks that sit at the crossroads of AI and real-world transport systems.
Uber Technologies Investment Narrative Recap
To own Uber Technologies, an investor needs to believe the platform can convert its large Mobility and Delivery footprint into steady free cash flow while committing about $10 billion to autonomous vehicles (AVs). The Madrid Level 4 permit, together with the recent large euro bond issues, signals a push to scale AV operations and keep the marketplace attractive for riders and merchants.
The key near‑term catalyst is execution on AV pilots and lower rider prices, while avoiding further pressure on already thinner 17.3% net margins. The main risk is that heavy AV and membership investment, combined with pricing pressure and regulatory costs, could keep profitability under strain even if revenue grows around existing services.
The Madrid AV permit comes alongside another important development. Uber Technologies recently priced several euro bond tranches, including 3.75% to 5.25% fixed‑rate notes due between 2029 and 2046, raising multiple billions of euros through senior and some subordinated unsecured paper.
These offerings matter because they help explain how Uber funds AV deployment and Delivery expansion without relying solely on internal cash generation. The structure and maturity profile of this debt keeps balance sheet risk in focus. Execution on AV rollouts, grocery partnerships and cost savings will need to support that additional leverage over time.
Uber Technologies' current analyst story points to forecast revenues of $80.0b and expected earnings of $11.6b by 2029. This is based on an assumed 13.1% yearly increase in revenue and a move in earnings from $9.6b today to $11.6b, which is a rise of about $2.0b over that period.
Uncover why Uber Technologies' fair value indicates a 42% potential upside to its current price that could narrow quickly.
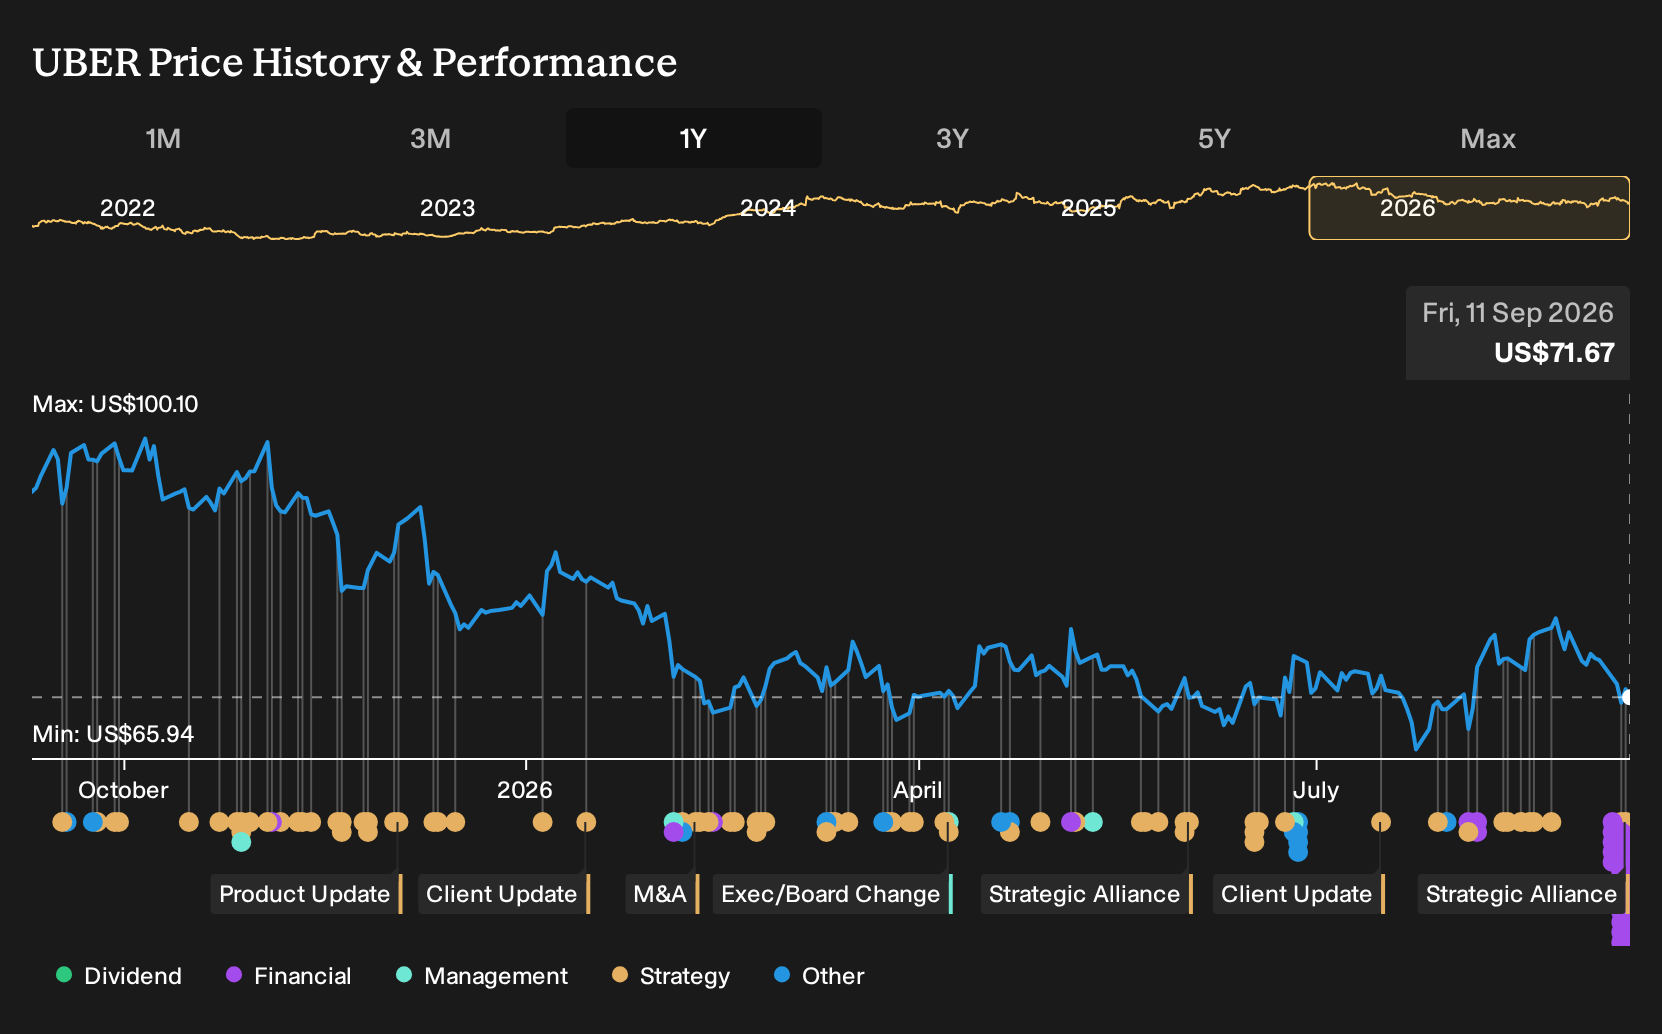
Exploring Other Perspectives
You just saw how consensus analysts frame Uber Technologies around AV execution and debt funded expansion. The lowest forecasts lean hard into margin risk from AV spending. They were modeling only 6.3% annual revenue growth to about US$66.4b and earnings of US$8.2b by 2029, so that group is likely to reassess in light of this Madrid permit and bond funding news.
Explore 28 other Uber Technologies fair value estimates, including one that suggests it could be worth just $77.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Uber Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Uber Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Uber Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Uber Technologies?
Once you have formed a view on Uber Technologies, it often helps to benchmark that thinking against other companies with different risk and return profiles. The Simply Wall St Screener lets you quickly filter by quality, balance sheet strength, income focus and more so you can build a wider watchlist that matches your own goals.
- If capital preservation is high on your list, start with stocks that aim for resilience by checking a 11 resilient stocks with low risk scores that can help you spot companies with steadier risk profiles.
- If you want potential mispricing opportunities, scan through a 15 high quality undiscovered gems that may highlight strong fundamentals that are not widely followed yet.
- If balance sheet strength matters most to you, filter for companies with robust finances using a list of solid balance sheet and fundamentals (23 results) that keeps the focus on financial durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com