


Chefs' Warehouse (CHEF), Why Is The Stock Back In Focus?
Chefs' Warehouse (CHEF) has drawn attention after recent trading left the stock near a last close of $110.45, with investors weighing solid multi year total returns against current valuation signals.
Chefs' Warehouse has seen sharp share price momentum this year, with a year to date share price return of 77.03% and a 1 year total shareholder return of 66.92%. The 3 year total shareholder return of 285.51% points to powerful longer term compounding that investors are now weighing against richer valuation signals.
Scan beyond Chefs' Warehouse and compare this momentum story with a curated set of 32 high quality undervalued stocks that pair stronger balance sheets with more compressed valuations.
Chefs' Warehouse now trades near its recent high after a strong multi year run, leaving investors to weigh business progress against the possibility that sentiment has simply run ahead of the fundamentals.
Most Popular Narrative: 5.2% Undervalued
Chefs' Warehouse is trading at $110.45 against a widely followed fair value estimate of about $116.56, which puts a modest valuation gap in focus for investors weighing the recent surge.
Operational improvements such as investments in procurement, digital ordering (now ~60% of specialty sales), predictive demand forecasting, and inventory optimization technology are already contributing to margin efficiency and scalability, laying the groundwork for further net margin and earnings expansion as these initiatives mature.
Investors may want to understand what kind of revenue trajectory and profit margin lift would need to align to support that fair value and beyond. The narrative refers to a specific blend of top line growth, richer mix and future earnings multiples that are usually reserved for faster growing retailers. It is worth examining which assumptions carry the most weight in this model and how sensitive that $116.56 figure is to small tweaks.
Result: Fair Value of $116.56 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Chefs' Warehouse story can change quickly if labor costs rise more than expected or if recent acquisitions take longer to integrate cleanly.
Find out about the key risks to this Chefs' Warehouse narrative.
Another View: Chefs' Warehouse Through Earnings Multiples
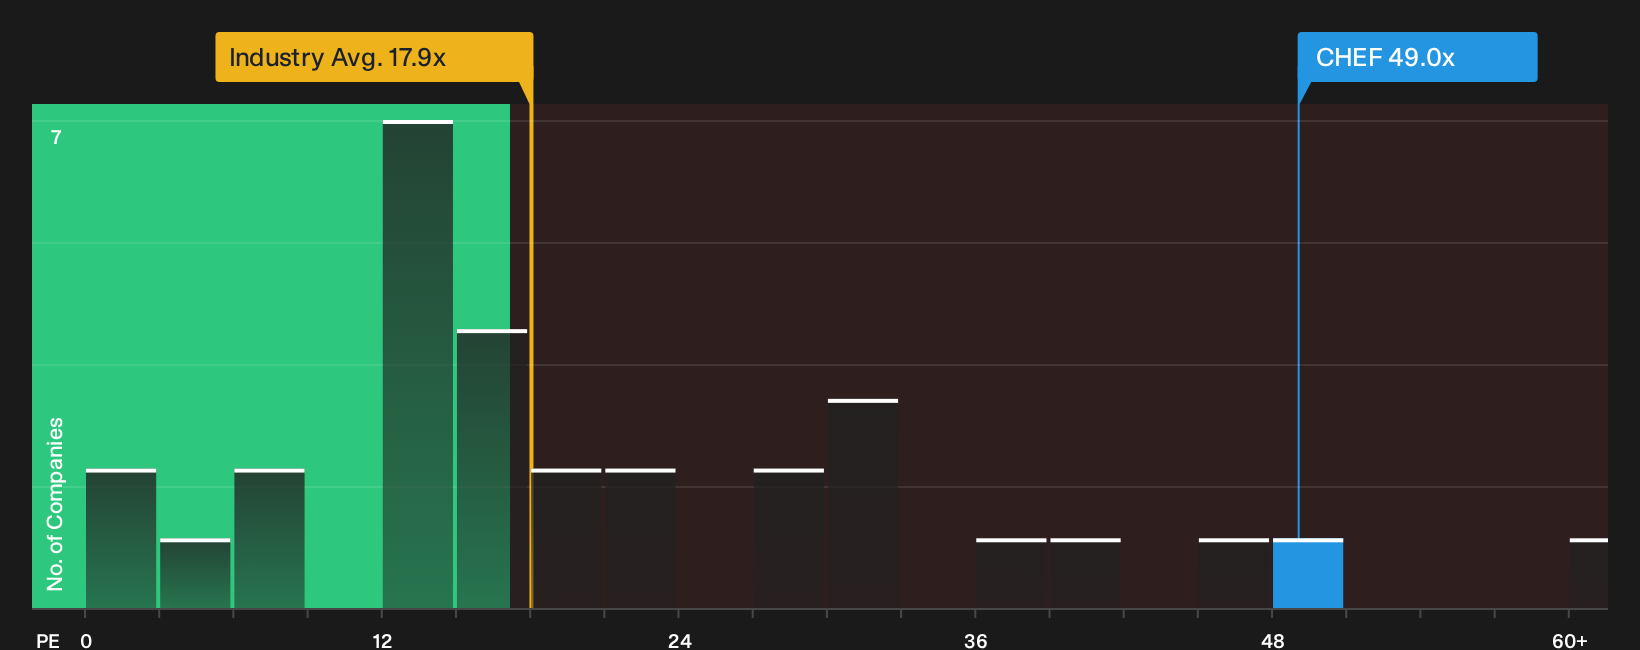
Chefs' Warehouse screens very differently when the focus shifts from future cash flows to what investors are paying for current earnings. The stock trades on a P/E of 49x, compared with 28.7x for peers, the US Consumer Retailing average of 17.9x, and a fair ratio estimate of 27.2x that the market could move toward over time. That kind of gap tilts the conversation toward valuation risk rather than upside, so the question becomes whether the quality of the story really justifies paying almost double the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong momentum and richer valuation signals can feel exciting, yet the real edge comes from checking the numbers yourself and deciding what truly matters for Chefs' Warehouse. To frame that view quickly with both sides of the story in mind, start with the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Chefs' Warehouse?
If you stop with Chefs' Warehouse, you risk missing other opportunities that better fit your goals, risk comfort, and timeline, so widen your search now with fresh ideas.
- Target higher income potential by focusing on companies that aim to sustain strong payouts through the 6 dividend fortresses.
- Spot resilient balance sheets and steady fundamentals before the crowd by running the list of solid balance sheet and fundamentals (23 results).
- Get ahead of the market by scanning for overlooked quality businesses using the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com