


Why Procter & Gamble (PG) Is Getting Attention Today
Procter & Gamble (PG) is back in the spotlight after new Oral-B iO product details highlighted a strong emphasis on premium oral care technology, prompting fresh questions about how this kind of branded innovation feeds into the stock’s valuation.
Recent price action shows that Procter & Gamble’s 1-day share price return of 1.61% sits against a softer 90-day share price return of 3.45% and a 1-year total shareholder return that is down 5.29%. This suggests momentum has cooled even as Oral-B iO and other launches attempt to refresh growth expectations.
See how Procter & Gamble’s premium Oral-B iO push compares with other branded consumer giants trying to reignite growth using pricing power and product upgrades by reviewing the 32 high quality undervalued stocks.
Bulls point to Procter & Gamble’s product engine and premium pricing power. Bears highlight recent underperformance and already rich expectations. Which story does the current valuation actually support, based on the numbers investors can see today?
Most Popular Narrative: 35.1% Overvalued
Procter & Gamble last closed at $145.27 while the most followed valuation storyline on Simply Wall St pegs fair value closer to $107.52, creating a sizeable gap investors are trying to understand.
From what we have seen I can also go a step further and extrapolate that a possible reduction of its exposure to the Beauty segment (with a decreasing operating margin) and an increase of exposure to the Grooming business segment (with an increasing operating margin) would be a logic step in improving the overall operating margins for the company. However, from what is presented in front of us, this does not seem to be the current or projected situation.
The central story here is simple. A mature franchise with wide-moat brands, steady but modest growth assumptions, and firm margin expectations is being plugged into a detailed cash flow, earnings and dividend model that points to a lower fair value than today’s share price. The tension between that slow and steady forecast and the premium the market currently pays is what drives this narrative.
Result: Fair Value of $107.52 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Procter & Gamble’s overvaluation case could be challenged if competitive pressure compresses margins faster than expected or if demand for premium Oral-B iO products disappoints.
Find out about the key risks to this Procter & Gamble narrative.
Another View On Procter & Gamble’s Valuation
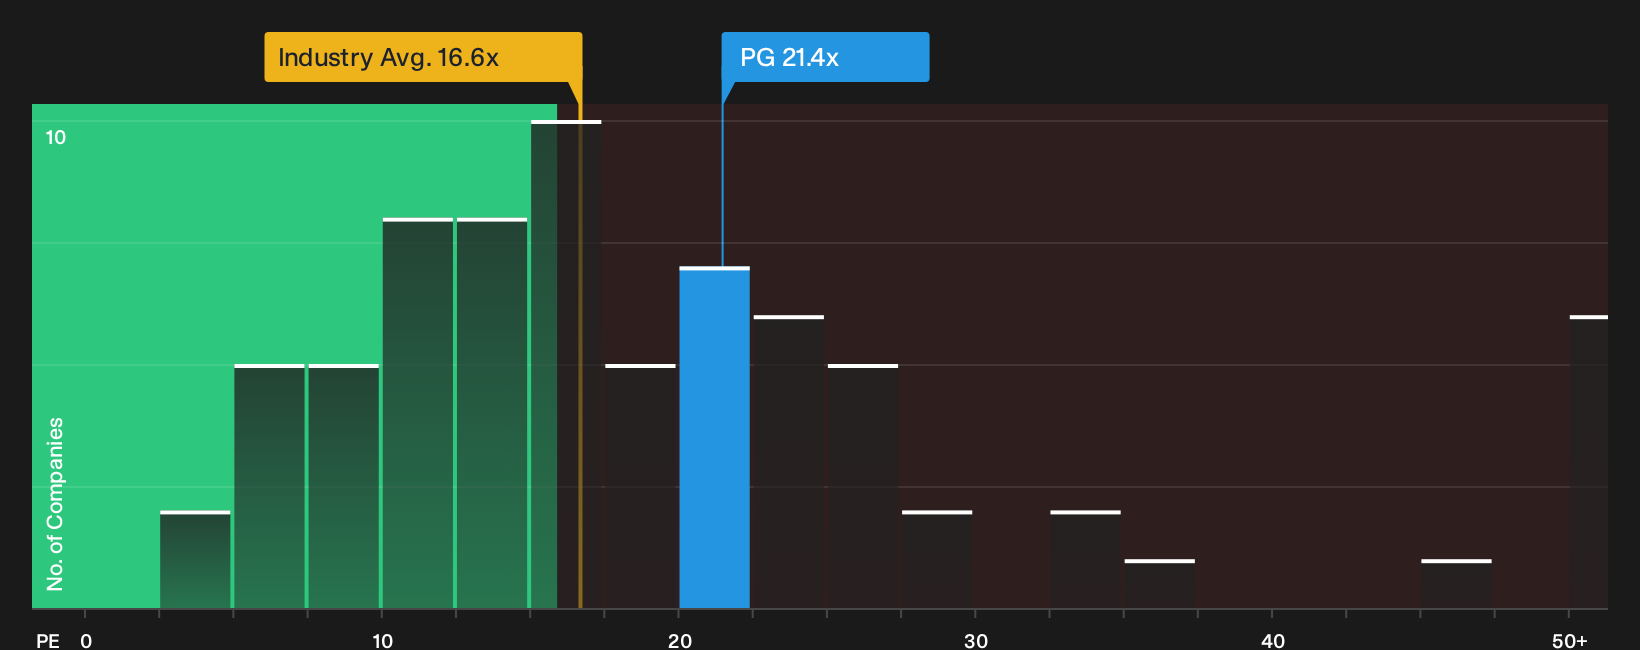
The most followed Simply Wall St narrative flags Procter & Gamble as 35.1% overvalued, yet the market signals are not one sided. On current numbers, PG trades on a P/E of 21.4x versus a peer average of 25.3x and a fair ratio of 25.4x, which points to a discount rather than a premium.
If the P/E were to drift closer to that fair ratio, investors would be paying more for the same earnings stream, which changes the risk reward trade off for anyone treating PG as a high quality compounder.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Procter & Gamble can create hesitation, yet the fastest way to cut through that noise is to weigh the core data yourself and decide where you stand. To see both sides of the story in one place, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Procter & Gamble?
If Procter & Gamble helps you frame what quality looks like, you can broaden your watchlist by scanning other opportunities that fit clear, data driven filters.
- Target stable compounding by reviewing companies screened as 11 resilient stocks with low risk scores that aim to balance return potential with measured downside.
- Hunt for resilient balance sheets through the list of solid balance sheet and fundamentals (23 results) so you can focus on businesses built to handle shocks.
- Get ahead of the crowd by checking the 15 high quality undiscovered gems before the market pays closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com